In 2025, state budget revenue exceeded the estimate by 36.8%, the budget deficit stood at 3.1% of GDP, and public debt amounted to 33.35% of GDP. However, the audit of the 2025 state budget final accounts revealed persistent shortcomings in revenue management, expenditure administration, and public investment disbursement.
Continuing the second session of the National Assembly, on the afternoon of October 17, State Auditor General Nguyen Huu Nghia presented the State Audit Report on the 2026 State Budget Final Accounts to the National Assembly.
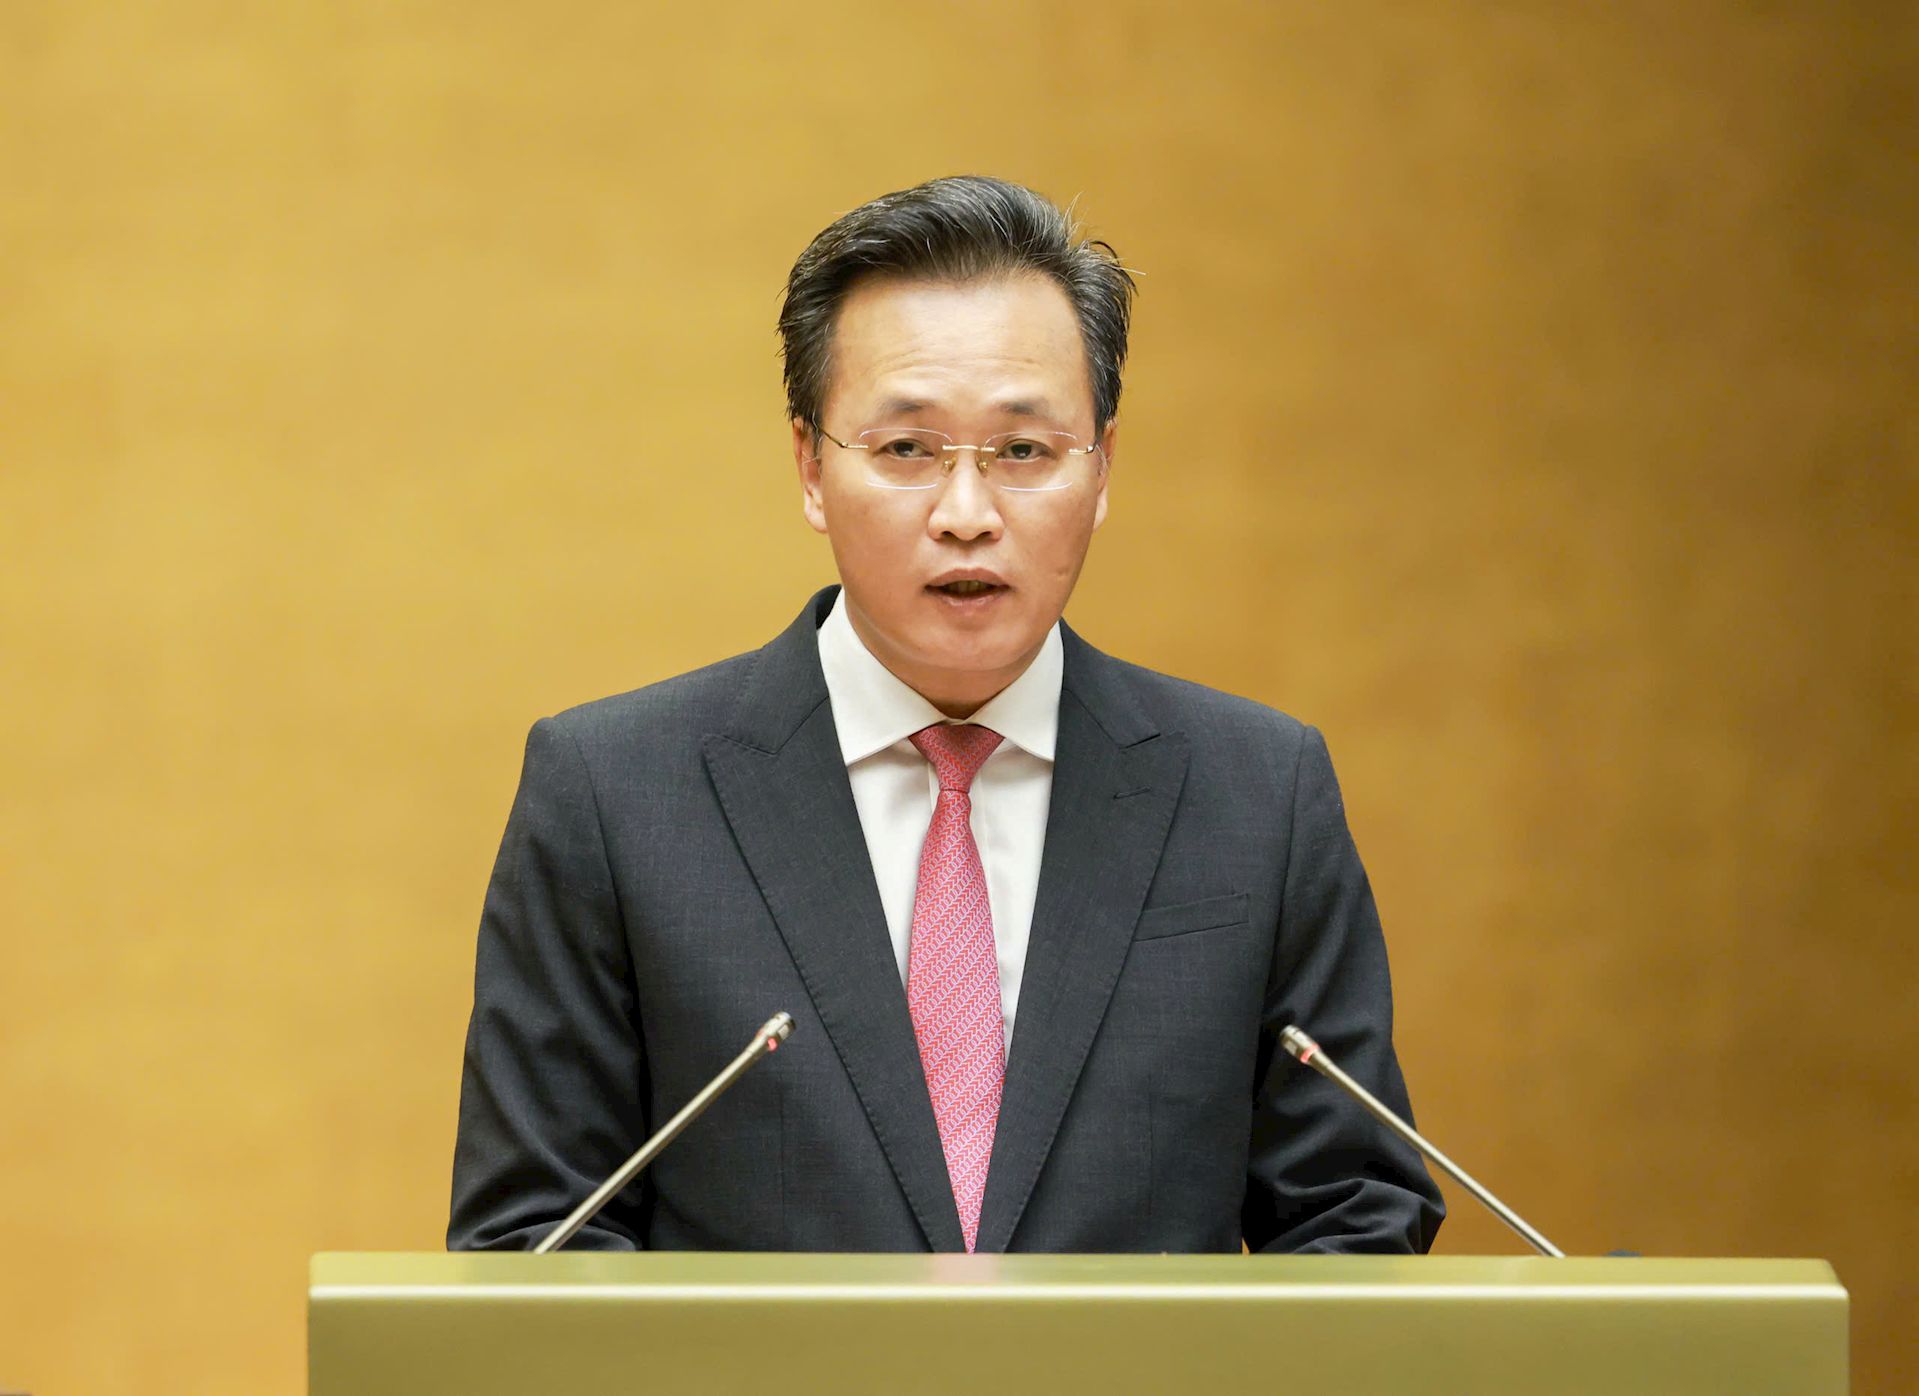
State Auditor General Nguyen Huu Nghia presents the State Audit Report on the State Budget Final Accounts for 2026. Photo: Nhu Y
Revenue Rises, but Expenditure Discipline Remains Weak
The State Auditor General stated that, despite numerous difficulties and challenges and adverse impacts from both domestic and external economic factors, Vietnam achieved several positive results in implementing its state budget estimates in 2025.
Notably, state budget revenue continued to grow, reaching 21% of GDP, up from 17.9% in 2024. Revenue exceeded the estimate by 36.8%, ensuring sufficient resources to finance socioeconomic development, foreign affairs, national defense, security, and social welfare.
State budget revenue exceeded estimates across all three sectors of the economy: state-owned enterprises surpassed their estimates by 3%; foreign-invested enterprises by 21.7%; and the non-state sector by 35.7%. Revenue from import and export activities exceeded the estimate by 35.9%. State budget expenditure also expanded, increasing by 4.6% compared with the estimate.
Overall, Vietnam's state budget remained relatively stable, safe, and sound in 2025, with the budget deficit at 3.1% of GDP and public debt at 33.35% of GDP. These results helped strengthen macroeconomic foundations and support rapid and sustainable economic development, particularly the goal of achieving double-digit growth in the new economic cycle, according to the State Auditor General.
However, alongside these positive results, the audit of the 2025 state budget final accounts identified several issues of concern.
State Auditor General Nguyen Huu Nghia pointed out that the expenditure structure had not improved compared with 2024: the share of investment expenditure continued to decline, while recurrent expenditure increased.
State budget management and administration remained subject to limitations and weaknesses, with fiscal discipline not always strictly enforced. In some cases and localities, requirements for the economical and efficient use of state budget funds, public assets, and public finances were not adequately observed. Budget funds were used outside approved estimates, while procurement and expenditure failed to comply with prescribed standards, limits, spending categories, assigned tasks, or eligible beneficiaries.
The State Auditor General also highlighted numerous outstanding issues in public investment, spanning project preparation, implementation, and completion.
State budget revenue management continued to face significant shortcomings, particularly in land, mineral resources, taxation, customs, and e-commerce. The structure of domestic revenue had yet to become truly stable and sustainable. Revenue from production and business activities, taxes, and fees remained relatively limited, while revenue from land, mineral resources, and land use accounted for a substantial share of domestic revenue.
The central budget's leading role had not improved and was even showing signs of weakening.
Large Carryovers and Rising Tax Arrears
According to the State Audit Office of Vietnam (SAV), while the state budget had to increase borrowing to cover the deficit, ineffective budget management and use could further increase borrowing requirements and expenditure.
View of the session. Photo: Nhu Y
Budget estimates continued to be allocated but not fully utilized, resulting in substantial carryovers that increased in both absolute and relative terms. Public investment disbursement remained slow, with allocated capital plans not fully executed, particularly for loan-funded projects. Advance payments accounted for a particularly large proportion of public investment disbursement in 2025, reaching 31%.
Tax arrears remained substantial and increased compared with 2024. Tax arrears managed by tax authorities alone amounted to nearly VND 245.5 trillion, up 20% from 2024 and equivalent to 10.58% of domestic revenue.
National and state budget financial security remained under control in 2025, but several risk factors warranted attention. The need to mobilize resources to support rapid economic growth was putting upward pressure on the budget deficit, public debt, and debt-servicing obligations. Other concerns included losses, waste, and inefficient use of state budget funds; the concentration of government bond issuance in 2025 on 10-year maturities, which could create substantial repayment pressure upon maturity; and rising market interest rates, which increased the state's borrowing costs.
From a materiality perspective, the 2025 State Budget Final Accounts Report fully, accurately, and objectively reflected total revenue, total expenditure, the state budget deficit, and total state budget borrowing, State Auditor General Nguyen Huu Nghia emphasized.
Based on the audit findings, the State Audit Office of Vietnam recommended that the National Assembly consider approving the 2025 state budget final accounts using the figures submitted by the Government, as follows:
-
Total state budget revenue: VND 4,267,354 billion.
-
Total state budget expenditure: VND 4,560,931 billion.
-
State budget deficit: VND 400,163 billion, equivalent to 3.1% of actual GDP.
-
Total state budget borrowing: VND 763,909 billion.