The development of big data and artificial intelligence (AI) is driving changes in the way public-sector audits are conducted. The shift from traditional auditing to data-driven auditing involves not only the application of technology but also requires changes in mindset, professional methodologies and auditors' capabilities. In this process, integrated infrastructure and centralized data are fundamental prerequisites, while independent professional judgment remains the decisive factor in determining the value of audit results.
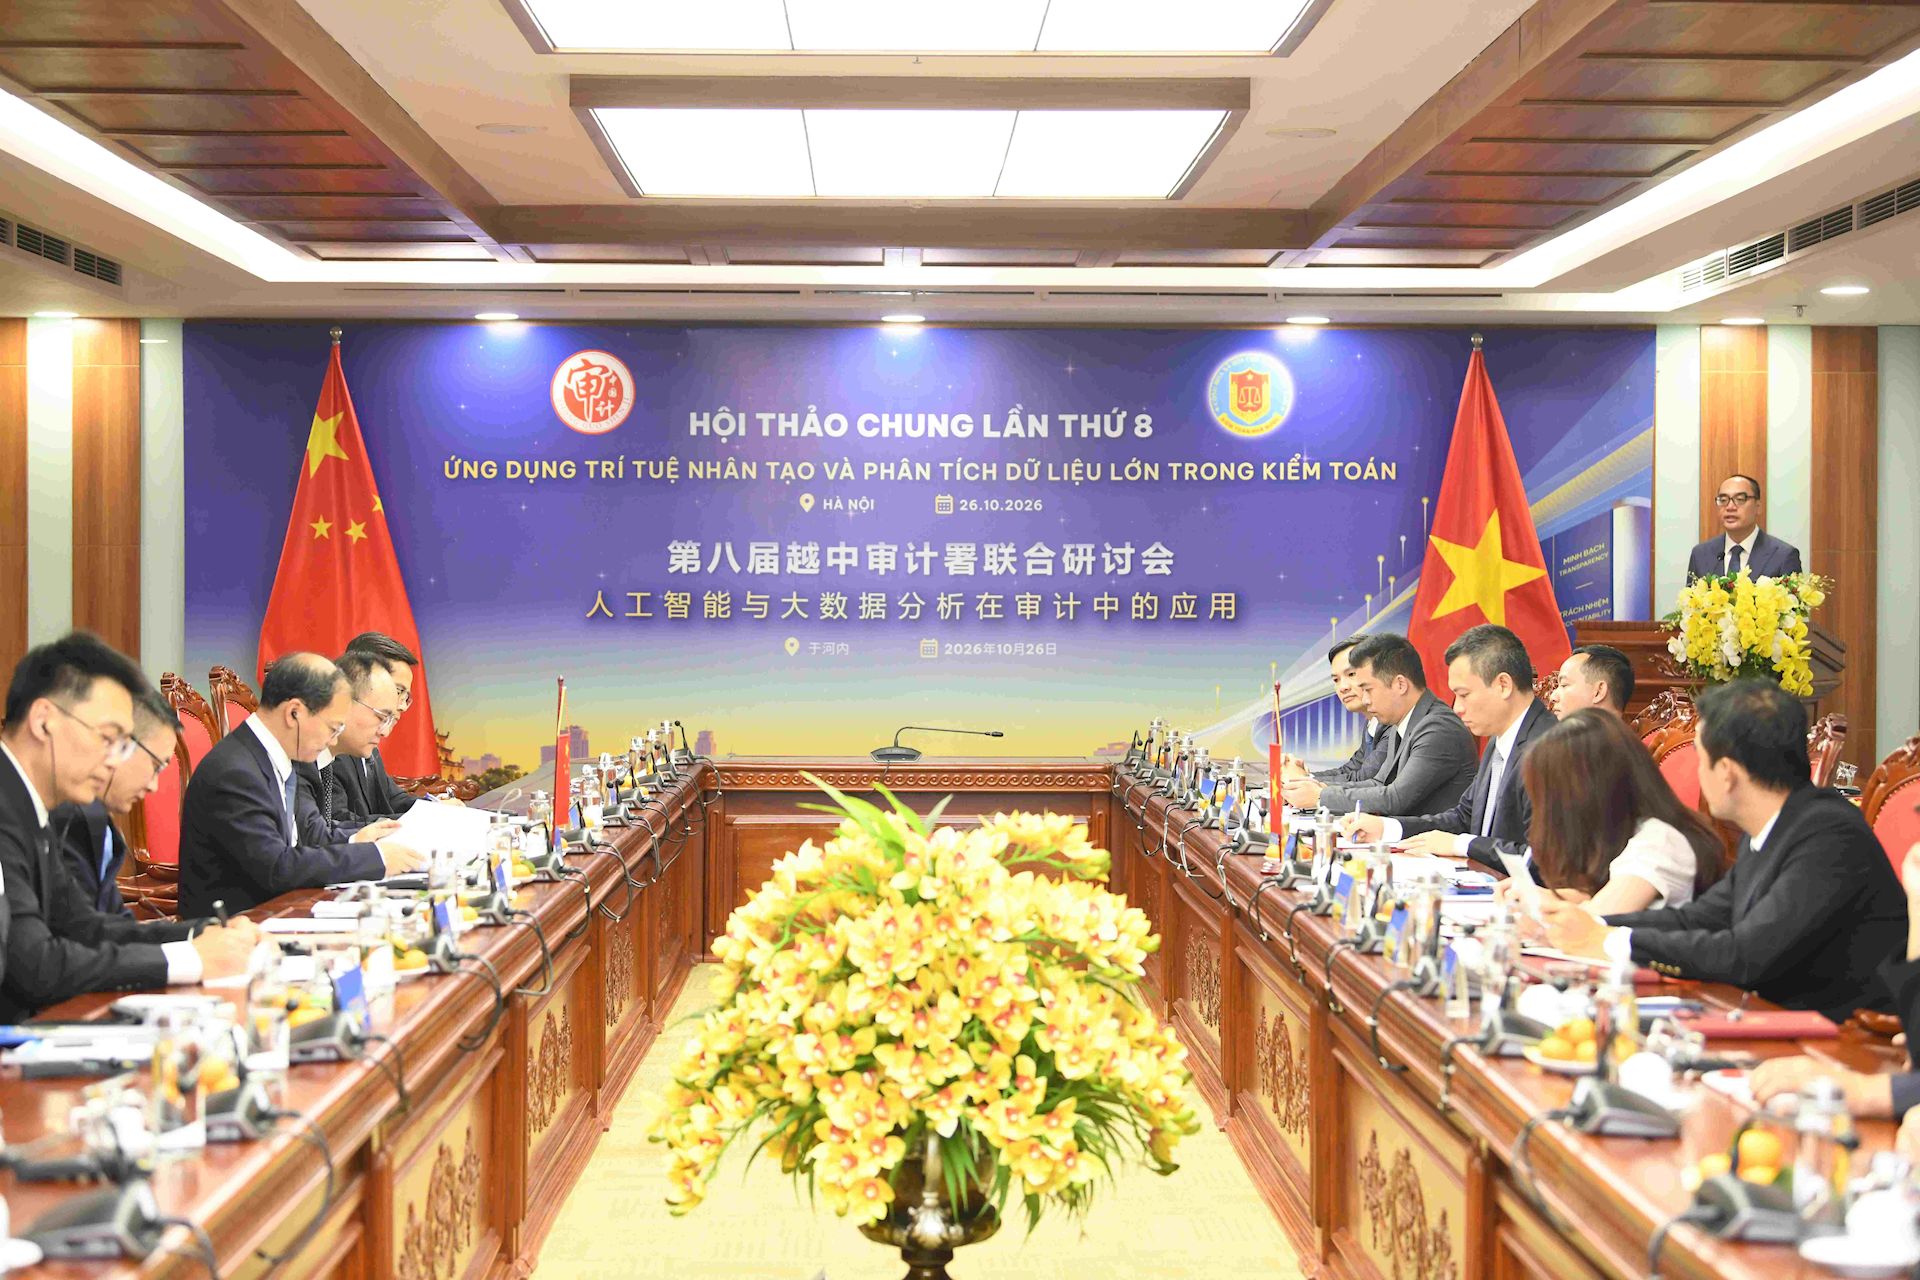
The 8th Joint Seminar between the State Audit Office of Vietnam and the National Audit Office of China. Photo: N. LY
Transforming Audit Methodologies through a Data-Driven Foundation
As public financial and public asset management becomes increasingly digitalized, digital auditing and big data analytics offer opportunities to enhance oversight capabilities, identify risks and determine audit priorities based on systematic information. Unlike the examination of individual supporting documents, data analytics enables auditors to examine transaction patterns, cash flows and relationships among entities. This allows auditors to detect anomalies, identify high-risk areas and allocate resources to matters requiring further verification.
Speaking at the 8th Joint Seminar with the National Audit Office of China (CNAO) on the application of AI and big data in auditing, held on the sidelines of the International Seminar “Supreme Audit Institutions in the New Context: Vision, Institutions and Innovation”, Deputy Auditor General of the State Audit Office of Vietnam (SAV) Bui Quoc Dung emphasized: “The most significant change lies not only in technology, but also in the way we think about and approach auditing: shifting from examining what has already happened to proactively identifying potential risks; and from checking individual files and transactions to conducting comprehensive analyses and identifying relationships within datasets.”
This shift expands analytical capabilities, but it does not mean that all data can be examined comprehensively or that every anomaly indicates a violation. The value of this new approach lies in its ability to help auditors identify risks on a sound basis, determine appropriate audit priorities and improve the quality of examination and verification. This is also an important direction in the modernization of SAV's operations.
To ensure the effectiveness of data-driven auditing, integrated technological infrastructure and centralized databases play a foundational role. According to Mr. Nguyen Van Quang, Deputy Director of SAV's Information Technology Department, data provides the basis for moving away from an approach that relies on the provision of individual documents towards the exploitation and cross-checking of electronic information, thereby supporting risk identification and improving audit efficiency.
In Vietnam, SAV has initially established a centralized Audit Data Repository containing more than 100 million records, connecting and cross-checking data from the State Treasury, the tax administration system, the budget and treasury management system, Vietnam Social Security and the National Public Service Portal. SAV has also begun piloting the combination of robotic process automation (RPA) and AI in a thematic audit of information technology supporting digital transformation in 13 provinces and cities.
However, the effectiveness of data exploitation still depends on the degree of consistency within the legal framework, the ability of different sectors to share and standardize information, the quality of input data and auditors' analytical capabilities. Information security and cybersecurity are also ongoing requirements, particularly when data is connected and processed on a large scale.
Sharing CNAO's experience at the 8th Joint Seminar, Mr. Pan Haiyang, Deputy Director of the department responsible for electronic data auditing, stated that building a data repository involves more than simply collecting and storing information. It also requires mechanisms for regular updates, standardized formats and assessments of the data's practical value and usability.
CNAO maintains a mechanism for periodically collecting data from 16 ministries and government agencies, while developing data infrastructure and AI tools to support various stages of the audit process. Organizing data by sector, integrating multiple information sources and developing analytical tools tailored to professional requirements create favorable conditions for expanding the use of data in auditing activities.
Regarding experience in developing regulations governing data collection and processing and organizing network systems, CNAO Deputy Auditor General Guo Xi stated that data must be managed according to different levels and scopes of access. Data exploitation must be linked to assigned duties, security procedures and users' responsibilities.
Therefore, developing digital auditing requires SAV not only to invest in infrastructure but also to establish a comprehensive data governance framework covering the legal basis, procedures for data collection, standardization, storage, exploitation and information protection. Data quality and the verifiability of results must be ensured from the outset, as these are decisive factors in determining the reliability of subsequent analyses.
The key to successful digital transformation lies not only in technological infrastructure but also in people. Future auditors do not necessarily need to become technology experts, but they must be capable of exploiting data, using analytical tools and working effectively with artificial intelligence.
Mr. Bui Quoc Dung, Deputy Auditor General of the State Audit Office of Vietnam
Technology Provides Support, Auditors Remain Accountable
On the foundation of standardized and properly governed data, AI can support information screening, automate repetitive tasks, identify anomalies and suggest areas requiring further examination. However, technology-generated results do not automatically constitute audit evidence; they must be verified through auditors' professional expertise. According to Mr. Huang Yuejin, Deputy Director of CNAO's Department of Laws and Regulations, data accuracy is essential to effective analysis. Before being incorporated into models, data must be assessed in terms of its origin, reliability and usability. Analytical results must be considered within their specific professional context and combined with auditors' assessments to determine which issues require further examination.
This requirement is particularly important when AI is used to analyze contracts, meeting minutes or large volumes of financial data. An anomaly alert may help narrow the scope of an audit, but it does not, in itself, prove that a violation has occurred. If input data is incomplete or inaccurate, the model may generate inappropriate alerts. Conversely, limitations in the data and models may prevent certain risks from being identified. Therefore, technology-generated results must be traceable, verifiable and cross-checked against original evidence.
Alongside data, human capabilities are a decisive factor in the effective application of technology. CNAO's training experience shows the importance of combining appropriate personnel recruitment, training in both professional and technological knowledge, and enhanced learning through practical audit experience. Digital auditing requires not only personnel proficient in technology but also a workforce capable of combining auditing expertise with the ability to exploit and evaluate data.
Deputy Auditor General Bui Quoc Dung emphasized: “The effectiveness of AI should not be assessed solely by the number of applications or the sophistication of the technology. Instead, it must be measured by tangible results in improving the quality of audit evidence and conclusions. Technology can assist auditors in analyzing data and detecting issues, but it cannot replace their professional responsibilities, assessments and professional judgment.”
For SAV, the development of digital infrastructure, the improvement of its centralized data repository and the expansion of AI applications must be implemented in parallel with the refinement of the legal framework, standardization of professional procedures, assurance of information security and enhancement of human resource quality. The application of technology should be evaluated based on its actual effectiveness, including its ability to identify risks, the quality of audit evidence, the efficiency of resource utilization and the reliability of audit results.
Digital transformation in auditing, therefore, is first and foremost about changing approaches and strengthening implementation capabilities. Infrastructure creates the necessary conditions, data provides the foundation and AI expands analytical capabilities; however, independent judgment and auditors' professional accountability remain the factors that safeguard the value of audit conclusions.