Commending the achievements made by the entire State Audit Office of Vietnam (SAV) in recent times, particularly the decisive efforts to reorganize its organizational structure and streamline its apparatus, State Auditor General Nguyễn Hữu Nghĩa called on all units to continue adhering closely to their established work plans to ensure the timely and high-quality completion of tasks, while strictly observing work discipline. He made these remarks while chairing the SAV’s online conference reviewing the performance of the entire sector in the third quarter of 2026 on the morning of October 12.
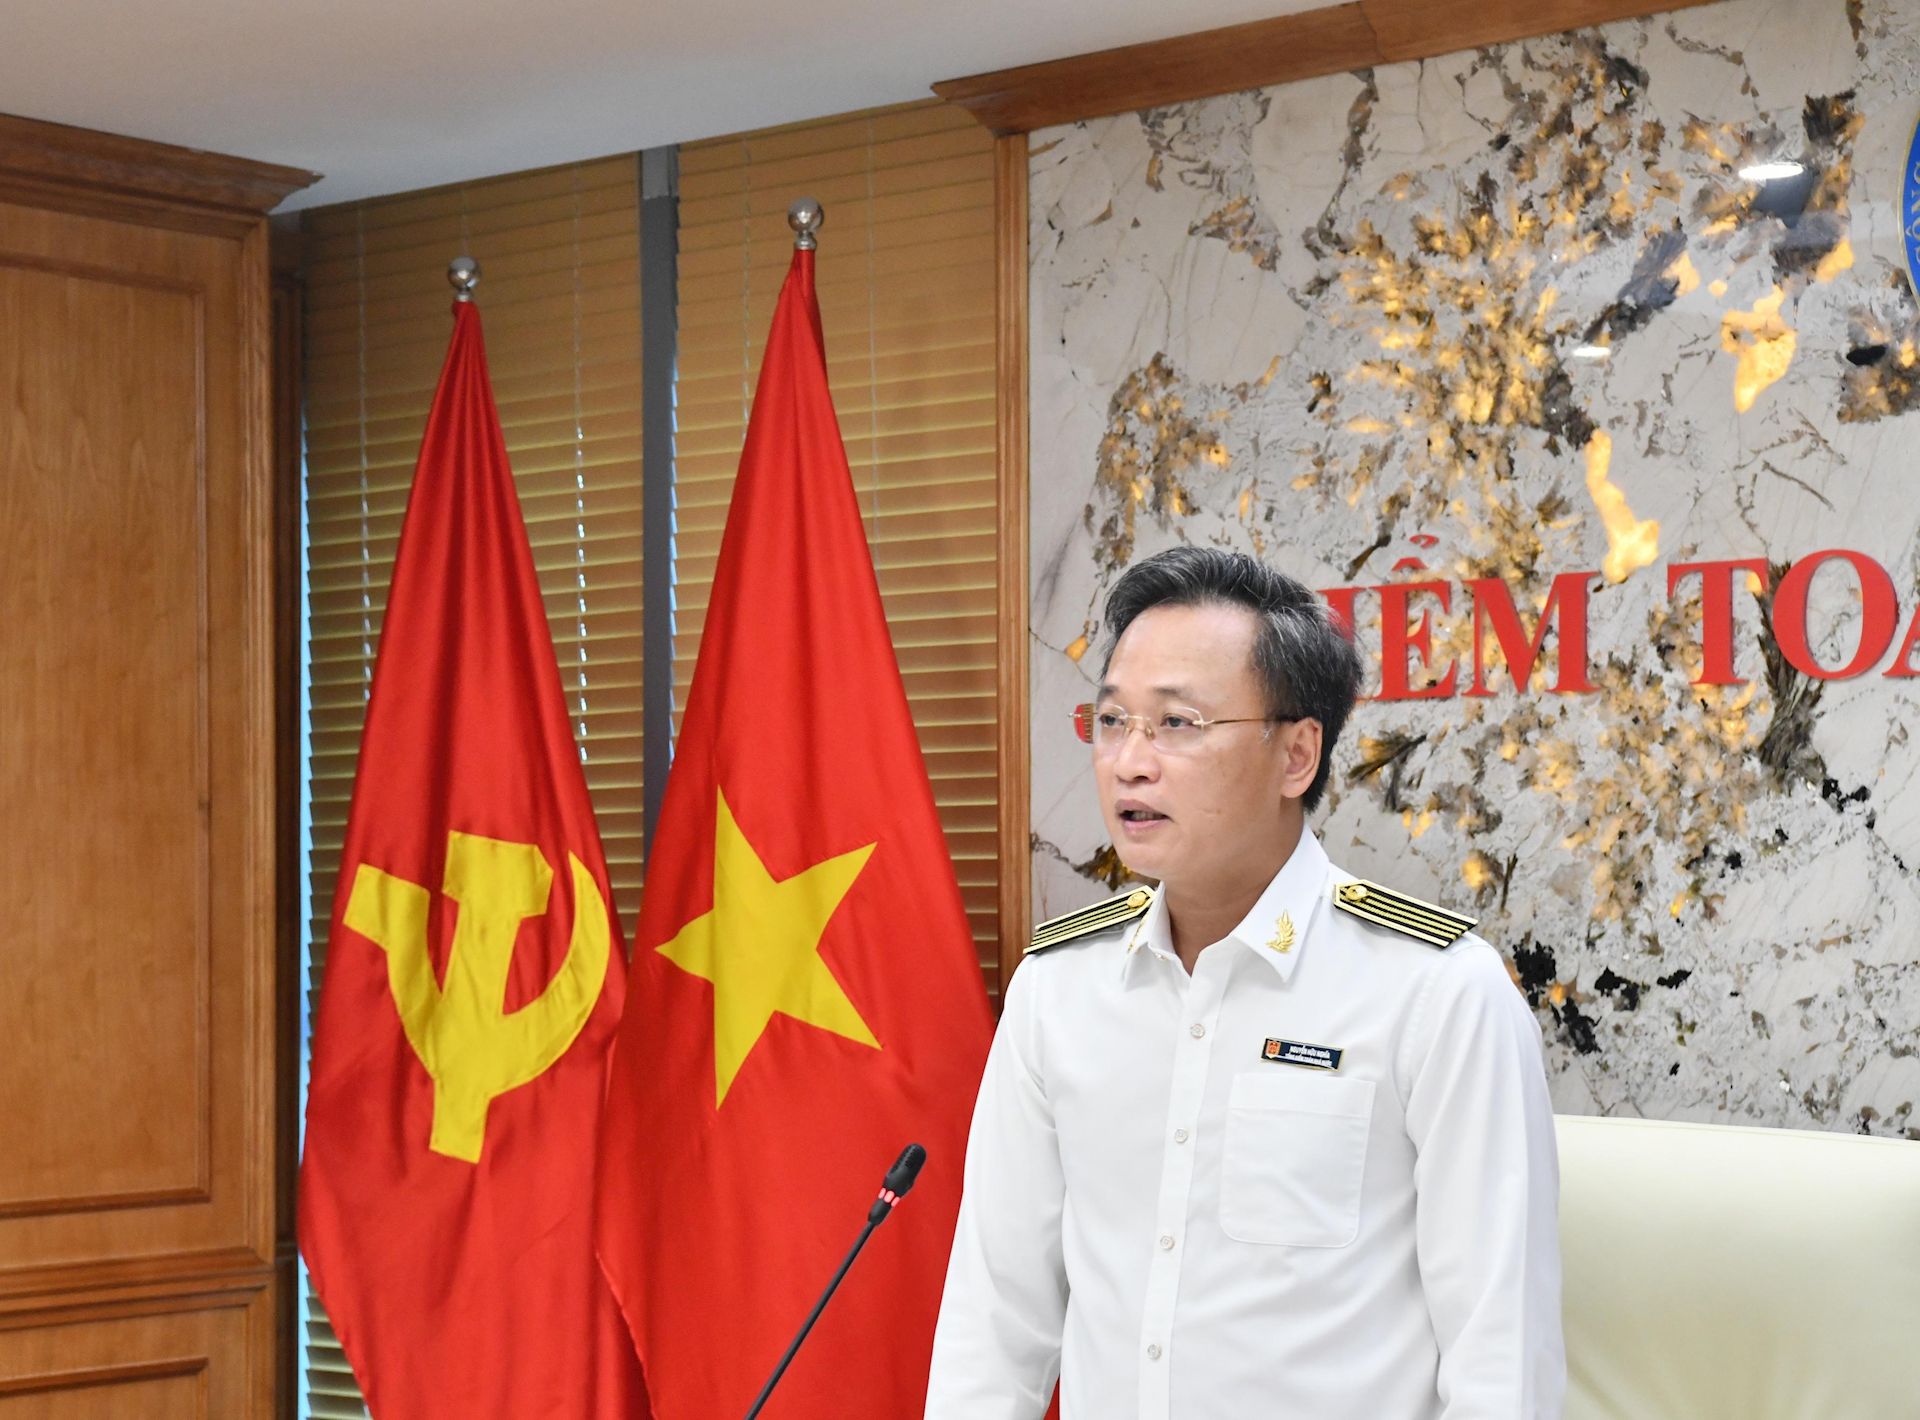
Member of the Party Central Committee, Secretary of the Party Committee, and State Auditor General Nguyễn Hữu Nghĩa chaired the conference and delivered the keynote directives. Photo: N. Loc
The conference was attended by Deputy State Auditors General and heads of departments and divisions from units across the SAV.
Decisively Implementing Organizational Restructuring Without Disrupting the Operations of the Entire Sector
In the third quarter of 2026, SAV-affiliated units closely followed the work program and directives of the SAV leadership, implementing tasks comprehensively across various areas and achieving numerous notable and breakthrough results.
Notably, at the 6th session of the National Assembly Standing Committee, the State Auditor General presented the SAV’s 2026 Performance Report, highlighting breakthrough achievements and positive changes. The report was carefully prepared and provided a comprehensive, in-depth assessment of the SAV’s activities during the first nine months of 2026. The results reflected the entire sector’s efforts to renew its thinking, strengthen awareness, and take decisive action to improve the effectiveness and efficiency of its political mandate. These efforts contributed to enhancing national public governance and strengthening discipline, accountability, and the effectiveness of public financial management, public asset management, and state budget administration.
In the first nine months of 2026 alone, the SAV recommended financial adjustments and other measures totaling nearly VND 114 trillion and USD 170 million, substantially exceeding the figures for the whole of 2025, which stood at over VND 41 trillion and USD 109 million. The implementation rate of recommendations concerning VND-denominated assets reached 79.09%, compared with only 58% in the same period of 2025, while the rate for USD-denominated assets reached 86.33%.
The SAV completed its second round of organizational restructuring and streamlining in accordance with Resolution No. 308a/NQ-UBTVQH dated July 27, 2026, concerning the number of specialized audit units, and renamed the Department of Audit Standards and Quality Control as the Department of SAV Policies under the SAV.
As a result, the SAV eliminated one additional department-level unit, reducing the number of specialized audit units by one, and cut 30 division-level units. At the same time, it adjusted the functions and responsibilities of its units to ensure a streamlined structure, fewer organizational and intermediate units, clearly defined personnel, tasks, responsibilities, authority, and deliverables, as well as full accountability for audit results within each assigned sector, field, and geographical area.
The restructuring and reorganization were completed within a very short period of just 15 days. The process was carried out with urgency, determination, transparency, and a systematic, coordinated approach, fostering consensus and unity while ensuring continuity, stability, and uninterrupted operations throughout the sector.
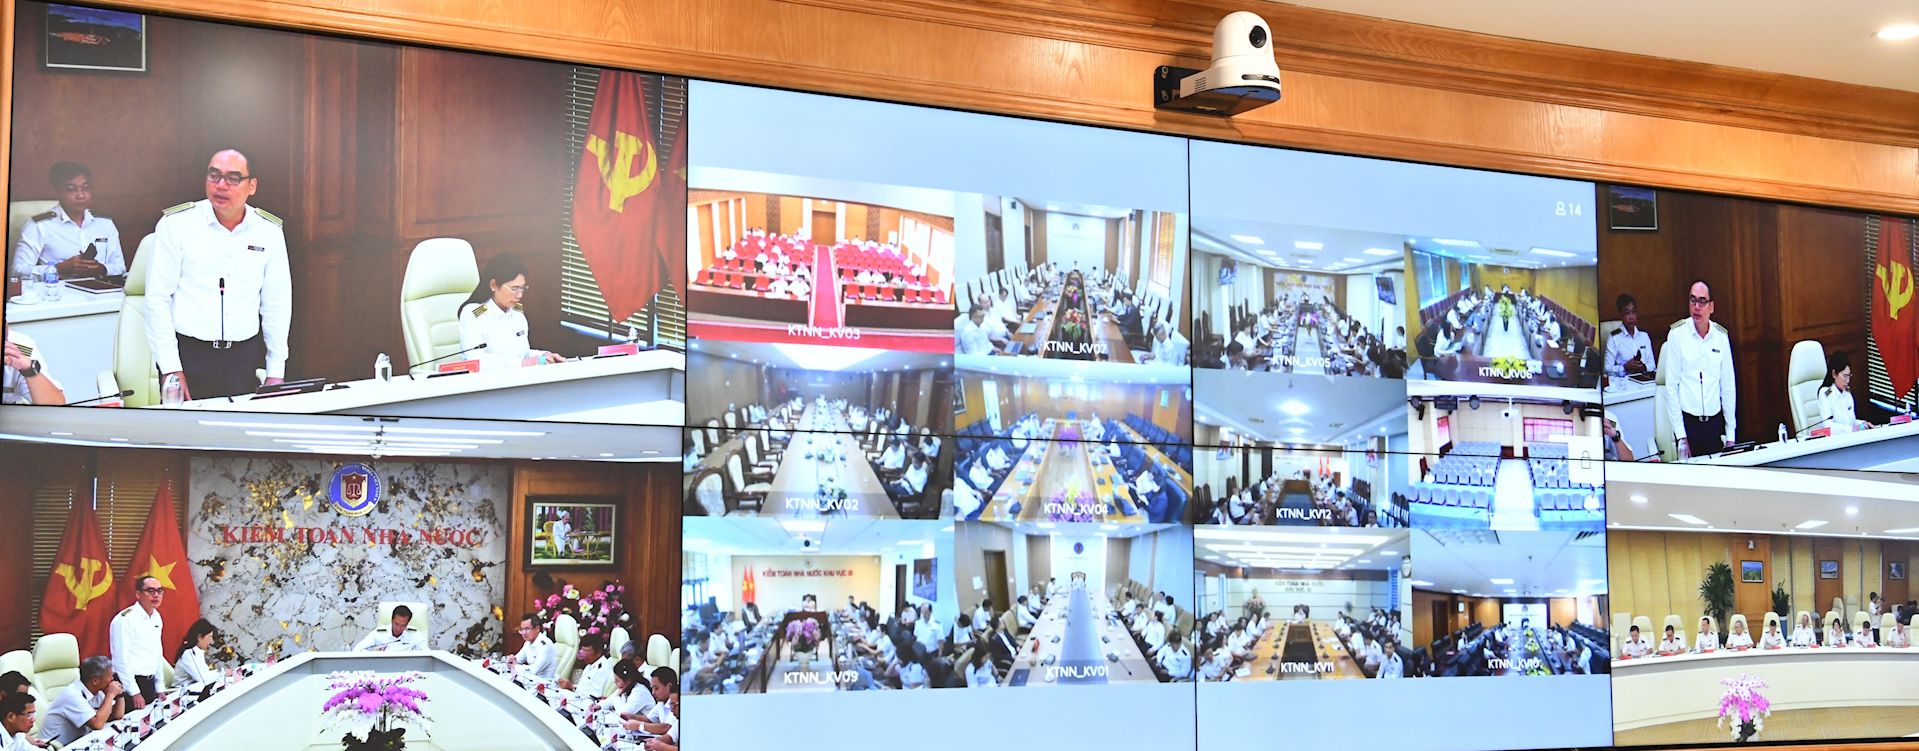
The conference was held in a hybrid format, combining in-person and online participation. Photo: N. Loc
The new organizational model became operational on August 15, 2026. Audit assignments and the SAV’s regular operations continued without any gaps in leadership, direction, or management, and without disruption to task implementation. This demonstrated the strong political resolve, organizational capacity, proactive adaptability, and high sense of responsibility of the SAV leadership, Party members, civil servants, public employees, and workers in implementing a major policy initiative of the Central Government.
In parallel, the SAV actively reviewed, amended, supplemented, and promulgated institutional frameworks, legal documents, and professional guidelines in a coordinated manner, aligning them with international practices and standards while meeting the requirements of digital transformation and innovation in governance and audit methodologies under the principle of “six clearly defined elements.”
The application of technology and digital transformation also achieved significant results. The SAV’s external relations and international cooperation activities continued to strengthen its role and standing in bilateral and multilateral cooperation and international forums, in line with the sector’s strategic orientations and political mandate. Meanwhile, training, scientific research, financial and logistical support, and communications activities continued to be actively implemented.
Focusing on Planned Tasks and Maintaining Public Service Discipline and Accountability
In his address, State Auditor General Nguyễn Hữu Nghĩa noted that, despite the substantial workload and increasingly demanding requirements during the third quarter and the first nine months of 2026, the entire sector had demonstrated determination, solidarity, initiative, and decisive action in implementing tasks under its work programs and plans. Significant achievements had been made, particularly in carrying out the annual audit plan, recommending financial adjustments, and monitoring and urging the implementation of audit conclusions and recommendations.
On behalf of the SAV leadership, the State Auditor General commended and acknowledged the efforts of all units, audit teams, civil servants, public employees, and workers throughout the sector.
Emphasizing that the fourth quarter of 2026 was a particularly critical period, with a substantial remaining workload and many tasks requiring completion within a short timeframe, the State Auditor General instructed specialized and regional audit offices to focus on completing the 2026 Audit Plan while ensuring both timeliness and quality.
Accordingly, audit units were required to accelerate the completion of audits under the 2026 Audit Plan and expedite the issuance of audit reports. All audits must be completed before October 31, 2026, and audit reports issued before December 31, 2026. No tasks may be carried over to 2027, except for supplementary audits.
The State Auditor General placed particular emphasis on auditing projects involving the construction of multi-level general education schools, especially boarding schools in assigned localities.
“This is a key task for 2026, playing an important role in assessing the effectiveness of public investment capital management and utilization, as well as the quality of implementation of the Party’s and State’s policies and guidelines,” the State Auditor General stressed.
To enhance the SAV’s role in providing policy advice and developing thematic audit reports, he instructed specialized audit offices to strengthen their professional guidance, share experience, and replicate effective models and practices throughout the sector.
The State Auditor General also called for stronger progress in implementing audit conclusions and recommendations, alongside greater public disclosure of audit results while ensuring information confidentiality.
At the same time, the entire sector must proactively prepare for the implementation of the 2027 Audit Plan beginning in the fourth quarter of 2026.
“Preparatory work is extremely important and plays a decisive role in audit outcomes. Therefore, it must begin early,” the State Auditor General emphasized.
Regarding advisory and support units, the State Auditor General requested that they continue carrying out their planned duties and any ad hoc assignments entrusted to them.
The Department of General Affairs was instructed to continue advising on, monitoring, and urging the implementation of the 2026 Audit Plan to ensure progress and quality, while promptly flagging audits that were at risk of falling behind schedule or had already been delayed.
The Department was also tasked with finalizing and submitting for issuance the audit reports on the 2025 State Budget Final Accounts and the 2025 Public Debt Report at the Ministry of Finance. In addition, it must finalize the audit report on the 2025 State Budget Final Accounts, together with the SAV’s opinions on the 2027 State Budget Estimates and the Central Government Budget Allocation Plan, for submission to the State Auditor General and subsequent reporting to the National Assembly at the second session of the 16th National Assembly.
The Department of Legal Affairs was instructed to continue monitoring and urging the units responsible for drafting documents under the SAV’s 2026 Legal Document Development Program to ensure compliance with assigned deadlines and quality requirements. It must also finalize and submit for promulgation the documents under its responsibility.
The Department of SAV Policies was tasked with finalizing and submitting the assigned documents for promulgation, monitoring and supervising the implementation of science and technology research tasks, and organizing seminars and evaluating completed research projects.
The Department of International Cooperation was directed to focus on preparations for bilateral and multilateral activities, particularly the international seminar entitled “Supreme Audit Institutions in a New Context: Vision, Institutions and Innovation.”
The SAV Inspectorate was required to continue implementing the third-round inspection and audit quality control plans for 2026 in accordance with approved arrangements, while further refining programs and plans for preventing and combating corruption, wastefulness, and other negative practices.
The Department of Personnel and Organization, the Information Technology Department, the State Audit newspaper, and other units were instructed to continue implementing their assigned tasks, ensuring timeliness, quality, and effectiveness.
Key priorities include improving personnel management, training, and professional development; accelerating digital transformation and the application of artificial intelligence while ensuring information security and confidentiality; and strengthening communications on the SAV’s results, contributions, and role in public financial and asset management, thrift practice, waste prevention, and anti-corruption efforts.
Communications activities should focus on thematic features and coordinated series of articles linked to the sector’s major political tasks, particularly the development and revision of the State Audit Law and the SAV Development Strategy.
The State Auditor General called on all organizations and individuals entrusted with responsibilities and delegated authority to adhere closely to their work plans, demonstrate a strong sense of responsibility, promote innovation and creativity, and improve the scientific rigor, efficiency, and effectiveness of their work.
The entire sector is expected to make every effort to successfully fulfill its 2026 work assignments, ensuring that all tasks are completed on schedule, to the required quality standards, and with maximum effectiveness.
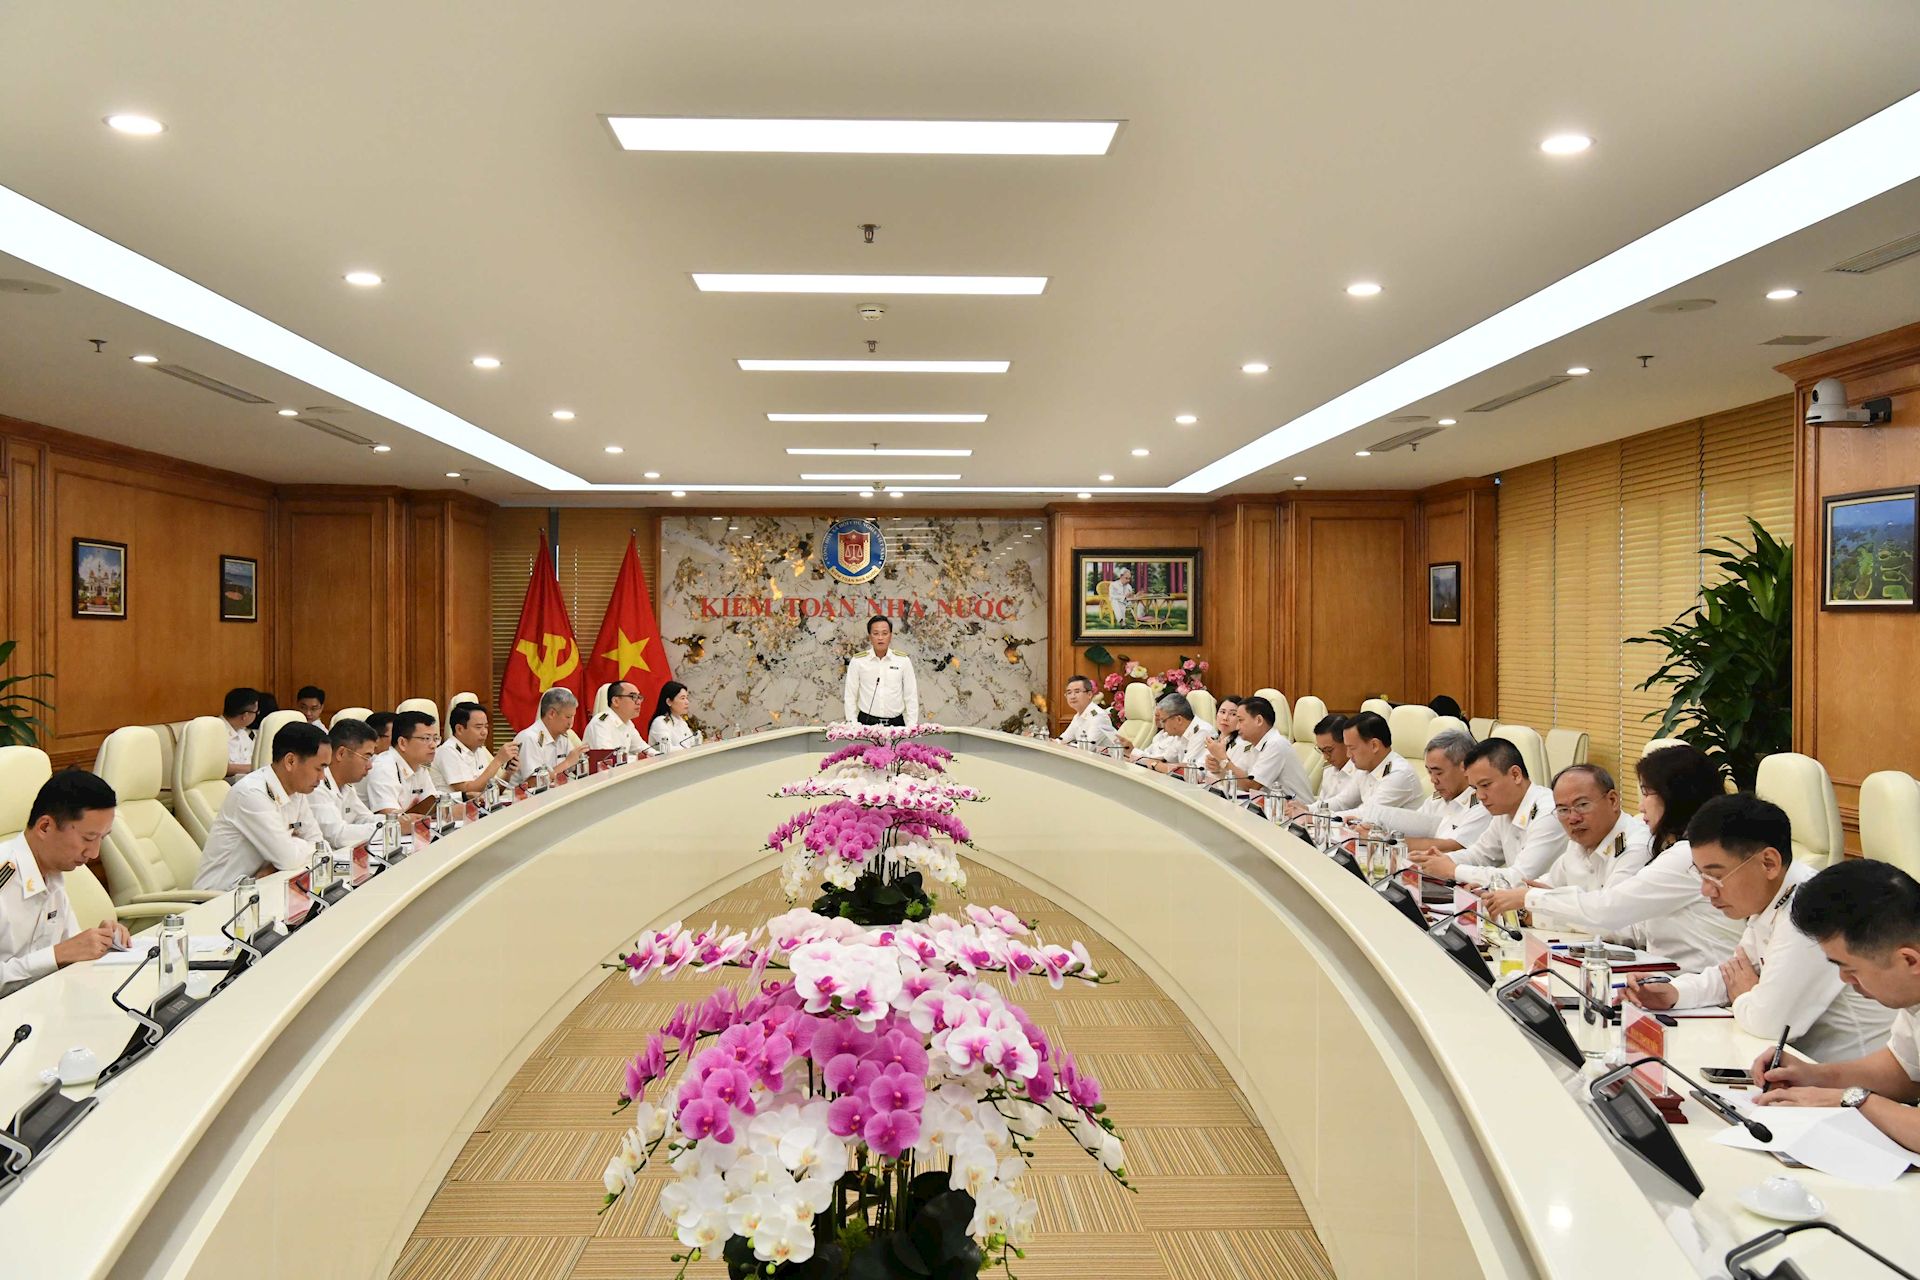
Overview of the conference. Photo: N. Loc
Regarding advisory units, the State Auditor General requested that they continue carrying out their assigned work plans and any ad hoc tasks entrusted to them. Specifically, the Department of General Affairs must continue advising on, monitoring, and urging the implementation of the 2026 Audit Plan to ensure timely and high-quality performance, while promptly flagging audits that are at risk of delay or have already fallen behind schedule.
The Department must also finalize and submit for issuance the audit reports on the 2025 State Budget Final Accounts and the 2025 Public Debt Report at the Ministry of Finance. In addition, it must finalize the audit report on the 2025 State Budget Final Accounts, together with the State Audit Office of Vietnam’s (SAV) opinions on the 2027 State Budget Estimates and the Central Government Budget Allocation Plan, for submission to the State Auditor General and subsequent reporting to the National Assembly at the second session of the 16th National Assembly.
The Department of Legal Affairs must continue monitoring and urging the units responsible for drafting documents under the SAV’s 2026 Legal Document Development Program to ensure that the assigned deadlines and quality requirements are met. It must also finalize and submit to the State Auditor General for promulgation the documents assigned to it.
The Department of SAV Policies must finalize and submit the assigned documents for promulgation, monitor and supervise the implementation of science and technology research tasks, organize seminars, and evaluate completed research projects.
The Department of International Cooperation must focus on preparations for bilateral and multilateral activities, particularly the international seminar entitled “Supreme Audit Institutions in a New Context: Vision, Institutions and Innovation.”
The SAV Inspectorate must continue implementing the third-round inspection and audit quality control plans for 2026 in accordance with the approved arrangements, while further refining programs and plans to prevent and combat corruption, wastefulness, and other negative practices.
The Department of Personnel and Organization, the Information Technology Department, the State Audit newspaper, and other units must continue carrying out their assigned tasks, ensuring timeliness, quality, and effectiveness. Priorities include improving personnel management, training, and professional development; accelerating digital transformation and the application of artificial intelligence while ensuring information security and confidentiality; and strengthening communications on the SAV’s achievements, contributions, and role in public financial and asset management, promoting thrift and preventing waste, and combating corruption and other negative practices. Communications activities should focus on thematic features and coordinated series of articles linked to the sector’s major political tasks, particularly the development and revision of the State Audit Law and the SAV Development Strategy.
The State Auditor General requested that all organizations and individuals assigned responsibilities and delegated authority closely follow their work plans, uphold their sense of responsibility, promote innovation and creativity, and improve the rigor, efficiency, and effectiveness of their work. The entire sector must strive to successfully fulfill its 2026 work assignments, ensuring timely completion, high quality, and effective results.