Although implementation rates have improved significantly, many audit recommendations remain outstanding due to bottlenecks in mechanisms, policies, and accountability for implementation. To ensure that recommendations go beyond reports and are fully implemented, the State Audit Office of Vietnam (SAV) is both tightening discipline and proactively coordinating with local authorities to resolve institutional obstacles and translate audit findings into practical improvements in management.
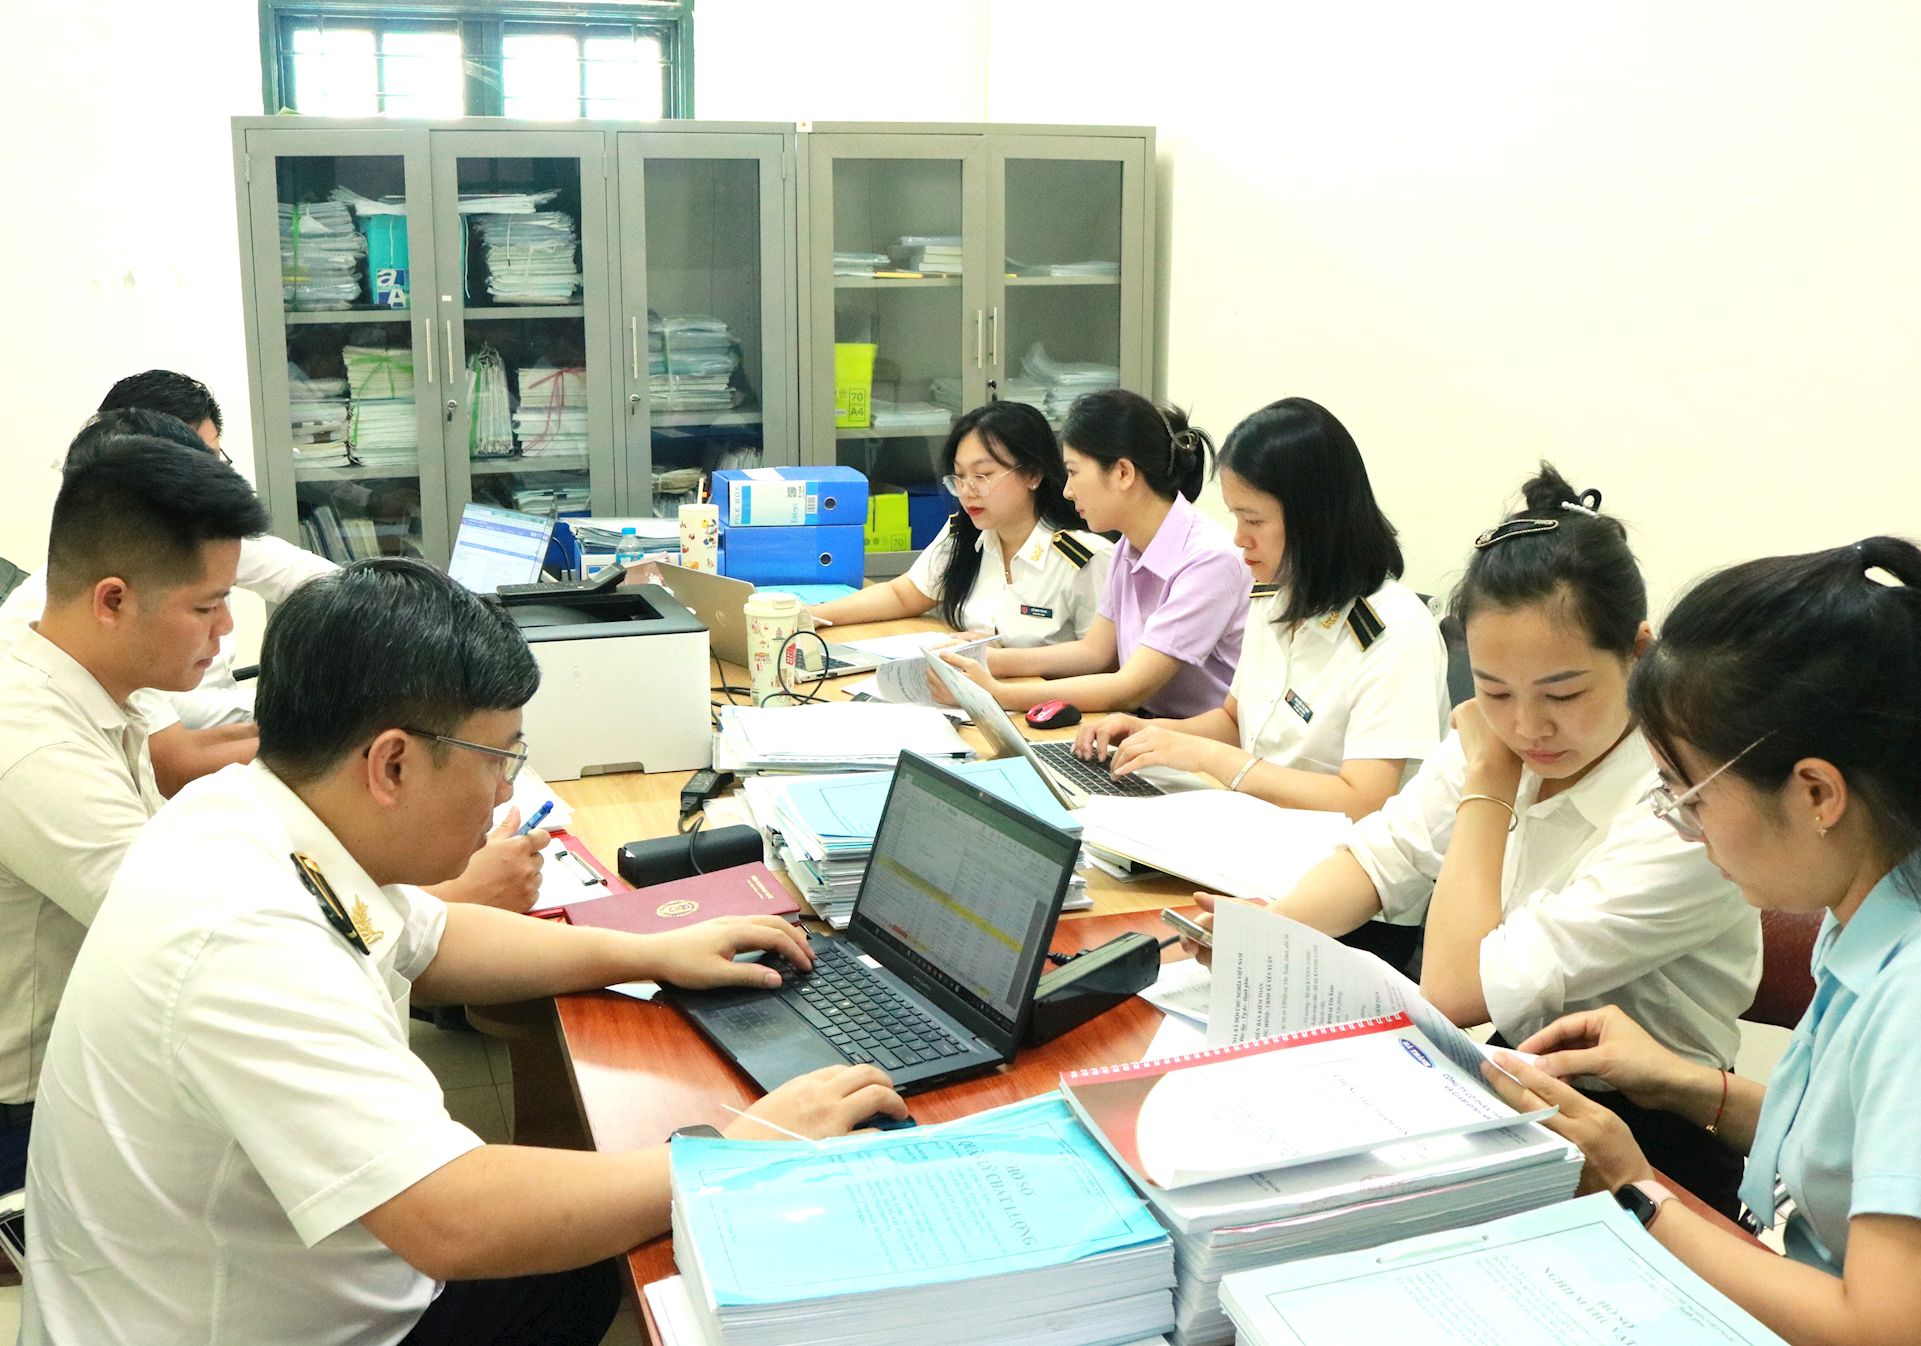
The SAV is taking proactive and decisive action to urge the implementation of audit recommendations. Photo: N. Ly
Outstanding Audit Recommendations Remain Unresolved for Extended Periods
According to the SAV's report, as of July 31, 2026, for recommendations relating to the 2024 budget year denominated in Vietnamese dong, the total amount of financial adjustments and other recommendations implemented reached VND 29,942.1 billion, equivalent to 72.96% of the total recommendations. This represented a remarkable increase of 52.06 percentage points compared with the same period in 2025, when the implementation rate as of July 31, 2025, stood at only 20.9%. For recommendations denominated in foreign currencies, the total value implemented reached USD 111.58 million, equivalent to 86.33% of the total recommendations.
Positive results were also recorded in recovering and resolving outstanding financial amounts from the 2023 budget year and earlier. During the first seven months of 2026, an additional VND 4,360.84 billion was implemented, bringing the cumulative amount implemented to date to VND 526,414.28 billion, equivalent to 90.94% of the total adjusted recommendations.
However, despite these achievements, the SAV's report shows that, as of July 31, 2026, recommendations relating to the 2024 budget year remained outstanding across the sector, with VND 11,097.17 billion (27.04%) and USD 17.66 million (approximately 14%) yet to be implemented.
For budget years 2023 and earlier, long-standing outstanding amounts totaled VND 52,424.66 billion. Of this amount, VND 30,052.82 billion, accounting for 57.33%, was directly attributable to audited entities facing financial difficulties, ceasing operations, undergoing dissolution or bankruptcy, lacking supporting documentation for settlement and finalization, or deliberately delaying implementation.
According to SAV Region I, which is responsible for Hanoi and Son La, as of September 20, 2026, the unit had achieved an implementation rate of 89.2% for recommendations relating to the 2025 budget year, with financial adjustments alone reaching 97.3%. Nevertheless, the cumulative outstanding recommendations that had yet to be implemented by the localities remained substantial, totaling VND 7,798 billion. Specifically, financial adjustment recommendations amounted to VND 4,594 billion, while other recommendations totaled VND 3,204 billion. Most of the outstanding amounts were concentrated in Hanoi, at VND 7,416 billion, followed by Son La Province at VND 334 billion and corporations operating in Hanoi at VND 48 billion.
SAV Region I identified three main groups of reasons why audit recommendations have remained difficult to resolve for many years.
First, the entities responsible for implementing recommendations are third parties outside the state budget system and therefore fall beyond the direct management authority of local governments. Examples include VND 903 billion in outstanding recommendations from a thematic audit of land management and use during and after the equitization of state-owned enterprises in the 2011–2017 period, as well as VND 539 billion outstanding from the investor of the Duong Noi New Urban Area Project.
Second, many recommendations concern district- and county-level entities that have since ceased operations, been dissolved, or been consolidated following the transition to the two-tier local government model. This has resulted in missing handover documents and difficulties in identifying the entities that have inherited the relevant obligations.
Third, certain recommendations require local authorities to review and reassess provisional amounts. Their implementation depends entirely on the progress of approving final accounts for completed projects or determining specific land prices by local authorities.
Audit experience at SAV Region XII, which is responsible for Dong Nai and Lam Dong provinces, also indicates that the transition to the two-tier local government model has directly affected the implementation of audit recommendations, particularly during the initial phase. Some departments, sectoral agencies, and district-level units have ceased operations, been consolidated, or had their functions changed. Meanwhile, the officials in charge have been reassigned, while relevant records and implementation obligations must be transferred to successor agencies. Without promptly identifying the responsible focal points, there is a significant risk of delays, buck-passing, and disruptions to the implementation process.
Stronger Measures to Resolve Outstanding Audit Recommendations
To end the prolonged failure to implement audit recommendations and prevent responsibility from being evaded following organizational restructuring, the SAV issued Circular No. 01/2026/TT-KTNN, providing detailed procedures for monitoring, urging, and inspecting the implementation of audit conclusions and recommendations. The circular clearly establishes coordination mechanisms and identifies the entities responsible following mergers, divisions, and consolidations. It also introduces stricter monitoring and accountability from the issuance of audit reports through to the complete resolution of outstanding recommendations.
One measure that the SAV's leadership has directed to be implemented immediately in 2026 is the public disclosure of organizations, units, and individuals that are slow to implement or deliberately delay audit recommendations. The lists will be published on the SAV's official website and through mass media. In addition, implementation results will be publicly reported to the 16th National Assembly at its Second Session.
In cases involving deliberate violations that cause serious consequences or show signs of criminal offenses, the SAV will apply appropriate measures in accordance with the law to protect the public interest and state assets.
For cases involving deliberate violations, serious consequences, or suspected criminal offenses, the SAV will impose administrative penalties under the Ordinance on Administrative Sanctions in the Field of State Auditing, refer the cases to investigative authorities for consideration of criminal proceedings, or notify the People's Procuracy at the same level to initiate civil litigation in order to protect the public interest and state assets.
According to SAV Region I, the quality of audit recommendations must be improved from the audit stage itself, following the principle of “four clear elements”: clearly identifying the responsible entity, the required action, the legal basis, and the feasibility of implementation. Every audit finding must specify the responsibilities of relevant organizations and individuals, as well as the particular entities required to take action. In addition, the SAV should standardize implementation deadlines across the sector, requiring recommendations to be fulfilled within three to six months of the issuance of the audit report.
Once the prescribed deadline has expired, recommendations requiring the recovery and remittance to the state budget of amounts spent in violation of regulations, if still unimplemented, will be referred to investigative authorities. Direct dialogue will also be strengthened, with workshops organized to address local authorities' concerns and obstacles.
For audit recommendations that can no longer be implemented due to objective legal or practical impossibilities, or difficulties arising from the transition to the two-tier local government model in which former agencies ceased to exist without properly transferring responsibilities to successor entities, the SAV has provided comments on the Ministry of Finance's draft submission to the Government concerning the development of a general mechanism for resolving inspection conclusions and audit recommendations that are no longer feasible to implement.
According to Mai Van Tan, Deputy Chief Auditor of SAV Region XII, a consistent mechanism is needed to address outstanding recommendations involving enterprises that have been dissolved, declared bankrupt, ceased operations, or no longer possess assets available for enforcement. The mechanism should clearly stipulate the criteria for determining cases in which implementation is genuinely impossible, the required supporting documents, verification procedures, decision-making authority, and the responsibilities of relevant organizations and individuals. Recommendations should only be removed from monitoring lists after all recovery measures have been exhausted, the objective causes have been accurately established, and any attempts to evade responsibility or legitimize violations have been ruled out.
Strengthening administrative discipline, imposing appropriate sanctions for deliberate violations, and removing institutional barriers in objective and unavoidable cases will establish a rigorous and substantive enforcement mechanism. This is essential to ensuring that audit recommendations are fully implemented, addressing fundamental weaknesses in management, preventing losses and waste, and ultimately enhancing the effectiveness and efficiency of public financial and public asset management.