CPA VIETNAM AUDITING COMPANY LIMITED
Qualified services, global understanding and vision

Hướng dẫn tiêu chí kiểm toán đánh giá hiệu quả dự án đầu tư công trong lĩnh vực giao thông

31/07/2026 - 08:53      106 view
Kiểm toán nhà nước (KTNN) vừa ban hành Hướng dẫn tiêu chí kiểm toán đánh giá hiệu quả dự án đầu tư công trong lĩnh vực giao thông (Hướng dẫn), nhằm nâng cao chất lượng, hiệu quả hoạt động kiểm toán và bảo đảm thống nhất trong việc đánh giá hiệu quả đầu tư công trong lĩnh vực giao thông.
Nội dung chính[ẩn][hiện]

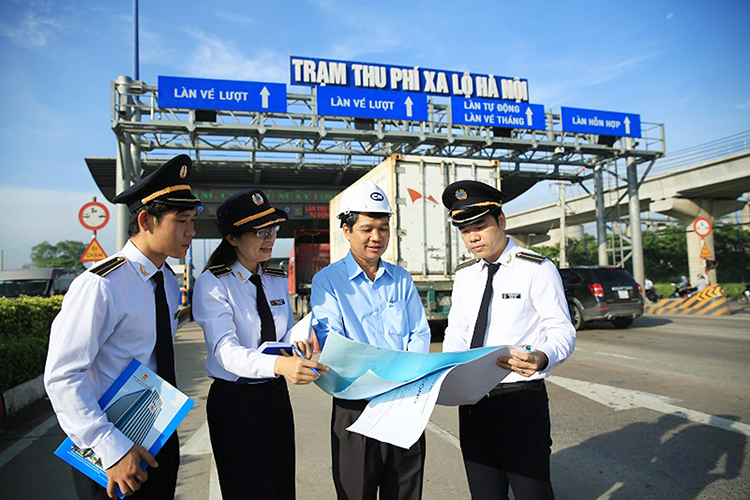
KTNN ban hành Hướng dẫn tiêu chí kiểm toán đánh giá hiệu quả dự án đầu tư công trong lĩnh vực giao thông. Ảnh minh họa: T.L

Hướng dẫn quy định các nguyên tắc, nội dung, tiêu chí và phương pháp đánh giá hiệu quả dự án đầu tư công trong lĩnh vực giao thông phục vụ hoạt động kiểm toán của KTNN.

Hướng dẫn được sử dụng để đánh giá hiệu quả các dự án đầu tư công sau khi hoàn thành hoặc đã đưa vào khai thác, vận hành; làm cơ sở để xem xét mức độ đạt được mục tiêu đầu tư, hiệu quả sử dụng nguồn lực, hiệu quả khai thác, vận hành và tác động kinh tế - xã hội của dự án.

Hướng dẫn áp dụng đối với các dự án đầu tư công thuộc lĩnh vực giao thông, bao gồm: dự án đường bộ, dự án đường sắt, dự án cảng hàng không, dự án cảng biển, dự án đường thủy nội địa, dự án giao thông đô thị.

Đối với các dự án có tính chất đặc thù hoặc dự án áp dụng hình thức đầu tư khác có sử dụng vốn nhà nước, việc vận dụng Hướng dẫn này được thực hiện phù hợp với mục tiêu, quy mô, tính chất và đặc điểm của từng dự án.

Hướng dẫn này là căn cứ để đoàn kiểm toán xây dựng tiêu chí kiểm toán, xác định nội dung kiểm toán, thu thập bằng chứng kiểm toán và đánh giá tính kinh tế, tính hiệu quả, tính hiệu lực, tính bền vững của dự án đầu tư công theo quy định của Luật KTNN và Chuẩn mực KTNN.

Theo Hướng dẫn, việc đánh giá hiệu quả dự án đầu tư công nhằm đánh giá tính kinh tế, tính hiệu quả, tính hiệu lực và tính bền vững trong quá trình đầu tư, quản lý, khai thác và vận hành dự án; đánh giá mức độ phát huy công năng, công suất thiết kế và hiệu quả sử dụng nguồn lực đầu tư công; đánh giá tác động kinh tế, xã hội, môi trường và đóng góp của dự án đối với phát triển ngành, lĩnh vực, địa phương và quốc gia.

Bên cạnh đó, việc đánh giá hiệu quả dự án đầu tư công cũng nhằm phát hiện những hạn chế, bất cập, nguy cơ thất thoát, lãng phí trong quá trình đầu tư, quản lý, khai thác và vận hành dự án; xác định nguyên nhân và trách nhiệm của các tổ chức, cá nhân có liên quan. Đồng thời làm cơ sở để kiến nghị hoàn thiện cơ chế, chính sách, nâng cao hiệu quả quản lý và sử dụng vốn đầu tư công.

Về nguyên tắc đánh giá hiệu quả dự án đầu tư công, Hướng dẫn chỉ rõ việc đánh giá hiệu quả dự án được xác định tại thời điểm thực hiện kiểm toán; bảo đảm khách quan, trung thực, đầy đủ, kịp thời và có thể kiểm chứng được.

Bên cạnh đó, việc đánh giá phải căn cứ vào mục tiêu đầu tư, quy mô đầu tư, công năng sử dụng, điều kiện khai thác thực tế, chi phí vận hành theo thời hạn sử dụng của công trình/dự án và các chỉ tiêu đã được cơ quan có thẩm quyền phê duyệt. Kết quả đánh giá phải được xem xét trên cơ sở so sánh giữa mục tiêu, chỉ tiêu dự kiến với kết quả thực tế đạt được sau đầu tư.

Đồng thời, việc đánh giá phải kết hợp giữa các chỉ tiêu định lượng và định tính; giữa đánh giá hiệu quả tài chính, hiệu quả kinh tế - xã hội, hiệu quả môi trường và hiệu quả trong công tác quản lý, tổ chức thực hiện, khai thác và vận hành dự án.

Theo Hướng dẫn, việc đánh giá hiệu quả dự án đầu tư công được thực hiện trên cơ sở 4 nhóm tiêu chí, gồm: tính kinh tế, tính hiệu quả, tính hiệu lực, tính bền vững và phòng, chống lãng phí.

Các nhóm tiêu chí đánh giá trên được sử dụng để xác định nội dung kiểm toán; thu thập và đánh giá bằng chứng kiểm toán; đánh giá mức độ đạt được mục tiêu đầu tư; xác định các tồn tại, hạn chế, hậu quả và nguyên nhân ảnh hưởng đến hiệu quả dự án.

16/11/2026 8
Despite spending 99.6% of its allocated budget for the 2025–2026 financial year, South Africa's Department of Sport, Arts and Culture (DSAC) has yet to address longstanding weaknesses in governance and financial controls. The Auditor-General of South Africa (AGSA) has warned that numerous gaps in the internal control system are increasing the risk of fraud, undermining budget efficiency and accountability.
View details
16/11/2026 6
On the afternoon of November 13, as part of his official visit and working trip to the Republic of Belarus, State Auditor General of Vietnam Nguyen Huu Nghia and his delegation held a bilateral meeting with Deputy Prime Minister of Belarus Aleksandr Terekhov, Head of the Belarusian delegation to the Vietnam–Belarus Intergovernmental Commission on Trade, Economic, Scientific and Technical Cooperation.
View details
13/11/2026 16
On November 12, in Minsk, the capital of Belarus, as part of an official working visit to the Republic of Belarus, a high-level delegation from the State Audit Office of Vietnam (SAV), led by Auditor General Nguyen Huu Nghia, held a bilateral meeting with the State Control Committee of the Republic of Belarus, headed by its Chairman, Vasily Gerasimov.
View details
13/11/2026 22
The rapid adoption of artificial intelligence (AI) across organizations is outpacing existing governance and control capabilities. The accelerated development of generative AI, AI agents, and the unauthorized use of AI tools (“shadow AI”) poses significant challenges related to transparency, data security, and accountability. In response to these emerging risks, internal audit functions must innovate their methodologies, enhance professional competencies, and strengthen oversight to ensure that AI applications are managed safely and effectively.
View details
12/11/2026 21
Disbursed investment capital from the state budget in the first 10 months of 2026 was estimated at VND 783.9 trillion, equivalent to 69% of the annual plan and up 19.8% year-on-year. Total registered foreign investment reached USD 54.85 billion, an increase of 74%, while disbursed foreign direct investment (FDI) amounted to USD 24.08 billion, up 13.1%. Increasing capital inflows are providing additional momentum for the economy. However, the key issue is not merely how much capital can be mobilized and disbursed, but more importantly, how much value, productive capacity, and competitiveness each unit of investment capital can generate.
View details
12/11/2026 20
The restructuring and streamlining of the political system's organizational apparatus, together with the implementation of the two-tier local government model, have resulted in adjustments to the functions, responsibilities, audited entities, and designated focal points of various agencies and organizations. Consequently, although many audits have been completed and recommendations issued, some recommendations may not yet have been fully implemented. It is therefore essential to ensure their timely and comprehensive handover and receipt to maintain continuity in monitoring, follow up on all outstanding recommendations, and prevent any omissions. The implementation of audit recommendations is a decisive factor in determining the effectiveness and efficiency of audit activities and serves as a basis for the State Audit Office of Vietnam (SAV) to demonstrate its performance and accountability to the National Assembly and the public.
View details
11/11/2026 30
The State Audit Office of Vietnam (SAV) is expected to strengthen data-driven auditing, remote auditing, thematic auditing and performance auditing in the coming years, with a particular focus on auditing public resources, development programs, nationally important projects and macroeconomic policies of the Party and the State, thereby serving the common interests of the country and its people.
View details
11/11/2026 21
Data should not only be regarded as a source of information for individual audits but also as a digital asset of the State Audit Office of Vietnam (SAV), requiring centralized management, consistent utilization and long-term reuse to support auditing activities, management, administration and strategic planning.
View details
10/11/2026 17
The Standing Committee of the Party Committee of the State Audit Office of Vietnam (SAV) has recently issued Official Letter No. 1614-CV/DU on communication activities commemorating the 80th anniversary of the First National Cultural Conference (November 24, 1946 – November 24, 2026), Vietnam Culture Day (November 24), and the Great National Unity Festival (November 18).
View details
10/11/2026 18
The State Audit Office of Vietnam (SAV) has recently published the results of a thematic audit on the management and use of public investment capital in Khanh Hoa Province during the 2021–2025 period. The audit revealed that 53 projects had to be suspended after their investment policies were approved; one project had achieved a disbursement rate of only 18.76% as of the audit date; and another project, scheduled for completion and handover in 2026, had only begun its investment preparation procedures by July 2026, when the audit was conducted.
View details
09/11/2026 38
On the morning of October 8, the Vietnam Association of Accountants and Auditors (VAA), in coordination with the Lao Cai Provincial Department of Finance, held the opening ceremony of a professional training conference on financial management for commune-level officials, civil servants, and public employees across the province at the Department of Finance's headquarters.
View details
09/11/2026 29
In its latest enforcement action, the State Securities Commission of Vietnam (SSC) has named several enterprises for violations involving periodic disclosure obligations, inaccurate information disclosure, securities issuance regulations, corporate governance reporting, and accounting personnel information.
View details
Head Office
Representative Office
Northern Branch
Ho Chi Minh City Branch
Key thời gian làm việc
Copyright © 2026 CPA VIETNAM AUDIT. All rights reserved. Website designed by Tat Thanh
Access statistics
Total visits: 487958 Currently visiting: 325
Website Policy