The Global Fund to Fight AIDS, Tuberculosis and Malaria has proposed that the State Audit Office of Vietnam (SAV) audit the Global Fund's grants in Vietnam for the 2027–2029 period.
On the morning of October 2, at the SAV headquarters, representatives of the Department of International Cooperation and SAV Specialized Audit Department III held a working meeting with representatives of the Global Fund to Fight AIDS, Tuberculosis and Malaria.
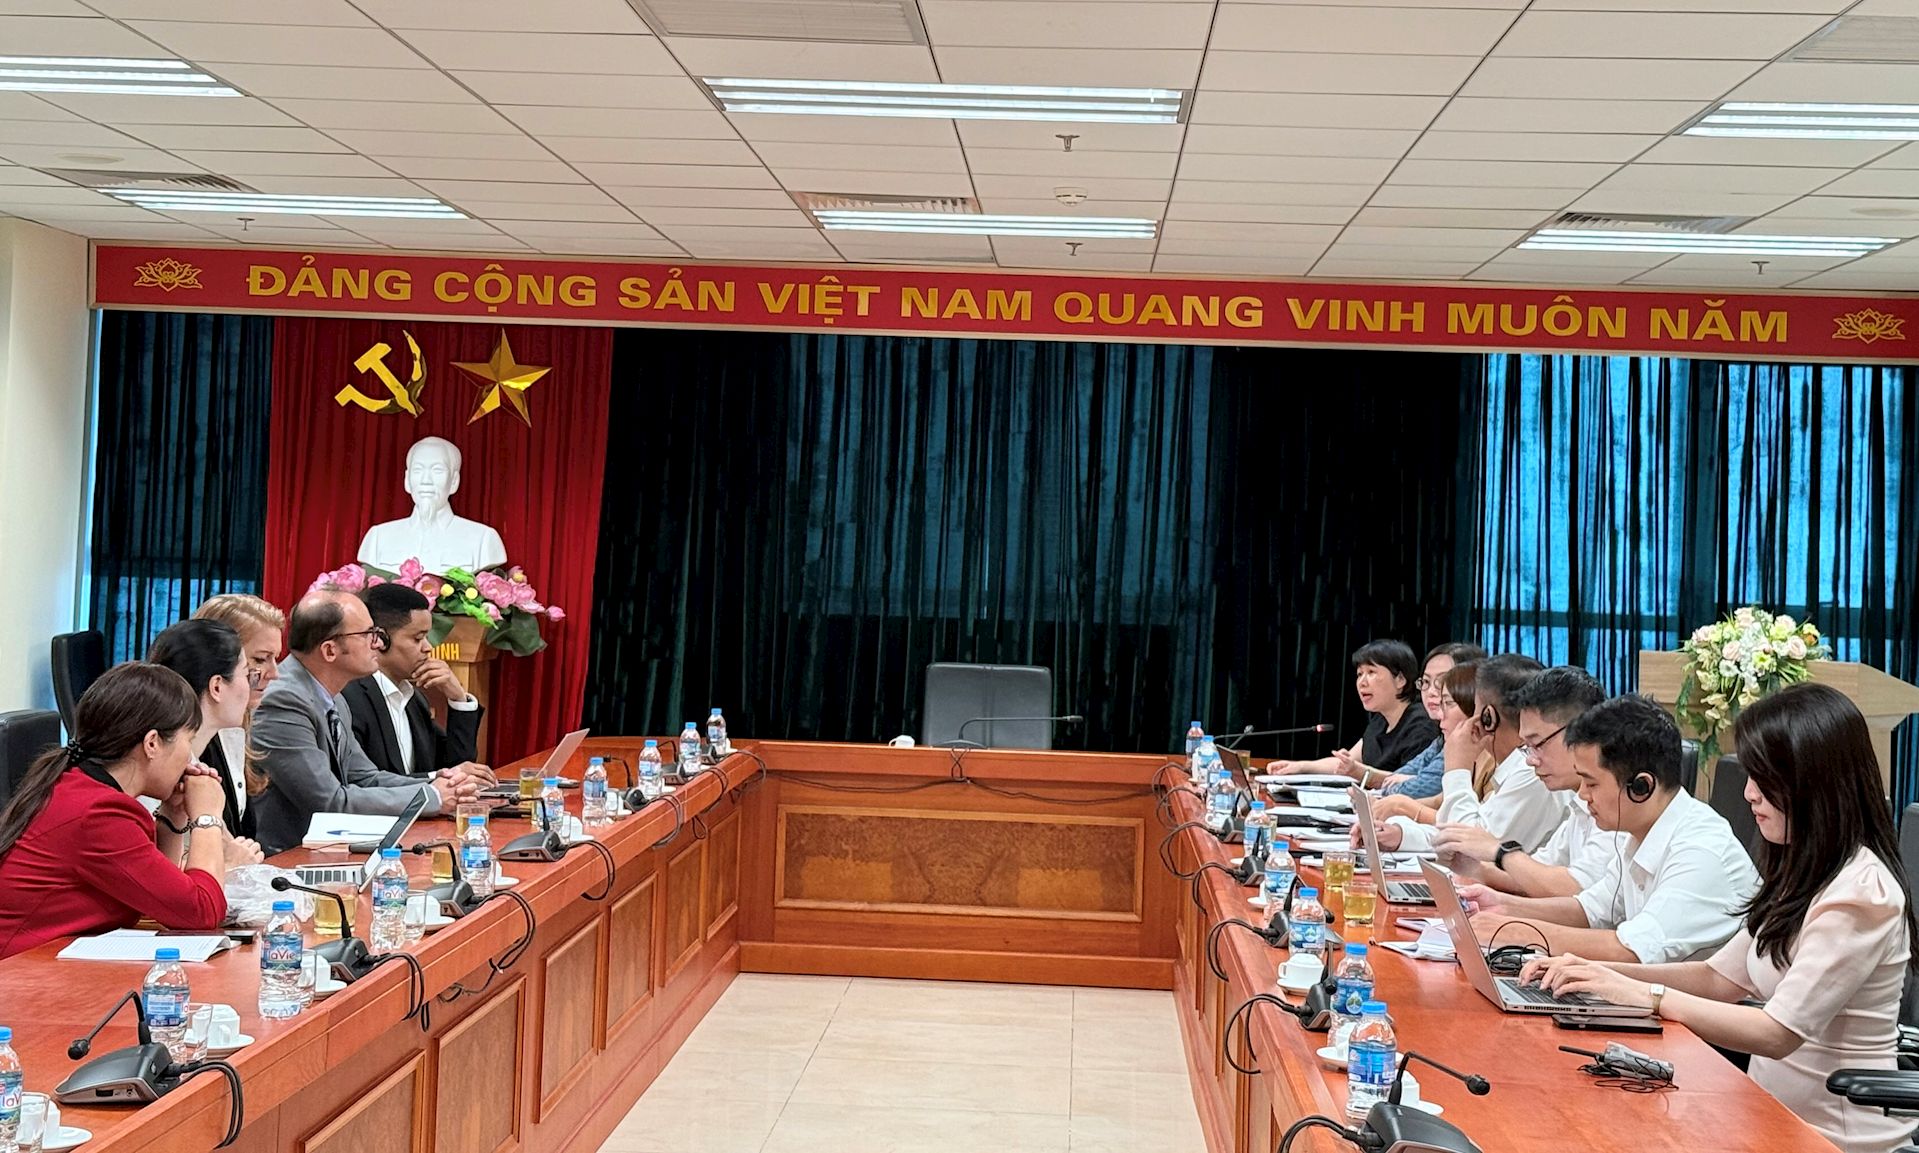
Overview of the meeting. Photo: QUYNH ANH
Representing the SAV were Ms. Lang Trinh Mai Huong, Deputy Director General of the Department of International Cooperation; Ms. Hoang Thi Vinh Thuy, Deputy Chief Auditor of SAV Specialized Audit Department III; and representatives of several relevant units.
Representing the Global Fund to Fight AIDS, Tuberculosis and Malaria were Mr. Stefan Stojanovikj, Senior Fund Manager; Ms. Gloria Pesarin, Senior Program Officer of the Grant Management Division; and Mr. Prosper Roman Moshi, Grant Finance Management Specialist.
Ms. Lang Trinh Mai Huong stated that, following the direction of the State Auditor General regarding an official letter from Vietnam's Country Coordinating Mechanism (CCM Vietnam) requesting a meeting with the Global Fund, the Department of International Cooperation, SAV Specialized Audit Department III, and the Department of General Affairs had been assigned to conduct a technical-level meeting with CCM Vietnam. The purpose was to hold preliminary discussions on the possibility of cooperation in auditing the Global Fund's grants in Vietnam for the 2027–2029 period.
Representatives of the SAV attend the meeting.
At the meeting, Mr. Stefan Stojanovikj, Senior Fund Manager, stated that once the initial grant recipients had been identified, the Global Fund wished to ensure that the recipients managed and used the funds effectively and that the SAV audited their use, particularly expenditures related to procurement and bidding activities under the projects.
Through CCM Vietnam, the Global Fund to Fight AIDS, Tuberculosis and Malaria supported four projects during the 2024–2026 period, with CCM Vietnam coordinating the respective implementation phases. These included the Global Fund Technical Assistance Project for HIV/AIDS Prevention and Control, whose grant recipient was the Department of Disease Prevention (formerly the Vietnam Administration for HIV/AIDS Control before its merger); the project implemented by the Vietnam Union of Science and Technology Associations (VUSTA), which also served as the grant recipient; the Global Fund Tuberculosis Prevention and Control Project for 2024–2026, whose grant recipient was the National Lung Hospital; and the Regional Artemisinin-resistance Initiative (RAI) for malaria control and elimination for 2024–2026, whose grant recipient was the National Institute of Malariology, Parasitology and Entomology.
For the 2027–2029 period, the Global Fund will support three projects: the HIV/AIDS prevention and control project, with the Department of Disease Prevention as the grant recipient; the tuberculosis prevention and control project, with the National Lung Hospital as the grant recipient; and the Regional Artemisinin-resistance Initiative (RAI) for malaria elimination, with the National Institute of Malariology, Parasitology and Entomology as the grant recipient.
According to Mr. Stefan Stojanovikj, the total funding allocated to the three projects amounts to USD 60 million, to be disbursed over the next three years.
Representatives of the Global Fund attend the meeting. Photo: QUYNH ANH
Mr. Prosper Roman Moshi, Grant Finance Management Specialist, stated that the Global Fund would establish audit standards covering relevant issues and areas, together with specific guidance tailored to the SAV's requirements. He also expressed the Fund's desire for the SAV to conduct annual audits of these grants.
During the discussion, Ms. Hoang Thi Vinh Thuy stated that, based on its preliminary review, the SAV considered the proposal to use Vietnam's Supreme Audit Institution to audit the Global Fund's grants consistent with the Fund's policy of strengthening the use of national public financial management systems.
For the 2024–2026 period, there is a legal basis for considering grant funding received, managed and used by the Ministry of Health and its subordinate units as falling within the SAV's audit mandate, in accordance with Article 4 of the State Audit Law, which defines the audit scope as the management and use of public finance and public assets, as well as related activities of audited entities, and Article 55, which identifies ministries, state agencies, bodies assigned to collect or spend the state budget, and their subordinate units as entities subject to audit.
However, the SAV cannot replace independent auditors in auditing the entire grant portfolio, as some recipients are outside the public sector and certain payments are made directly by the Global Fund.
Similarly, for the 2027–2029 period, audits of Global Fund grants received by the three recipient entities under the Ministry of Health fall within the scope of entities eligible for audit under the State Audit Law. Nevertheless, the extent to which the SAV can audit the Fund's non-refundable grants must be determined based on Vietnamese law and the specific project documentation. Several important aspects remain to be clarified, including the grant recipients, fund receipt mechanisms and cash flows, accounting and final settlement arrangements, the scope of financial reporting, the terms of reference, and the expected audit deliverables of the SAV.
Accordingly, the SAV requested that the Global Fund, CCM Vietnam and the Ministry of Health provide the relevant documentation and jointly assess whether the proposed arrangements meet the Fund's audit requirements while remaining within the SAV's statutory authority under Vietnamese law. Based on this assessment, the SAV will consider whether to include the task in its audit plan and determine an appropriate coordination mechanism.
Representatives of the Global Fund thanked the SAV for receiving the delegation and reiterated their desire for the SAV to participate in auditing the grants. They also expressed their interest in strengthening cooperation with the SAV in the coming period.
In conclusion, Ms. Lang Trinh Mai Huong requested that the Global Fund provide the list of documents required by the SAV. Based on the submitted documentation, the relevant SAV units will conduct further reviews and report to the State Auditor General for consideration and a decision on whether to include this matter in the audit plans for the coming years.