More than 65,000 cases involving entities no longer operating at their registered addresses have been notified of exit suspension, with total tax arrears exceeding VND 6.9 trillion. Behind this enforcement measure lies the challenge of distinguishing between enterprises deliberately evading their obligations and legal entities that have effectively become “clinically dead”…
What Are the Boundaries of Exit Suspension Measures?
As part of efforts to clean up taxpayer data, tax authorities are reviewing and handling tens of thousands of enterprises that are no longer operating at their registered addresses.
For these cases, the issue goes beyond determining the enterprise’s tax obligations and may directly affect the individual legal representative through the application of exit suspension measures. The new regulations on exit suspension are designed to clearly identify the applicable subjects, debt thresholds, and time limits for taxpayers to remedy their violations before the measure is imposed.
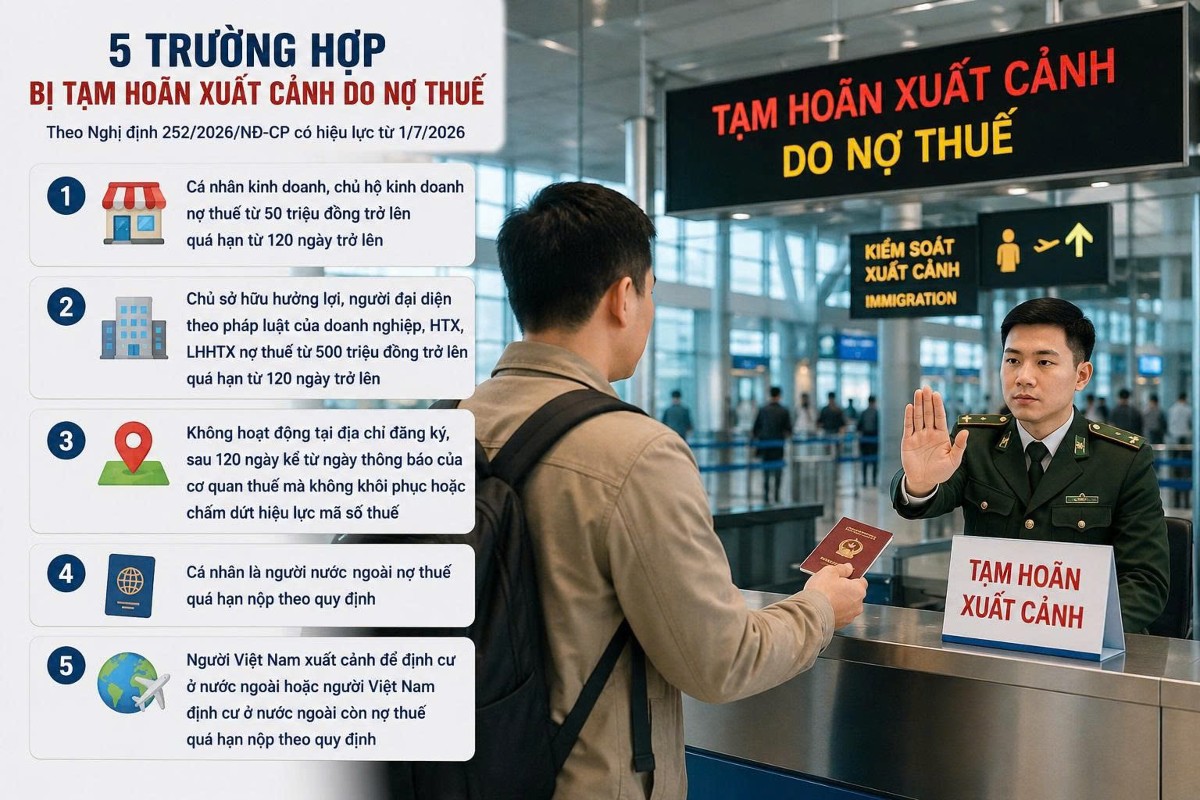
Under Decree No. 252/2026/NĐ-CP, which took effect on July 1, 2026, business individuals and household business owners subject to enforcement measures with tax arrears of VND 50 million or more that are overdue for at least 120 days may be subject to exit suspension. For individuals who are beneficial owners or legal representatives of enterprises, cooperatives, or cooperative unions, the threshold is VND 500 million or more, with the debt overdue for at least 120 days.
Notably, for taxpayers determined by tax authorities to no longer be operating at their registered addresses, exit suspension is not merely a matter of whether the tax debt is large or small. It is also linked to whether the taxpayer proactively addresses the status of their tax identification number after being notified by the tax authority.
If, after 120 days from the date the tax authority issues a notice regarding the taxpayer’s non-operation at the registered address, the taxpayer still fails to carry out procedures to restore the tax identification number or terminate the validity of the tax identification number, the legal representative, beneficial owner, and certain related individuals may be subject to exit suspension.
Source: Tax Department
The Same Status Does Not Mean the Same Level of Risk
According to data from the Tax Department, approximately 105,000 legal representatives of enterprises and household business owners have been notified of exit suspension, involving total tax arrears of nearly VND 61 trillion.
Of these, more than 65,000 cases involve entities that are no longer operating at their registered addresses but failed to notify the tax authorities, with tax arrears exceeding VND 6.9 trillion. These figures indicate that enterprises no longer operating at their registered addresses account for a significant proportion of cases subject to exit suspension measures.
From the perspective of the tax authorities, this represents a considerable information gap. When an enterprise is no longer located at its registered address, it becomes difficult for the tax authority to determine whether the enterprise is still actually operating, whether it has assets or cash flows, or whether it has any outstanding obligations. If the legal representative also fails to proactively contact the authorities, the legal entity may remain on the system in a status that does not clearly reflect its actual circumstances.
In this context, exit suspension becomes a tool for creating pressure to bring legal representatives back to work with the tax authorities. Initial results in the recovery of outstanding obligations are also reflected in tax sector data.
Cumulatively, tax authorities have collected more than VND 4 trillion in tax arrears from over 13,000 taxpayers. Among entities no longer operating at their registered addresses, approximately 7,100 cases have proactively contacted the tax authorities, paid nearly VND 100 billion, and had their exit suspension measures lifted.
(Tax Department)
Thus, the effectiveness of this measure cannot be denied. When an enterprise disappears from its registered address and its legal representative fails to proactively address the matter, creating sufficient pressure may help tax authorities bring the taxpayer back into the system.
However, the effectiveness of this tool also raises questions about the boundaries of enforcement. No longer operating at the registered address is an important administrative indicator, but it does not mean that all enterprises in this status present the same level of risk.
Experts note that not every enterprise that is no longer operating at its registered address is a “shell company.”
In practice, an enterprise’s failure to operate at its registered address may result from various circumstances. Some enterprises may have changed their business locations without updating their information; some may have genuinely ceased operations but have not completed dissolution procedures; while others may deliberately abandon their registered addresses to evade their obligations.
According to reports from various enterprises on tax and accounting forums, there are cases in which legal representatives submitted dissolution applications to tax authorities three to five years ago but have still not completed the process. Without confirmation from the tax authority, the dissolution procedures with the business registration authority cannot be finalized either.
As a result, an enterprise may have genuinely exited the market while remaining “stuck” in the system for years. When the data are reviewed, the enterprise may be identified as no longer operating at its registered address, while its legal representative is still struggling to resolve outstanding obligations in order to close the tax identification number.
Enforcement Measures Need to Be Accompanied by Effective Classification
This is also an important consideration when applying enforcement measures to entities that are no longer operating at their registered addresses, because although these cases share the same status in the system, their underlying circumstances may be very different.
The same “no longer operating at the registered address” status may apply to an enterprise deliberately evading its obligations, concealing its activities or assets, as well as to an enterprise that has ceased operations, has no significant cash flows or assets, but has yet to complete the legal procedures required to formally conclude its existence.
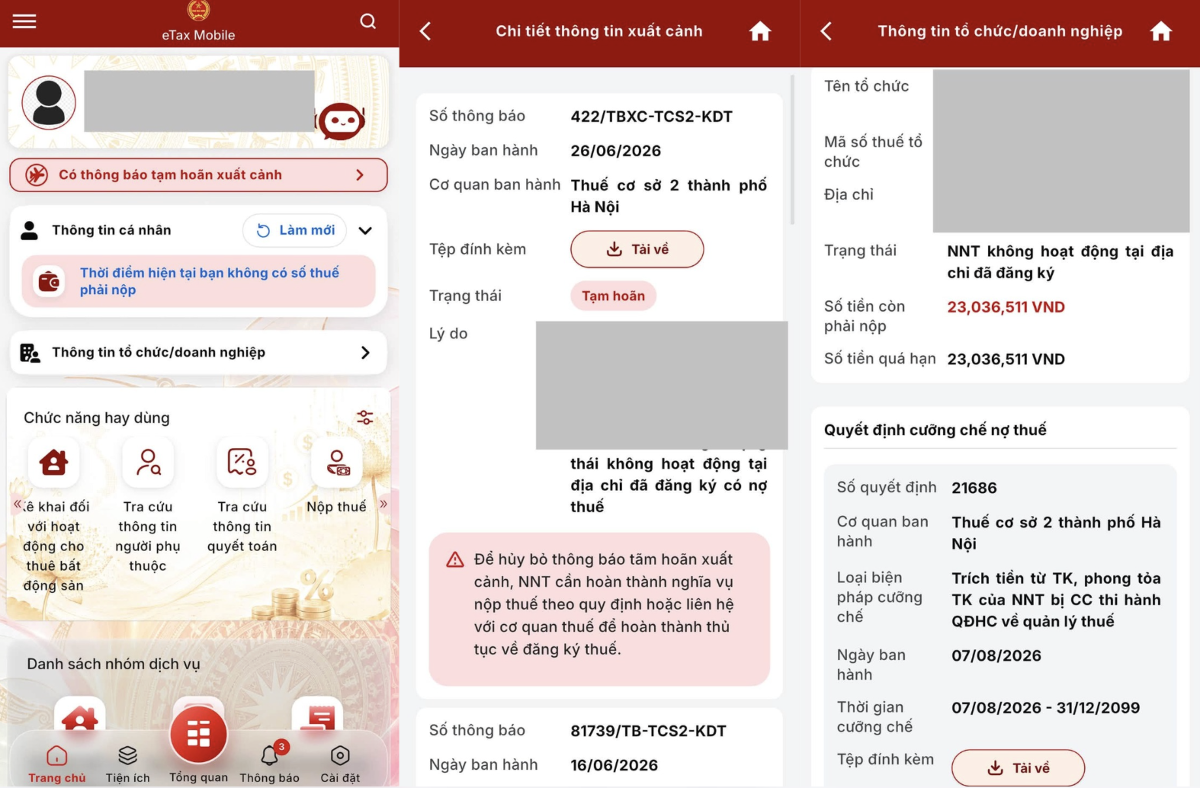
Photo: Provided by the source
For an enterprise that remains operational and has revenue, cash flows, or assets but deliberately fails to fulfill its tax obligations, imposing strong measures against the legal representative has a clear basis. In such cases, both the risk of revenue loss to the state budget and the risk of the responsible individual evading their obligations are present.
Conversely, for an enterprise that has ceased operations for a long period and no longer has cash flows, the question may be different. Does the pressure created by an exit suspension measure actually increase the likelihood of recovering outstanding obligations, or does it primarily place additional pressure on the individual to complete the process of dealing with a legal entity that ceased operations long ago?
The substance of the issue therefore does not lie in whether exit suspension should be used, but rather in how the measure is applied so that it is proportionate to the level of risk and the ability of each taxpayer to fulfill their obligations.
If the purpose of exit suspension is to create pressure for individuals capable of fulfilling their obligations to do so, then determining that capacity becomes a critical step. An enterprise that is still operating but deliberately conceals revenue or assets or evades its obligations should not be treated in the same manner as an enterprise that ceased doing business years ago and is seeking to complete its dissolution procedures.
Therefore, before applying strong measures against an individual, reviewing the enterprise’s actual status is crucial. Tax authorities need to cross-check tax obligations, information on the legal representative and beneficial owner, the status of the tax identification number, filing history, invoices, and outstanding tax amounts in order to correctly identify the applicable person and determine whether the relevant conditions are satisfied.
In particular, for enterprises that have ceased operations for a long period, if the obstacle lies in the enterprise’s deliberate failure to fulfill its obligations, enforcement measures may create the necessary pressure. However, if the enterprise has proactively initiated the procedures and is merely encountering difficulties in the processing of its application, the focus should instead be on removing the bottleneck so that the enterprise can complete the procedures.