According to experts, enterprises that have encountered difficulties, have no remaining revenue or cash flow, but have yet to complete dissolution procedures may continue to face additional obligations and costs. The issue is not merely about fully collecting outstanding amounts, but also about making proper classifications so that enterprises that are “dead but not yet laid to rest” can exit the market in an appropriate manner...
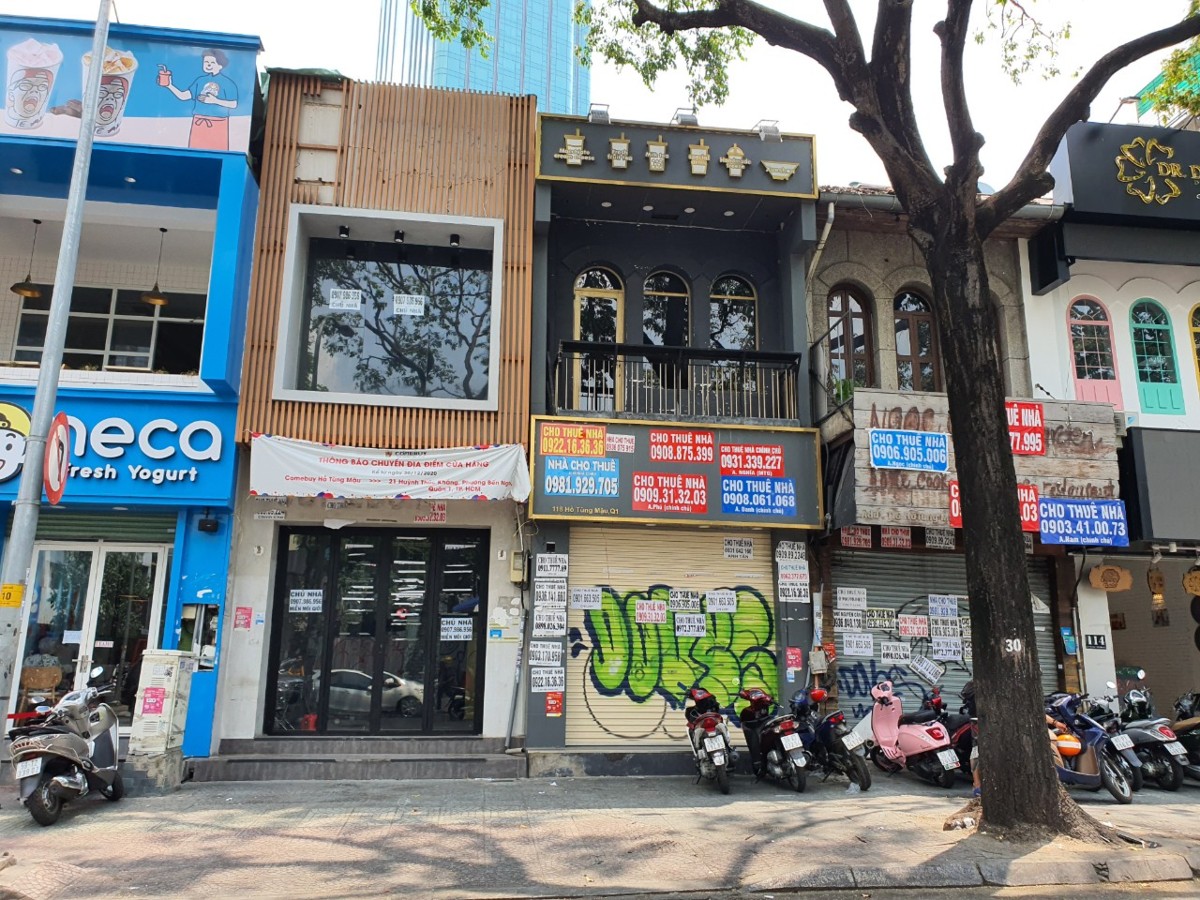
A way out is needed for enterprises that are “dead but not yet buried.” Photo: Thuy Hang
As VnEconomy has reported, a number of enterprises have ceased operations for a long period but have still been unable to complete dissolution procedures and terminate the validity of their tax identification numbers. As long as the legal entity has not been formally established as having ceased to exist, obligations associated with its operational status may continue to arise, while its legal representative may face additional pressure from tax administration measures.
Of course, business owners cannot deny their responsibility. When ceasing operations, an enterprise must carry out procedures for business suspension or dissolution and fulfill its obligations relating to tax, accounting, invoices, and business registration.
Unilaterally abandoning a business address without notifying the competent authorities and leaving the legal entity on the system constitutes an error on the part of the business owner and must be handled in accordance with regulations. However, the issue is that not all enterprises have the same underlying circumstances or level of risk.
“Fugitive” Enterprises and Stalled Enterprises Cannot Be Treated as One
Some enterprises deliberately engage in invoice trading, tax evasion, falsification of information, asset dissipation, or absconding to evade their obligations to the State. However, there are also small enterprises that have failed in business, have no remaining revenue or cash flow, and whose owners lack legal knowledge or sufficient financial capacity to handle procedures after closing down. Treating these two groups in the same manner would make it difficult to accurately reflect the nature of their respective violations.
According to Ms. Nguyen Thi Cuc, Chairwoman of the Vietnam Tax Consultants Association, the approach should be based on the nature and level of risk of each group of enterprises.
For cases that have genuinely ceased production and business activities, generate no revenue or expenses, use no invoices, and have no tax debts, but have not terminated the validity of their tax identification numbers due to a lack of knowledge or neglected procedures, consideration could be given to not collecting business license fees and late-payment interest, while also refraining from imposing penalties for late submission of tax declaration dossiers during periods when the enterprises were not actually operating. Instead, the focus should be on addressing the failure to notify the suspension of business activities and the failure to carry out procedures to terminate the validity of the tax identification number.
Meanwhile, cases showing signs of fraud, invoice trading, establishment of “shell companies,” use of false information, or abandonment of business addresses to evade taxes should be subject to strict control and handling. Properly classifying enterprises according to their actual circumstances will help management resources focus on cases that genuinely pose risks, rather than being spread across all dossiers, the Chairwoman of the Vietnam Tax Consultants Association said.
However, looking at the issue from another perspective, a major bottleneck is how to determine which enterprises have genuinely exited the market and which are deliberately keeping their legal entities “on hold” to evade obligations.
Mr. Le Van Tuan, Director of Keytas Accounting and Tax Co., Ltd.
“Most cases involve enterprises that are no longer doing business but whose owners gradually give up because the procedures are lengthy and complicated. There are also cases where enterprises previously contacted the competent authorities to carry out procedures but the process was not completed, after which the dossiers were left unresolved. Therefore, it is very difficult to specifically determine whether an enterprise failed to complete the procedures intentionally or due to objective reasons.”
According to Mr. Le Van Tuan, Director of Keytas Accounting and Tax Co., Ltd., simply classifying enterprises based on whether they “unintentionally” or “intentionally” let their businesses remain unresolved makes it difficult to accurately assess the situation. The business owner’s responsibility cannot be denied, but the reasons why an enterprise ceases operations do not necessarily originate from only one side.
In this context, a prolonged period without revenue, invoices, or transactions may serve as indicators that an enterprise has genuinely exited the market. If management data are sufficiently complete, tax authorities can rely on system data, including the date on which the enterprise was recorded as no longer operating, to determine its status and adopt an appropriate course of action.
This issue is significant not only for “cleaning up” tax identification number data. If an enterprise has actually exited the market but is still legally regarded as existing, obligations associated with that legal status may continue to arise. Business license fees are one of the issues that clearly illustrate this paradox.
According to Mr. Tuan, by nature, the business license fee is an administrative fee payable when the State provides public services to an entity commencing business activities.
However, current regulations only provide that enterprises carrying out business suspension procedures in accordance with regulations are exempt from business license fees during the suspension period. This means that if an enterprise has actually ceased operations but has not completed the required procedures, the fee may continue to be recorded in subsequent years.
Therefore, Mr. Tuan proposed that, where an enterprise has genuinely ceased business activities, the application of business license fees during that period should be reconsidered. Once an enterprise has ceased operations for many years, the fee should not continue to accrue, in order to avoid an accumulation that makes it more difficult for the enterprise to complete its dissolution procedures.
Fairness Is Not Merely About “Collecting in Full”
According to Mr. Tuan, this approach would not create unfairness or open another “loophole” for enterprises to evade their obligations. The key is to distinguish between obligations arising from actual business activities and those arising simply because an enterprise has not completed the procedures to exit the system.
Enterprises that remain operational must file tax returns, pay taxes, and fulfill their financial obligations in accordance with regulations. Enterprises that have completed dissolution procedures have a clearly established legal status and should no longer incur obligations associated with business activities after the date of termination.
The issue lies with enterprises caught between these two statuses: they have actually ceased operations but have not completed the procedures to formally exit the system. Because there is no legal decision confirming the date of termination, these enterprises remain at risk of continuing to incur filing obligations, fees, and administrative processing requirements.
If this vicious cycle continues, accumulating obligations and outstanding dossiers will increase the cost of dissolution, further reducing the likelihood that business owners will be able to complete the procedures. Meanwhile, the legal entity continues to exist and remains subject to administrative management.
The number of enterprises and household businesses requiring review also raises questions about how these cases should be handled. If hundreds of thousands of enterprises and household businesses are genuinely in this situation solely because their owners deliberately failed to comply with regulations, the responsibility of the business owners is difficult to deny.
However, reality shows that the causes do not originate solely from the enterprises, while the ultimate consequences still fall on the business owners themselves, ranging from outstanding financial obligations to administrative measures such as exit suspension, restrictions on invoice use, or difficulties in carrying out certain transactions.
In such circumstances, the question of fairness is not merely whether all outstanding obligations have been collected, but first and foremost whether those obligations have been correctly determined based on the nature and circumstances of each case.
According to Mr. Tuan, when assessing policies applicable to enterprises that have actually exited the market, it is necessary to take into account both the costs of implementing the policies and the social consequences arising in the process.
First is the cost of completing the tax identification number data-cleaning campaign. In addition to the resources required from management authorities, enterprises also have to spend time and incur costs for accounting and legal services, restoring records, completing tax declarations, handling invoices, and covering other expenses arising from prolonged procedures. If an enterprise is no longer operating and has no remaining revenue, every additional cost can become a practical barrier to completing the required procedures.
More broadly, how failed enterprises are treated may also affect the mindset of people considering starting a business.
Businesses can fail, and failure is inherently part of market activity. However, if the cost of exiting the market after failure becomes excessively high and prolonged, business owners may have to consider another type of risk: the risk associated with closing down itself.
“Basically, business owners can accept financial exhaustion resulting from losses because that is a risk inherent in business activities. But if someone has already failed, is no longer operating, and has no remaining income, they should not be pushed into further financial exhaustion by penalties, fees, and compliance costs simply to be able to exit the market.”
Mr. Le Van Tuan, Director of Keytas Accounting and Tax Co., Ltd.
Therefore, any policy option should aim to facilitate remediation of the consequences rather than push taxpayers into financial exhaustion, while still allowing them an opportunity to start over after failure. This does not mean waiving obligations or creating an “escape route” for violating enterprises.
For late submission of tax declaration dossiers, Mr. Tuan proposed establishing an appropriate mechanism for handling declarations that generate no tax liabilities, particularly by considering reductions in penalties. However, removing fees and penalties does not mean waiving tax obligations. Actual tax debts that have arisen must still be addressed in accordance with the law.