The tax authorities’ increasing use of big data and artificial intelligence (AI) to monitor compliance is prompting businesses to pay greater attention to data quality, control systems, and their ability to provide explanations and supporting information.
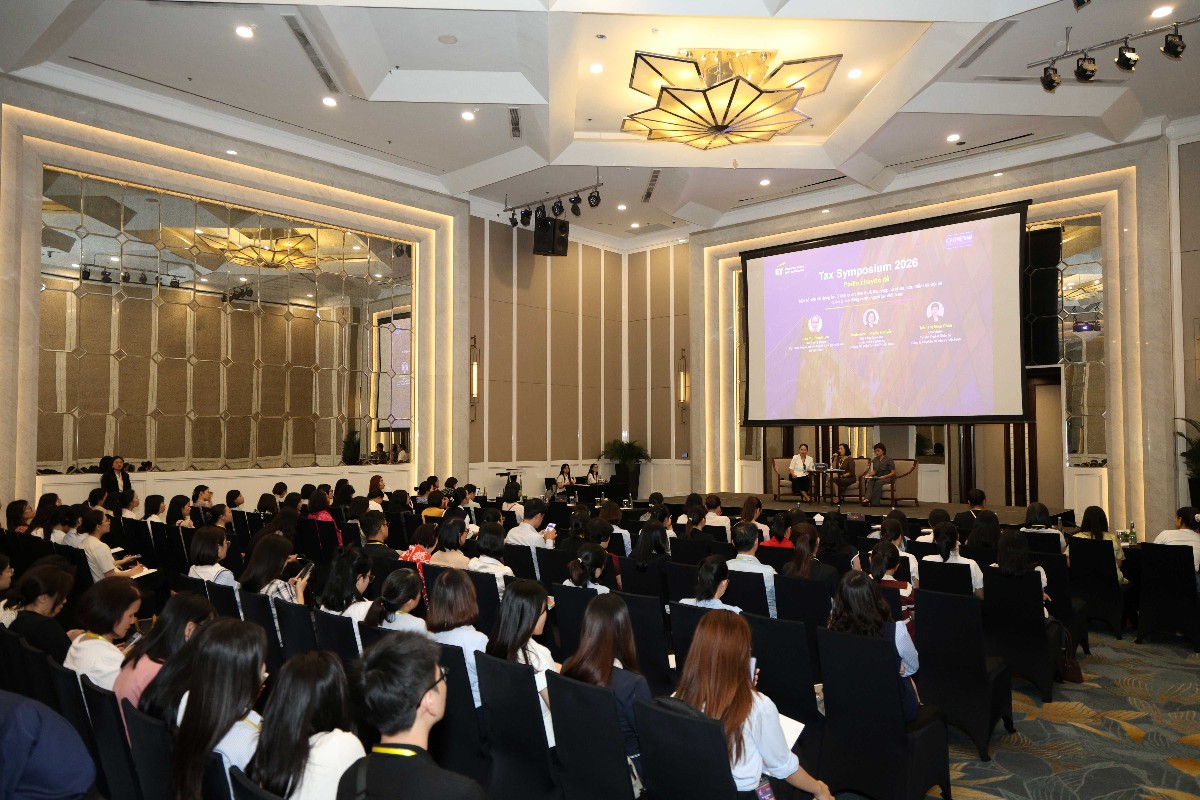
Overview of the event. Source: EY.
This was one of the issues raised at the 2026 Annual Tax Seminar, jointly organized by EY Vietnam Joint Stock Company and the Vietnam CFO Club. The event was attended by representatives of tax authorities, EY experts, and more than 500 executives, finance and accounting department heads from domestic and foreign enterprises.
According to EY, alongside changes in tax policies in 2026, tax administration is also shifting toward the use of big data and AI to monitor compliance and identify risks. When discrepancies or unusual signs are detected, tax authorities may request businesses to provide explanations, submit additional information, or undergo tax inspections and audits.
This trend is not limited to Vietnam. EY cited an OECD report stating that more than 70% of tax administrations have used AI for compliance management, risk assessment, and tax fraud detection.
In Vietnam, according to figures from the Ministry of Finance cited by EY, as of the end of 2025, more than one million enterprises were using electronic tax filing services, equivalent to 99.31%. The Tax Department has also deployed 223 fully online public services and integrated them into the National Public Service Portal.
Against this backdrop, EY considers case-by-case tax management to be no longer suitable. One of the challenges businesses may face is that tax and accounting departments only become involved after a transaction has been completed, while relevant information is held across different departments. This may result in inconsistent data, unexpected tax liabilities, or prolonged processes for providing explanations to the tax authorities.
Ms. Trang Pham, Deputy General Director of Tax Consulting at Ernst & Young Vietnam Limited, said that as data is increasingly used as a basis for tax administration, businesses need to improve information quality and strengthen their financial systems and risk controls.
According to Ms. Huong Vu, Managing Partner of EY Consulting Vietnam, tax considerations need to be incorporated into commercial, legal, financial, and operational decisions, rather than being handled as a separate process after a transaction has been completed.
EY recommends that businesses standardize their processes and systems, improve data quality, and develop comprehensive supporting documentation with clear linkages across different stages. This approach is intended to help businesses provide consistent explanations and supporting evidence when tax authorities conduct inspections or audits.
From a corporate finance perspective, Mr. Nguyen Ngoc Bach, Chairman of the Vietnam CFO Club, said that Chief Financial Officers need to incorporate tax considerations into the business planning process and ensure that management has sufficient data when making decisions. According to him, early preparation can help businesses reduce compliance risks, protect profit margins, and respond to changes in tax policies.