On the afternoon of September 30, State Auditor General Nguyen Huu Nghia chaired a meeting of the Steering Committee for reviewing the implementation of the Development Strategy of the State Audit Office of Vietnam (SAV) through 2030 and formulating orientations for the development of the SAV through 2035, with a vision to 2045. The meeting focused on providing comments on the first draft of the Scheme for the Development of the SAV through 2035, with a vision to 2045.
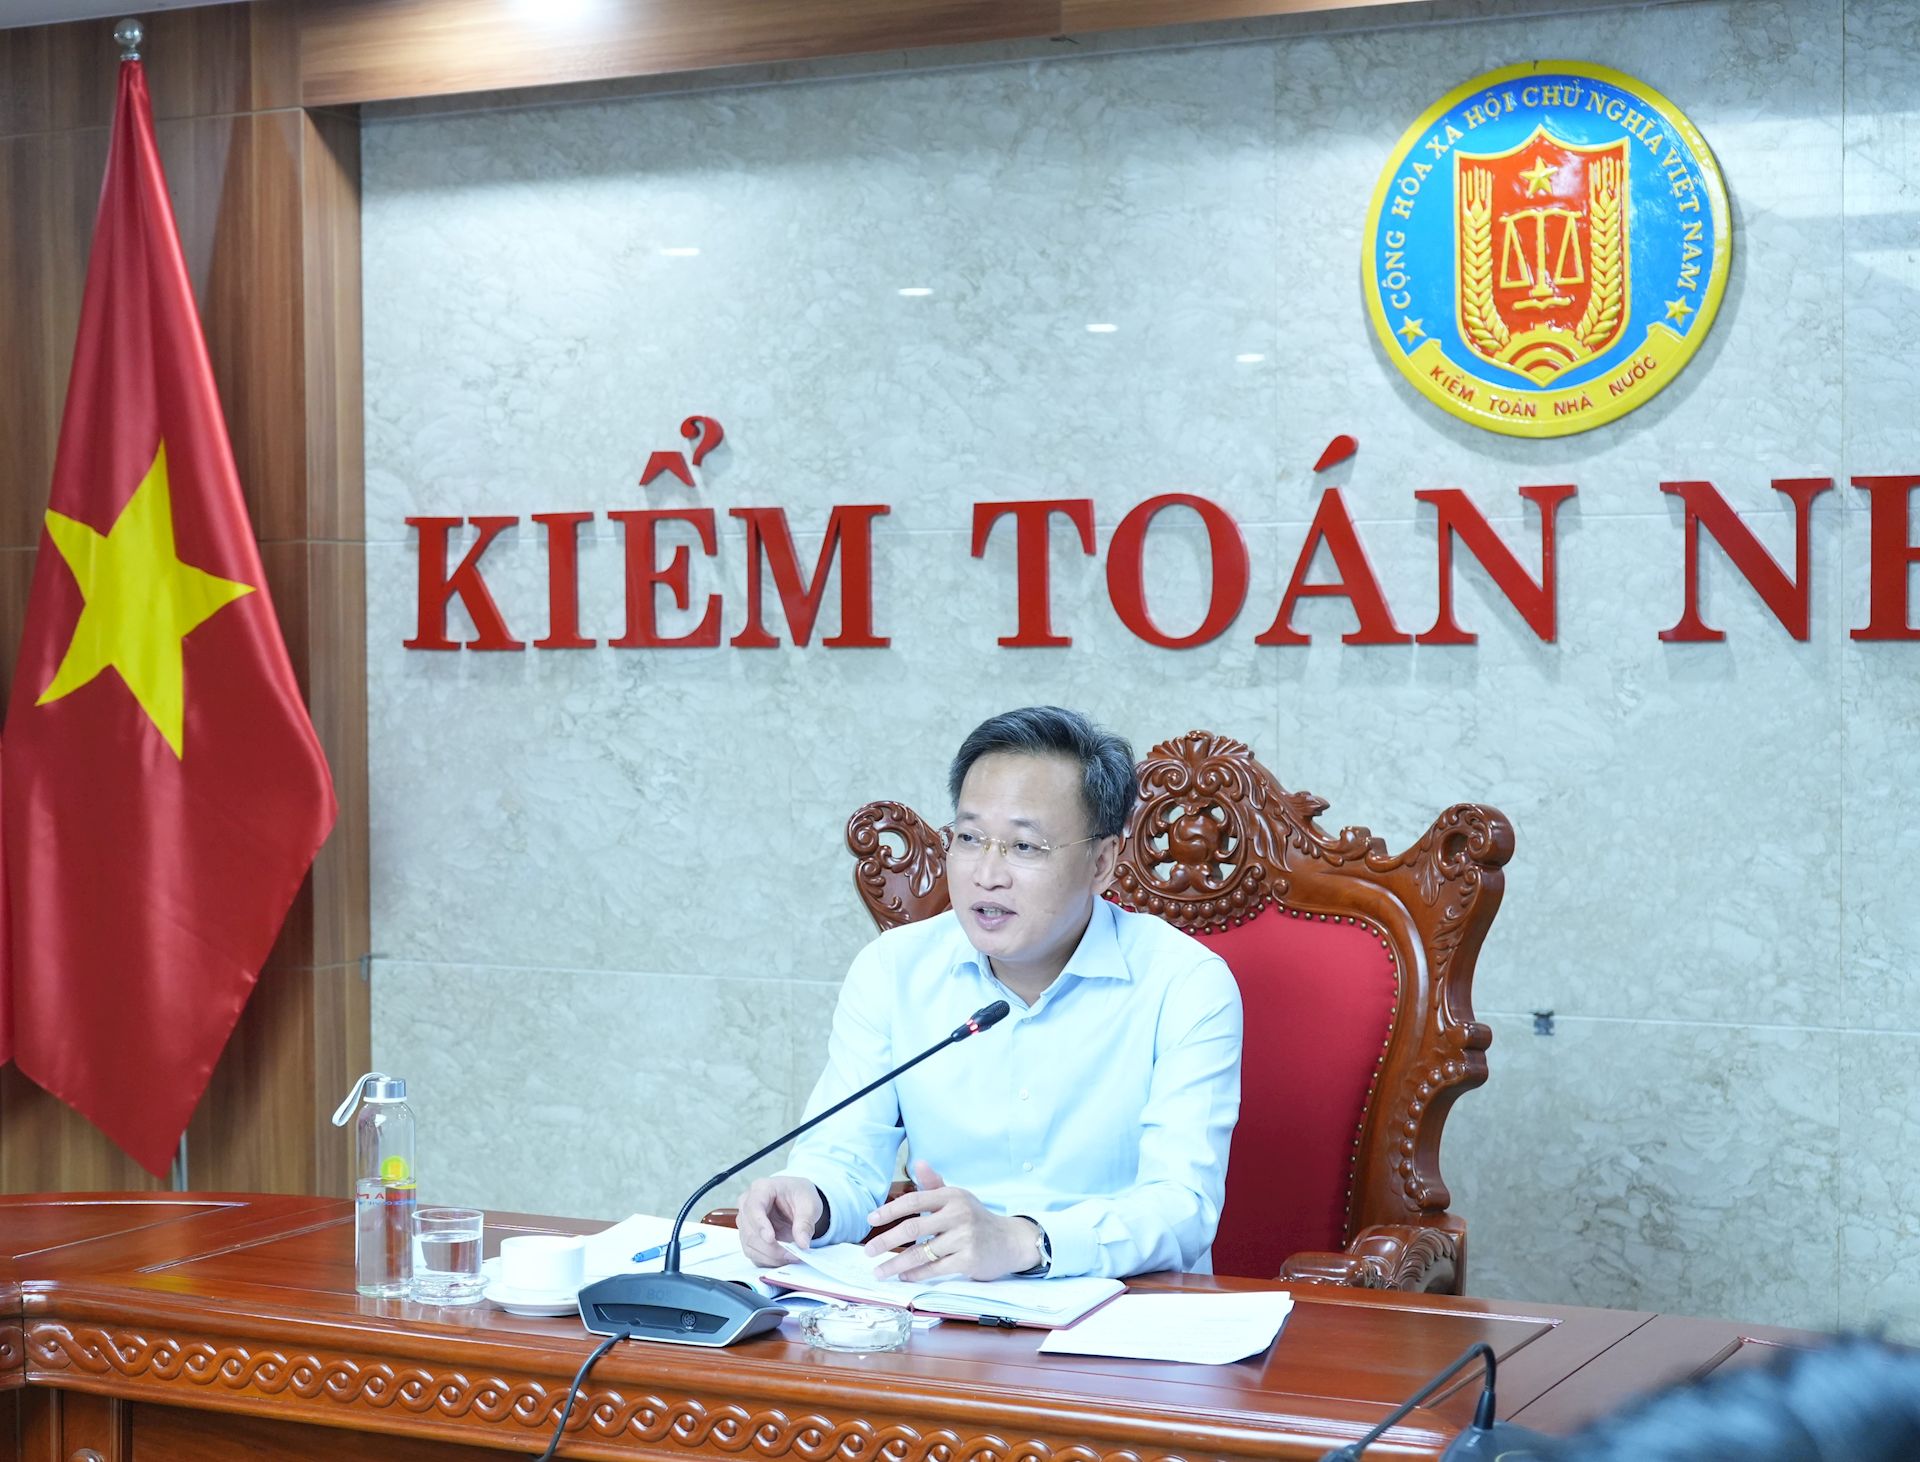
State Auditor General Nguyen Huu Nghia chairs the meeting.
The meeting was held in person at the SAV headquarters and connected online to regional State Audit Offices. Attending the meeting were Deputy State Auditors General Bui Quoc Dung and Ha Thi My Dung, along with members of the Steering Committee.
At the meeting, Hoang Van Luong, Director General of the Department of General Affairs and representative of the Steering Committee's support team, presented a report. Accordingly, following the directions given by SAV leaders at the meeting of the Standing Committee of the Steering Committee on September 9, the support team continued to refine the Draft Scheme.
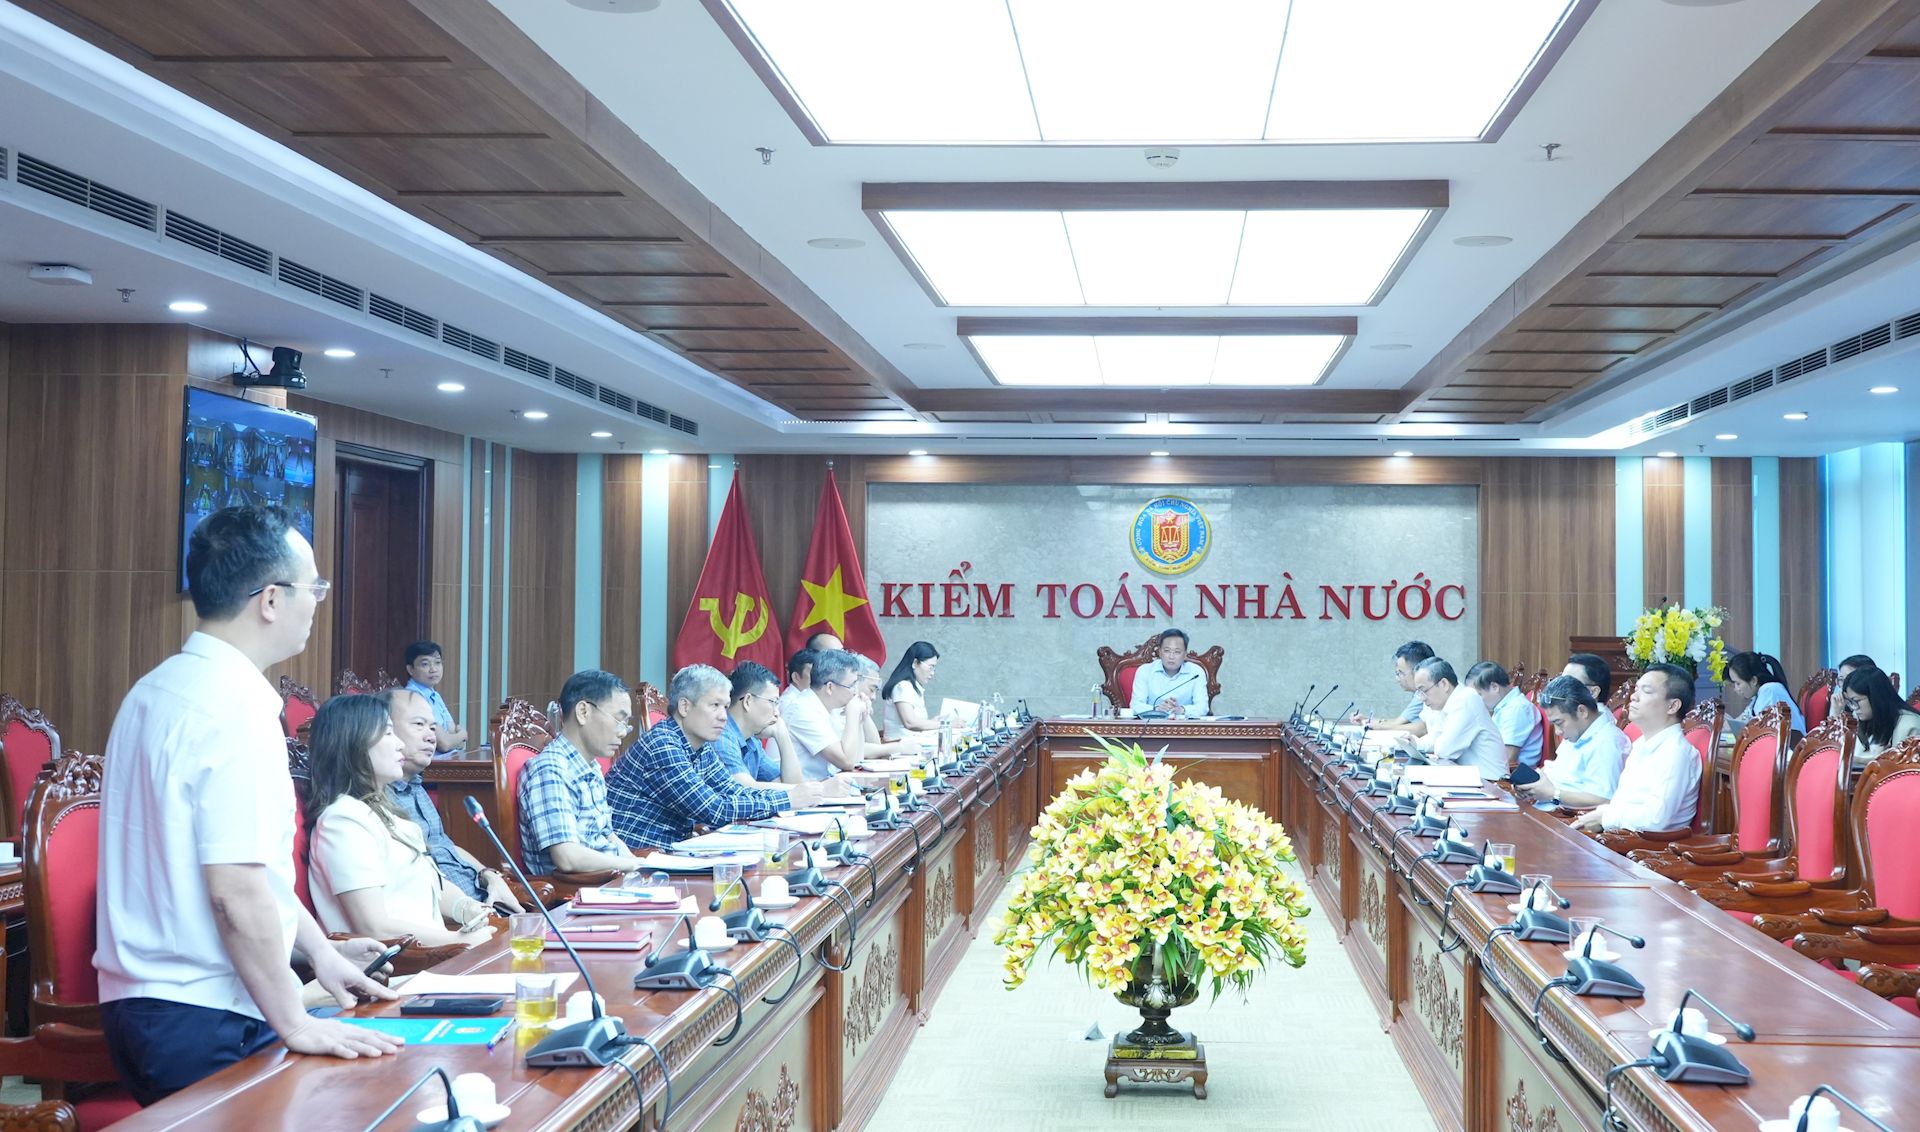
Overview of the meeting.
According to the Draft Scheme, after more than 30 years of establishment and development, particularly after more than half of the period implementing the Development Strategy of the SAV through 2030 under Resolution No. 999/2020/UBTVQH14 of the National Assembly Standing Committee, the SAV has achieved significant results. Its legal framework, system of auditing standards, procedures and methodologies have continued to be improved, while its organizational structure, human resources, physical facilities and technological infrastructure have been gradually strengthened.
At the same time, the quality, effectiveness and scope of the SAV's operations have improved significantly. During the 2021–2026 period, the SAV conducted 885 audits; made recommendations on the handling of more than VND 261 trillion and USD 126 million in financial matters; recommended the amendment, supplementation, replacement or issuance of 1,009 legal and regulatory documents; and transferred 26 cases showing signs of violations of the law to investigative authorities. The rate of implementation of audit recommendations during this period was significantly higher than that recorded in the 2016–2021 period.
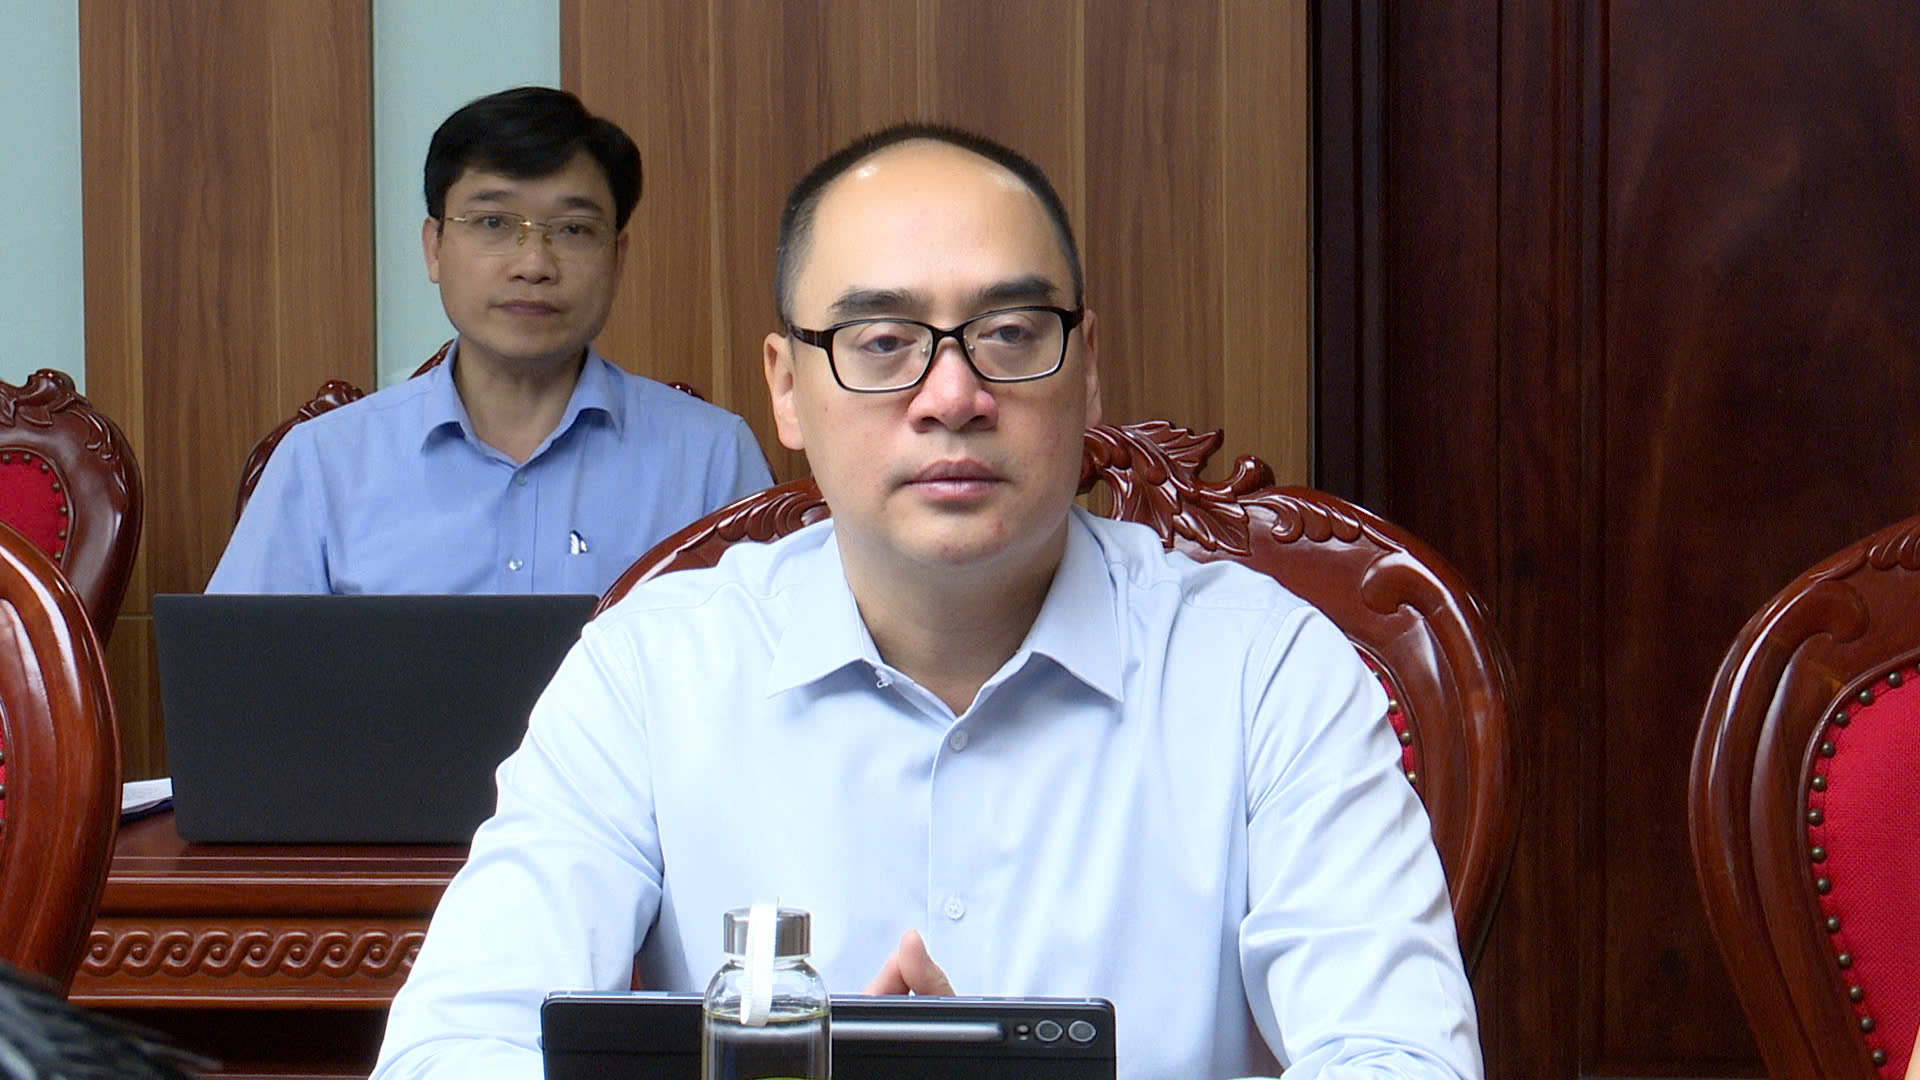
Deputy State Auditor General Bui Quoc Dung at the meeting.
However, practice has shown that the SAV's operations have developed more rapidly than certain aspects covered by the Strategy. A number of new audit tasks, methods and areas have been introduced, including information technology audits, remote audits, major thematic audits, and the application of data analytics, artificial intelligence and remote sensing technology in auditing activities. The SAV has also participated in providing opinions on nationally important projects and supplied information to support legislative activities, oversight and decision-making on important national issues.
The SAV has put into operation 12 software applications supporting management and administration and 13 applications supporting audit activities; gradually digitized audit records, established an audit database and developed the SAV Digital Architecture Framework. These are new areas that have either emerged or been significantly strengthened but have not yet been fully and systematically incorporated into the current Strategy, requiring them to be reviewed, integrated and reprioritized within a unified strategic framework.
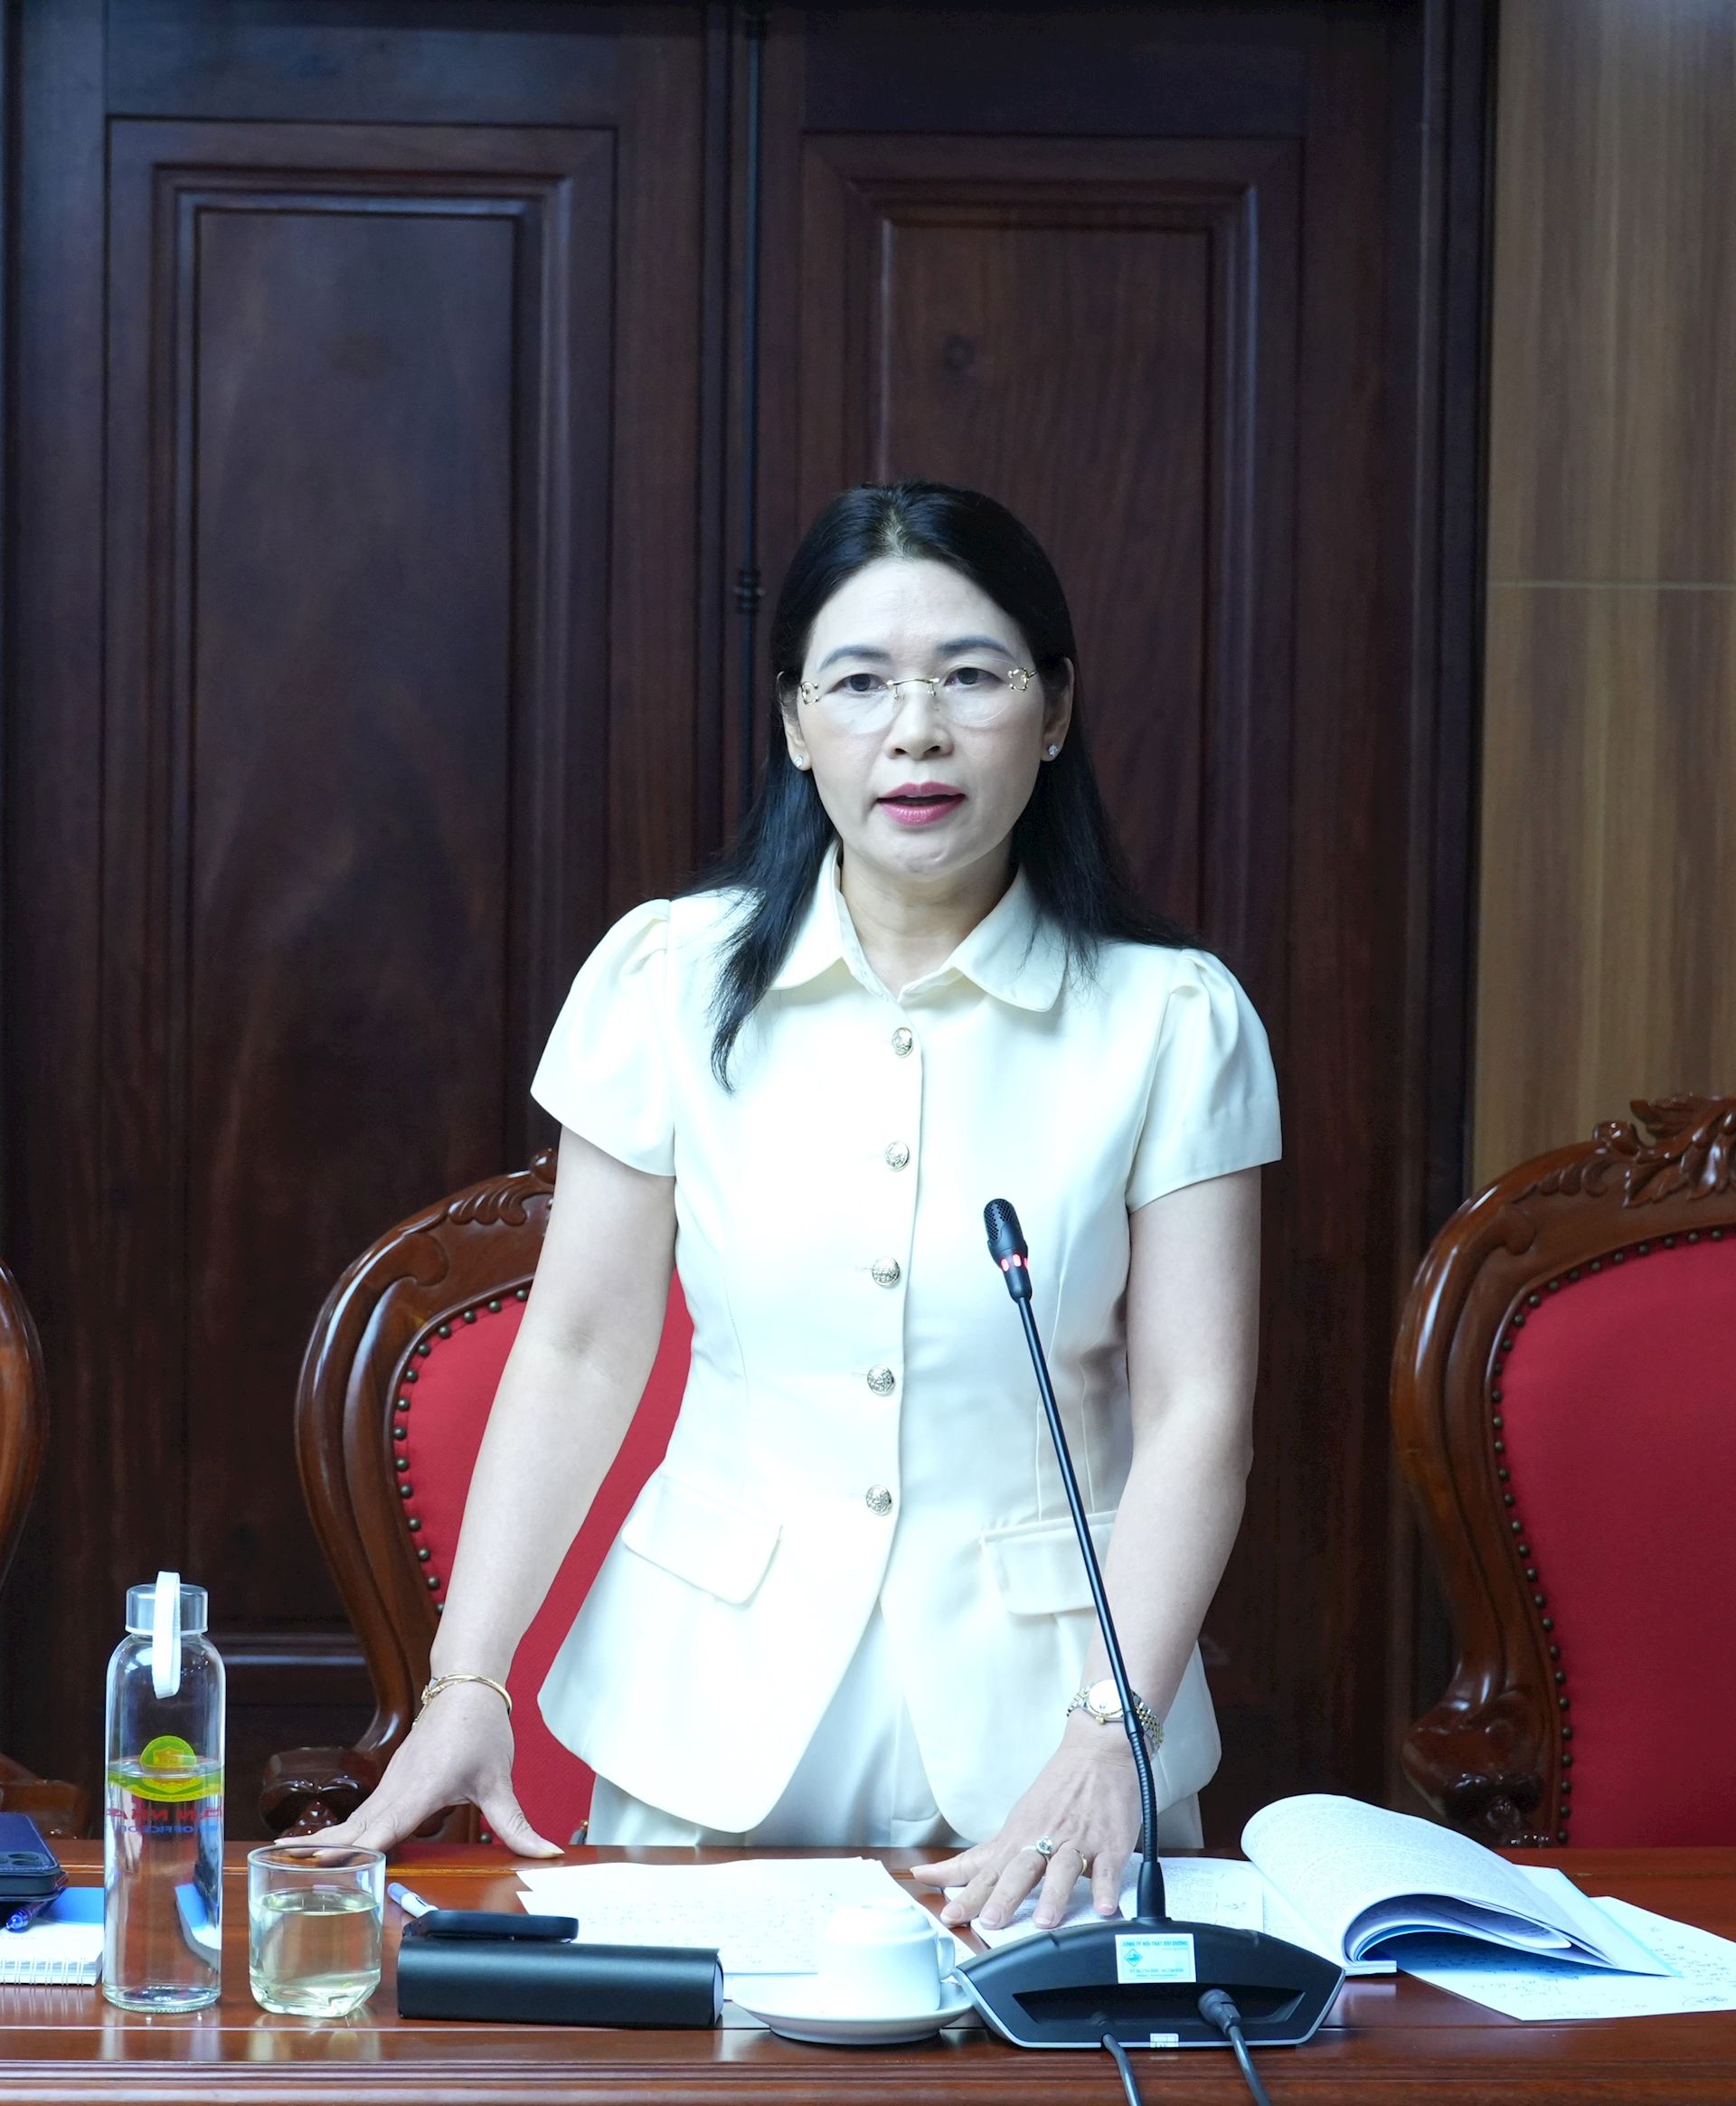
Deputy State Auditor General Ha Thi My Dung speaks at the meeting.
The first draft of the Scheme was developed on the basis of inheriting the contents of the Development Strategy of the SAV through 2030 while incorporating new requirements arising from practical developments, with the aim of establishing a more comprehensive and synchronized long-term development framework for the SAV's operations.
The Draft Scheme provides an overall assessment of the necessity of the Scheme, its theoretical, legal and practical foundations, its objectives, requirements and scope, as well as international experience and standards concerning the operations of supreme audit institutions.
Notably, the Draft Scheme focuses on analyzing several major bottlenecks facing the SAV, including institutions and the legal framework, human resource development, and the quality, effectiveness and efficiency of auditing activities.
On that basis, the Scheme sets out development orientations for the SAV through 2035, with a vision to 2045, focusing on key areas such as development perspectives; overall objectives and a system of specific objectives; development pillars, tasks and implementation solutions; organizational arrangements, resource assurance and implementation monitoring; as well as proposals and recommendations to competent authorities.
At the meeting, delegates assessed the Draft Scheme as having been prepared thoroughly and contributed numerous comments to further clarify issues concerning the legal framework, the role and position of the SAV, improving the quality, effectiveness and efficiency of auditing, human resource development, the application of technology and digital transformation in auditing activities, and the study of international experience.
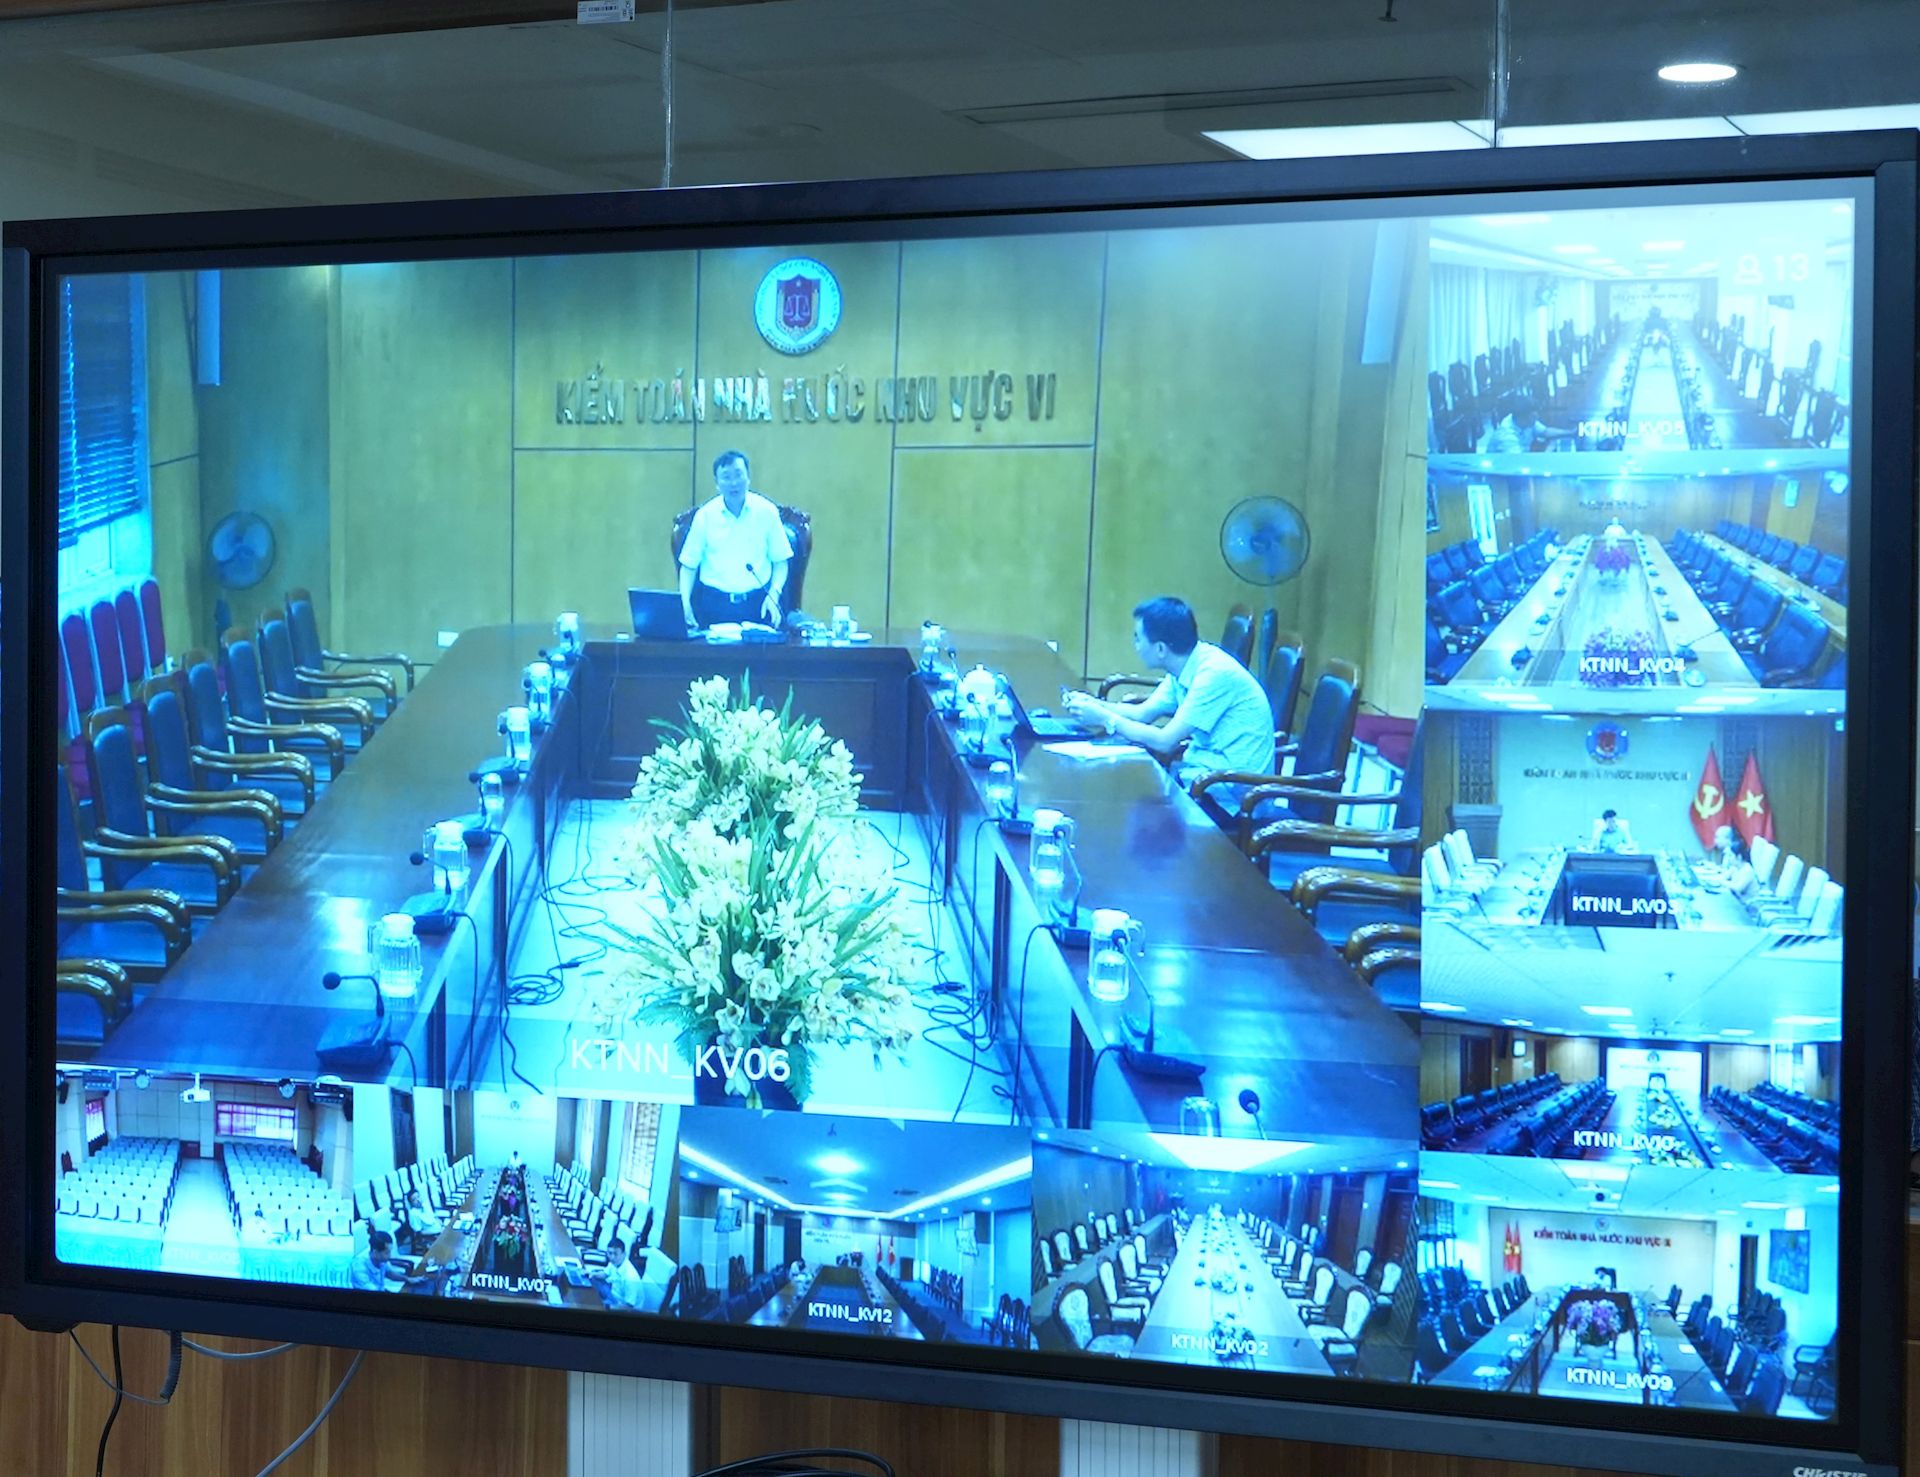
Regional State Audit Offices participate in the meeting via online connection.
Concluding the meeting, State Auditor General Nguyen Huu Nghia highly appreciated the support team for urgently preparing the first draft of the Scheme with all required contents in accordance with the proposed outline. At the same time, the State Auditor General provided further clarification on several important orientations concerning the theoretical foundations; the role of the SAV in policy consultation and advisory work; improving the effectiveness and efficiency of auditing activities; enhancing the value of audit reports and audit conclusions and recommendations; the authority and responsibilities of the SAV; decentralization and delegation of authority within the audit institution; reducing overlaps between SAV activities and inspection activities; as well as the relationship between the SAV and other agencies.
In particular, the Development Strategy of the State Audit Office must be aligned with and meet the requirements of the country's socio-economic development process, as well as the objectives of becoming a developing country with modern industry and upper-middle income by 2030, and a developed, high-income country by 2045.
To further finalize the Scheme, the State Auditor General requested that the support team continue studying and incorporating the comments and conclusions of the Head of the Steering Committee and complete the second draft before October 30. The Standing Committee of the Steering Committee is expected to meet to reach agreement on the Draft Scheme, after which it will be circulated for comments from ministries, sectors and central-level agencies in November 2026.