Increasing the proportion of thematic audits, auditing 100% of state budget finalization reports, and focusing on key and high-risk areas are among the prominent orientations in the proposed 2027 State Audit Plan. The key requirement set by the National Assembly Standing Committee (NASC) is that auditing activities must be closely aligned with the National Assembly's program of activities, while strengthening early warnings, prevention, and policy recommendations to help create a favorable institutional environment for development.
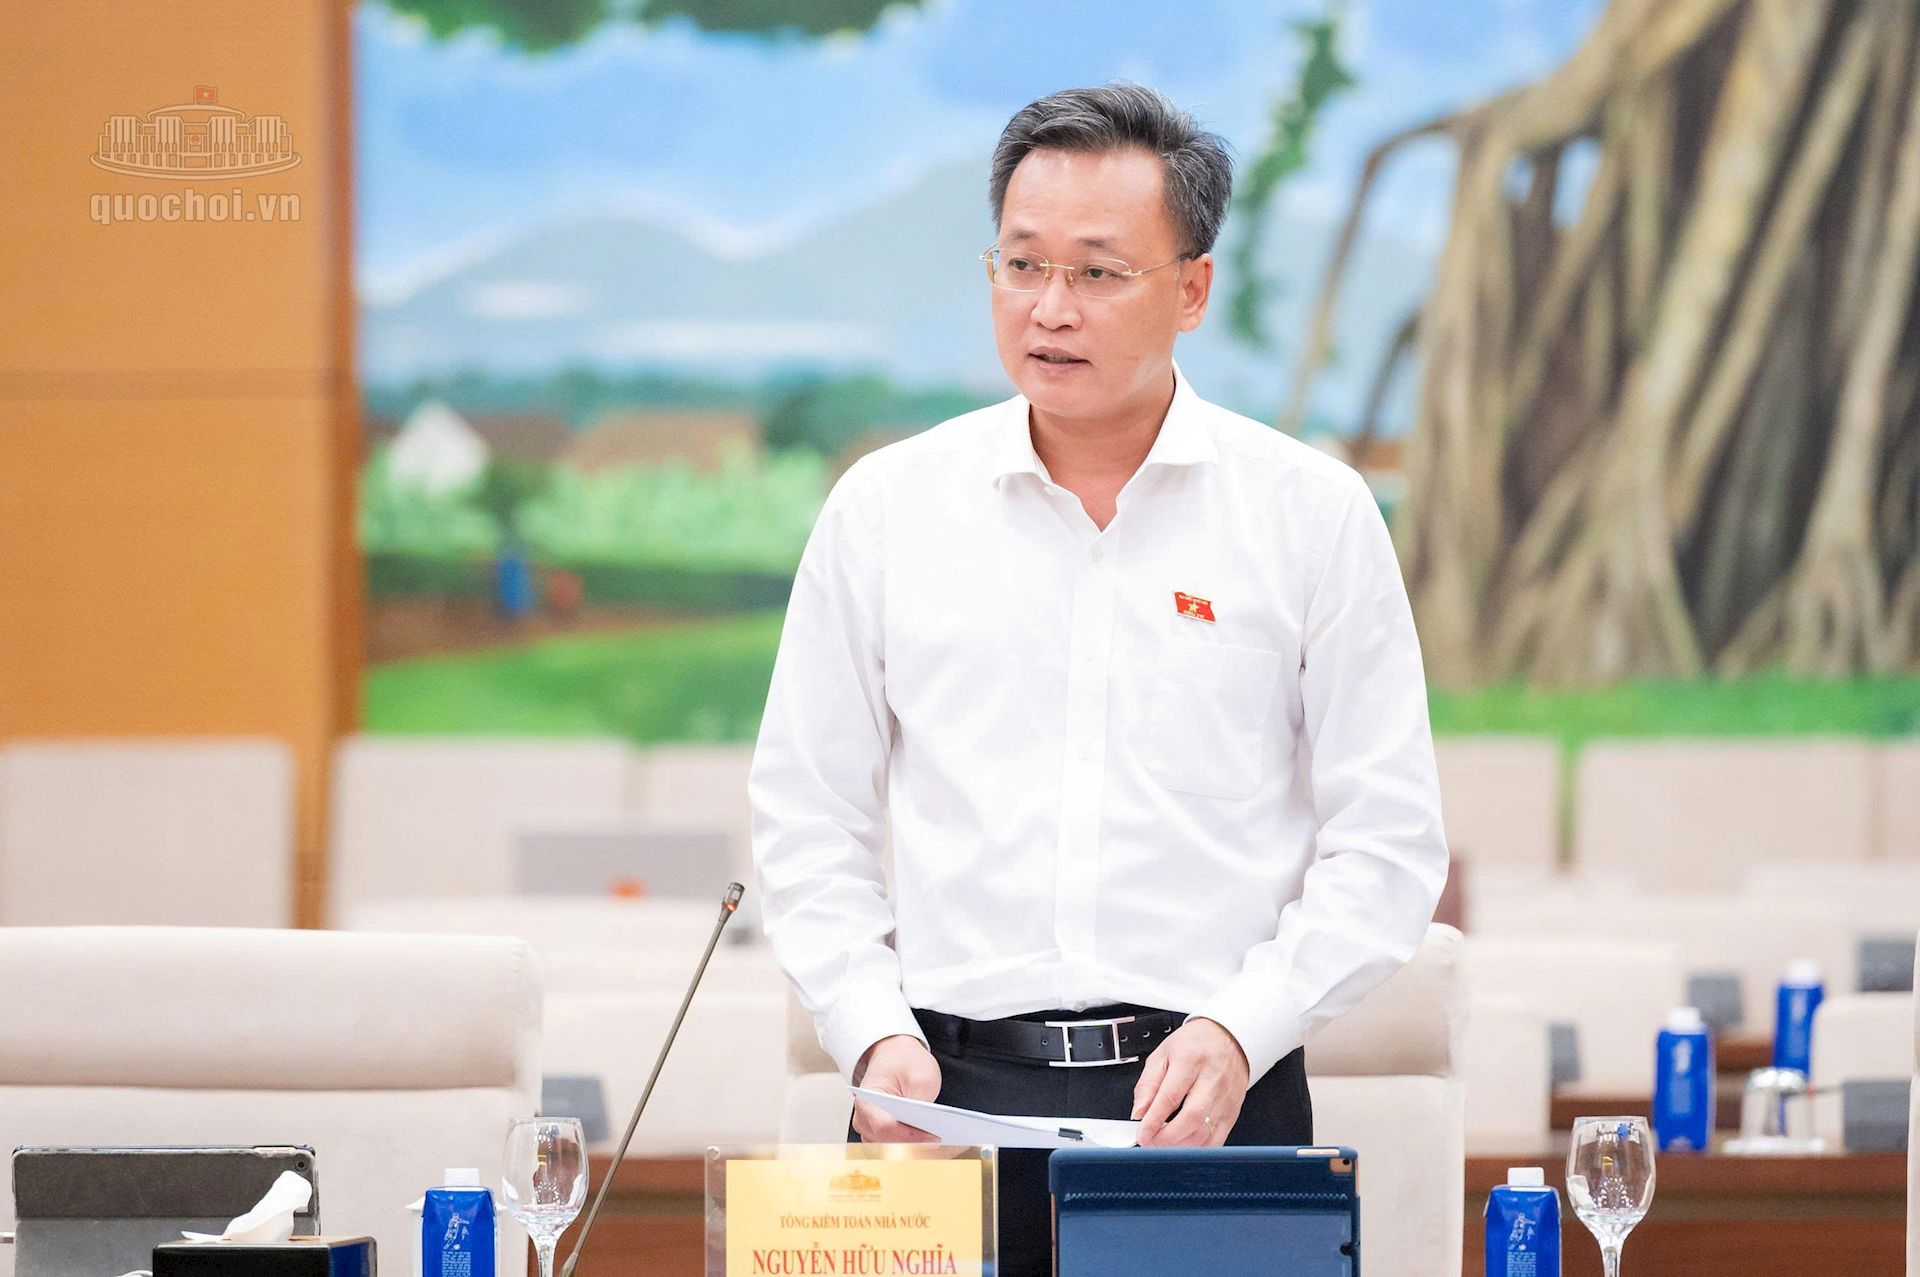
Auditor General of the State Audit Office of Vietnam (SAV) Nguyen Huu Nghia presents the proposed 2027 State Audit Plan to the NASC. Photo: Office of the National Assembly.
Staying Close to Management Practices and High-Risk Areas
Auditor General Nguyen Huu Nghia said that in 2027, the SAV is expected to carry out 139 audit tasks, focusing on six areas: auditing the management and use of assets, public finance, and the state budget; conducting 24 thematic audits; conducting environmental and information technology audits covering seven topics; carrying out 31 audits of investment projects; auditing nine groups and corporations and five financial institutions and banks; and conducting 25 audits in the areas of national defense, security, and central Party agencies.
The SAV will focus on auditing major programs and policies of the Party, particularly a number of strategic resolutions of the Politburo; strengthen audits of key national projects; and focus on entities and areas with significant potential risks and risks of violations, corruption, waste, and other negative practices. This will enable the timely detection and strict handling of violations and shortcomings, as well as inadequacies and obstacles in mechanisms and policies, thereby helping remove bottlenecks and barriers in the management and use of public assets and public finances that may affect the target of double-digit economic growth.
Auditor General Nguyen Huu Nghia
The NASC basically agreed with the SAV's orientation to audit budget finalization reports for 100% of ministries, ministerial-level agencies, central agencies, and localities; increase the proportion of thematic, performance, environmental, and information technology audits; and focus on preventing and combating corruption, waste, and other negative practices.
National Assembly Secretary General and Chairman of the Office of the National Assembly Le Quang Manh assessed that, with 139 audit tasks expected in 2027, the proportion of thematic, performance, environmental, and information technology audits would increase to 39%, compared with 29.5% in the previous year. He considered this an appropriate direction for the SAV.
However, the requirement is that the selection of audit topics must continue to closely reflect major changes in management practices. The National Assembly Secretary General proposed that in 2027, the SAV should conduct in-depth audits of emerging institutional issues, such as the two-tier local government model, digital transformation, and artificial intelligence. “Through auditing, sufficiently in-depth conclusions can be drawn to help address the difficulties currently arising,” the National Assembly Secretary General emphasized.
Over the past two to three years, the National Assembly has spent considerable time issuing mechanisms and policies to resolve difficulties facing projects, yet localities have so far proposed only 24 projects for audit. The SAV needs to assess substantively whether the mechanisms that have been issued have actually helped remove difficulties and unlock resources. This is important for achieving the 10% growth target and other objectives.
National Assembly Secretary General Le Quang Manh
According to National Assembly Vice Chairwoman Nguyen Thi Hong, the State Audit Plan should closely follow the action program implementing the 14th National Party Congress Resolution, as well as new strategic resolutions and conclusions of the Central Committee and the Politburo and major issues of concern to the National Assembly, voters, and the public. The focus should be on sectors, programs, policies, and projects involving significant resources and high risks, particularly public investment and nationally important projects; land and public assets; state capital and assets in enterprises; finance and banking; science and technology; and digital transformation.
Regarding the audit of the state budget and the 2026 budget finalization reports, the NASC noted the need to take into account the implementation of the 2025 Law on the State Budget and the operation of the two-tier local government model, including the allocation of revenue sources and expenditure tasks, the transfer of assets, projects, debts, and funding following the restructuring. The timing of audits and the issuance of audit reports should also be aligned with the schedule for reviewing and approving budget finalization reports.
Auditing Must Create Value for Legislative and Oversight Activities
A consistent point emphasized by members of the NASC when commenting on the proposed 2027 State Audit Plan was the requirement to closely link the plan with the activities of the National Assembly. National Assembly Chairman Tran Thanh Man emphasized that the State Audit Plan is an important component of the information system supporting the National Assembly. Therefore, the SAV needs to provide independent, objective, in-depth information that is valuable to legislative activities, oversight, and decision-making on important national issues.
Accordingly, the development of the State Audit Plan should not be limited to identifying entities and areas subject to audit, but should be closely connected with the legislative agenda, oversight program, consideration of budget estimates and allocations, budget finalization, and other important decisions of the National Assembly and the NASC. The SAV needs to closely coordinate with National Assembly agencies from the planning stage in order to identify issues that require focused auditing.
In particular, the National Assembly Chairman emphasized the core requirement of evaluating the effectiveness of audit activities. According to the Chairman, an important objective of auditing is to improve the voluntary compliance of ministries, sectors, and localities.
“The role of the SAV is extremely important at present, directly affecting personnel-related work as well as the consideration and appointment of personnel in localities and sectors. Therefore, going forward, the SAV needs to focus on key and priority tasks and further strengthen its role in early warning, prevention, and policy recommendations,” the National Assembly Chairman emphasized.
At the same time, requirements concerning the quality of individual audits were also raised. The National Assembly Chairman agreed on continuing to increase the proportion of performance, thematic, information technology, and environmental audits, while ensuring that each thematic audit has clear objectives, tangible outputs, and practical value for management and oversight activities.
Improving the quality of recommendations for institutional improvement is a task that needs to see clear progress in 2027. Audit results must be consolidated and analyzed at the policy level to identify systemic issues, thereby providing recommendations for amending legislation, improving management mechanisms, and addressing shortcomings in policies.
National Assembly Chairman Tran Thanh Man
At the same time, increasing the proportion of these types of audits must be accompanied by assessments of economy, effectiveness, and efficiency; risk-warning capabilities; appropriate audit methodologies, human resources, and quality-control mechanisms; as well as continued promotion of data-driven auditing, remote auditing, and the controlled application of artificial intelligence.
Alongside the quality of audit activities, there is also a requirement to strengthen discipline, compliance, and professional ethics. Chairwoman of the National Assembly's Committee on People's Petitions and Supervision Le Thi Nga proposed that the SAV strengthen personnel management within audit teams and ensure that there is no harassment or misconduct. National Assembly Vice Chairwoman Nguyen Thi Hong also emphasized the need to strengthen auditors' professional capabilities, discipline, compliance, professional ethics and integrity, as well as efforts to prevent and combat corruption, waste, and other negative practices in audit activities.
Members of the NASC affirmed that the implementation of audit recommendations, particularly recommendations to amend legal documents, is one of the practical contributions of auditing. Therefore, such recommendations should continue to be monitored and followed through until full implementation.