Member of the Party Central Committee, Secretary of the Party Committee, and Auditor General of the State Audit Office of Vietnam (SAV) Nguyen Huu Nghia asked SAV Area I to proactively propose audit tasks appropriate to its available resources, based on the actual situation in the localities under its jurisdiction. This would enable the unit to support, accompany, and facilitate local socio-economic development while effectively serving as a bridge between the SAV and local Party committees and authorities.
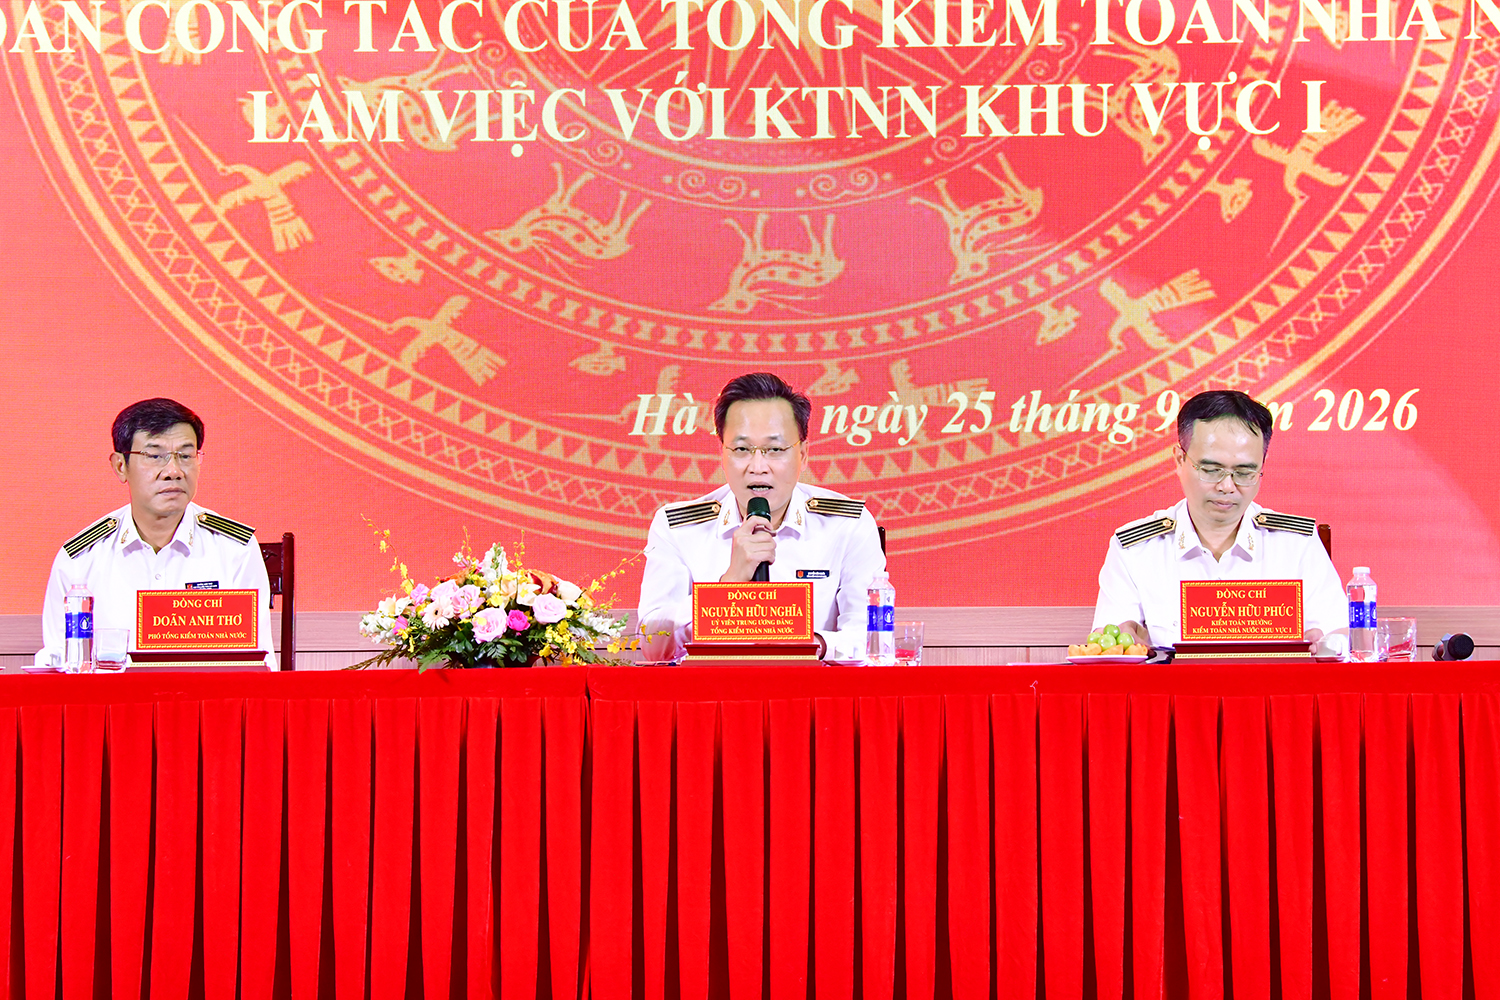
Auditor General of the State Audit Office of Vietnam Nguyen Huu Nghia speaks at the Conference.
On the afternoon of September 25, in Hanoi, Member of the Party Central Committee, Secretary of the Party Committee, and Auditor General of the State Audit Office of Vietnam Nguyễn Hữu Nghĩa chaired a working conference with SAV Area I on the implementation of its assigned tasks and orientations and solutions to improve the unit’s operational quality in the coming period.
The Conference was attended by Deputy Auditor General Doãn Anh Thơ and leaders of SAV-affiliated units in Hanoi.
Representing SAV Area I were Auditor General Nguyễn Hữu Phúc, Deputy Auditors General, and all civil servants and employees of the unit.
Nearly VND 157 trillion in financial adjustments recommended
SAV Area I is assigned to audit Hanoi and Son La Province. Over more than 31 years of establishment and development, SAV Area I has conducted 301 audits, including 149 audits of local budgets and local budget settlement reports, accounting for 49.5%, thereby providing information for local People’s Councils to approve budget settlements in accordance with regulations. In addition, the unit has conducted thematic and performance audits, with their proportion increasing in line with the overall orientation of the sector.
Since its establishment, SAV Area I has recommended financial adjustments totaling approximately VND 156.933 trillion. Many thematic, performance, and local budget audits have not only recommended financial adjustments but also called for improvements to mechanisms and policies, the closing of loopholes, and clearer determination of the responsibilities of different levels in the management of public finances and public assets.
In 2026 alone, as of September 20, SAV Area I had launched all 8 of its planned audits, of which 6 had been completed and 2 were ongoing. The unit had issued 3 Audit Reports, while the remaining audits were undergoing the prescribed review, finalization, and report issuance procedures.
Auditor General Nguyen Huu Nghia discusses and provides specific feedback on issues raised by delegates at the Conference.
In the third quarter of 2026, SAV Area I conducted performance audits of two investment projects: Component Project BRT 01 (Kim Ma – Yen Nghia) under the Hanoi Urban Transport Development Project, and the Xuan La Resettlement Area Project serving the development of the Tay Ho Tay New Urban Area. The audits were conducted in accordance with the sector’s guidelines, ensuring quality and notable results.
The thematic audits on enterprise management and the management and use of investment capital during the 2021–2025 period in Hanoi have been completed. The thematic audit on the use of funds at public educational institutions during the 2023–2025 period provided timely information to the Hanoi People’s Committee at the same time as the city was arranging and reorganizing educational institutions in the area, thereby enhancing the effectiveness and value of the audit recommendations.
The financial adjustments recommended from 6 of the 8 audits under the 2026 audit plan and one audit under the 2025 Audit Plan totaled VND 5.511 trillion, while other adjustments amounted to VND 3.969 trillion.
In particular, SAV Area I recommended amendments and supplements to 11 mechanisms and policies and called for reviews of the responsibilities of 38 collectives and individuals. The unit also transferred information on two enterprises showing signs of violations of tax laws to the Investigation Police Agency of Hanoi for consideration and handling within its jurisdiction, and notified the Hanoi People’s Procuracy in accordance with regulations.
Regarding the implementation of audit recommendations, in 2026, SAV Area I proactively launched and completed inspections of the implementation of audit recommendations in Hanoi and Son La Province ahead of schedule. As of September 20, the implementation rate of recommendations contained in Audit Reports issued from 2025 and earlier reached 88.1%. For recommendations contained in the 2025 Audit Reports alone, the implementation rate reached 89.2%, with financial adjustment recommendations reaching 97.3%.
In Party building, the Party Committee of SAV Area I promptly consolidated its affiliated Party cells, reviewed and issued regulations, resolutions, and leadership and directive documents, and organized the dissemination and implementation of resolutions and directives of the SAV Party Committee.
In the coming period, closely following the directives and resolutions of the Party Committee and the direction of the Auditor General, SAV Area I will focus on several key tasks: completing the 2026 audit tasks on schedule and with quality assurance; proactively preparing early for the 2027 Audit Plan, linking plan development with enhanced audit capacity; continuing to transform audit methods toward specialized, data-driven approaches and “auditing issues through to completion”; strengthening Party building, quality control, discipline, and order, while developing a team of auditors capable of meeting the requirements of reform; and enhancing coordination and exchanges with localities, linking audit activities with major issues in management and administration.
At the Conference, delegates presented papers further clarifying a number of issues, including difficulties and obstacles encountered in audit implementation and proposals during the process of revising SAV procedures and regulations and reviewing the implementation of the State Audit Law; difficulties and proposals regarding the proactive application of information technology and digital transformation in the operations of SAV Area I; and solutions to enhance the effectiveness and value of audit recommendations in the coming period.
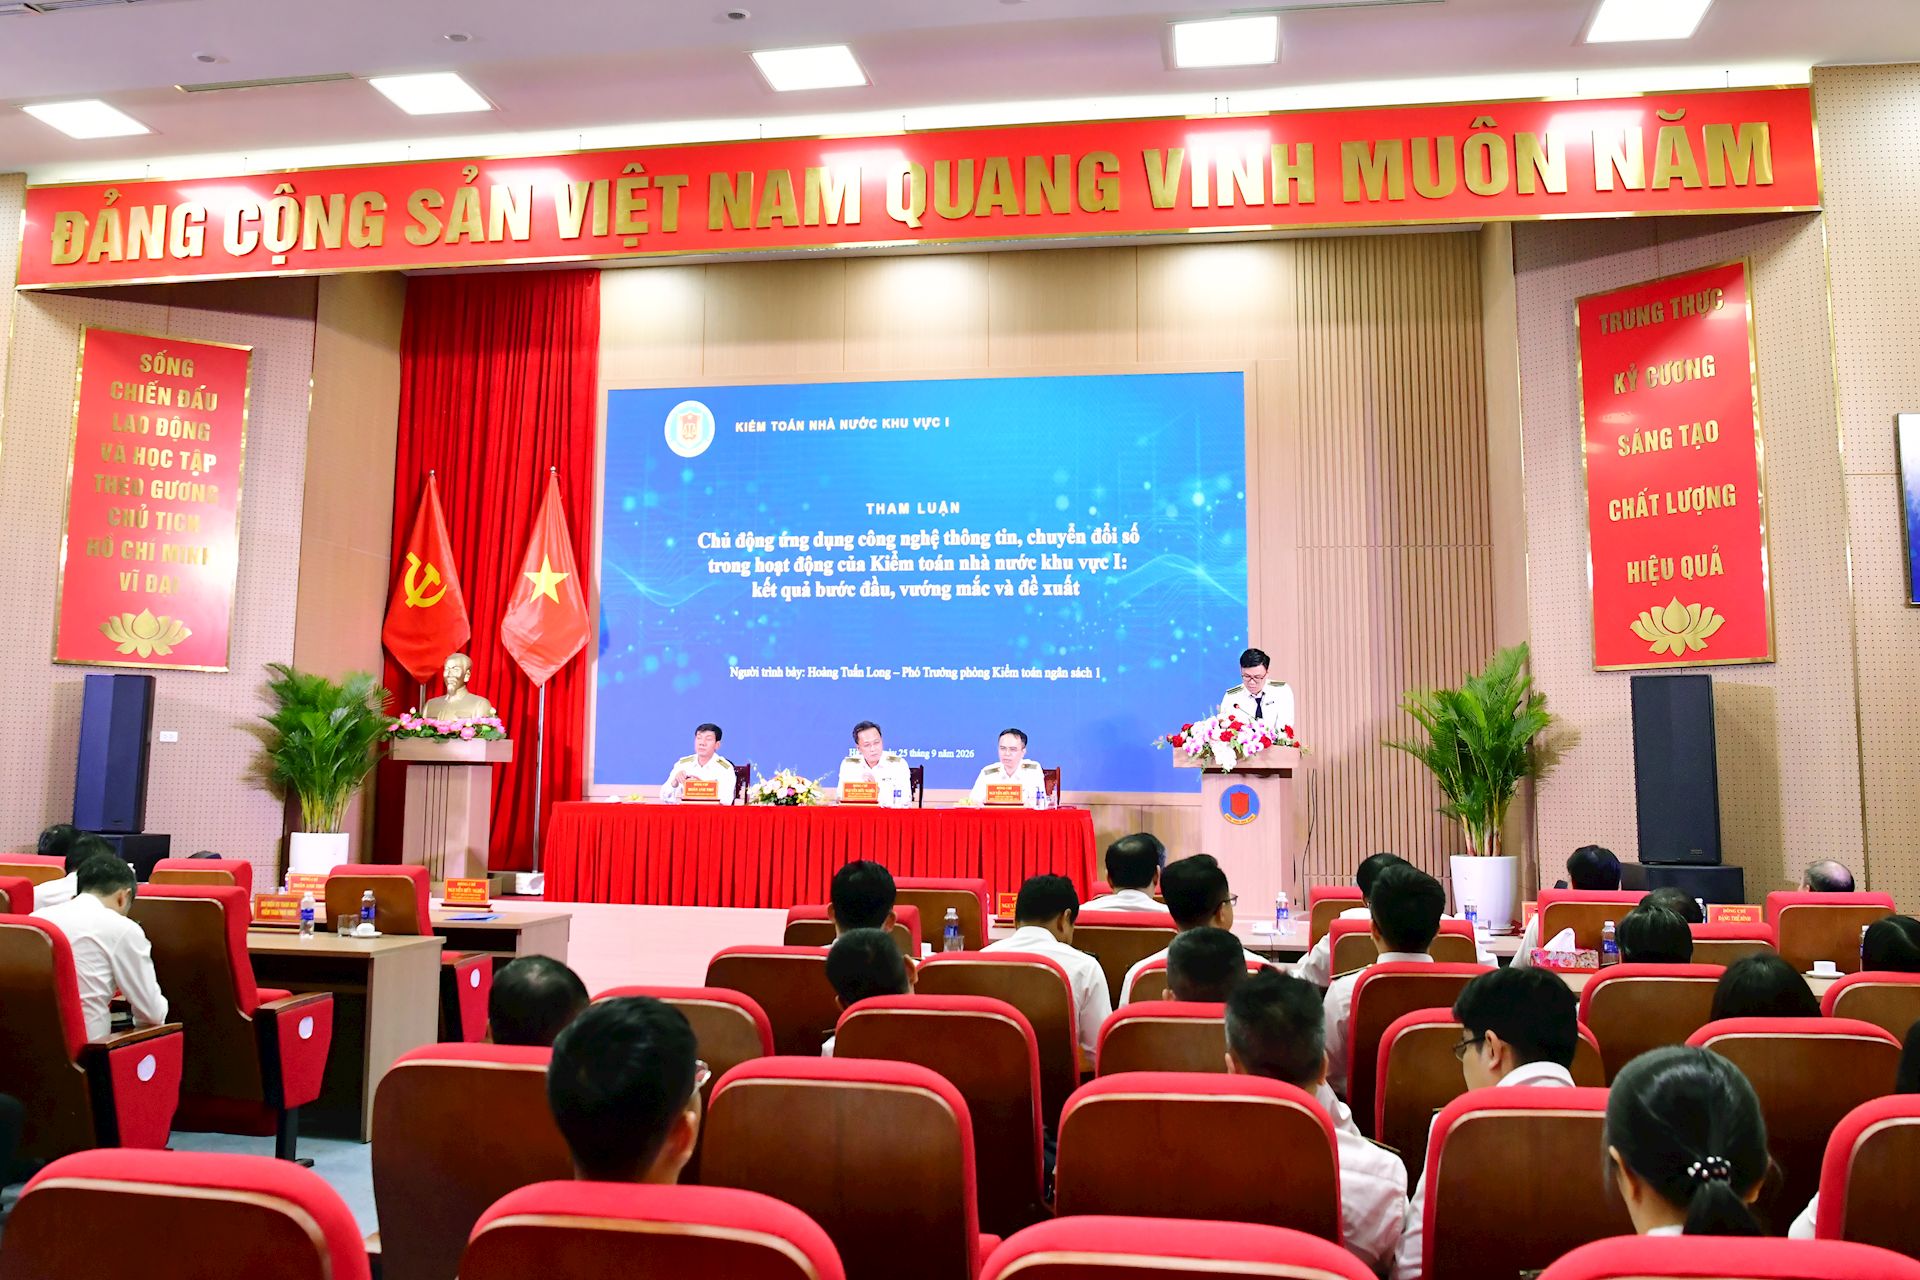
Overview of the Conference.
SAV Area I has performed well and will do even better in the coming period
Addressing the Conference, Auditor General Nguyen Huu Nghia discussed and provided specific guidance on each issue raised by the delegates, including participation in local budget estimates; difficulties in conducting performance audits; digital transformation and the application of AI; and the implementation of audit conclusions and recommendations.
Regarding orientations and tasks for the coming period, Auditor General Nguyen Huu Nghia said that the SAV would focus on sector-wide issues based on themes, major orientations, and major policies of the Party and State. At the same time, based on the actual situation in the localities, after completing thematic audits under the sector’s general directives, SAV Area I should proactively propose audit tasks appropriate to its available resources.
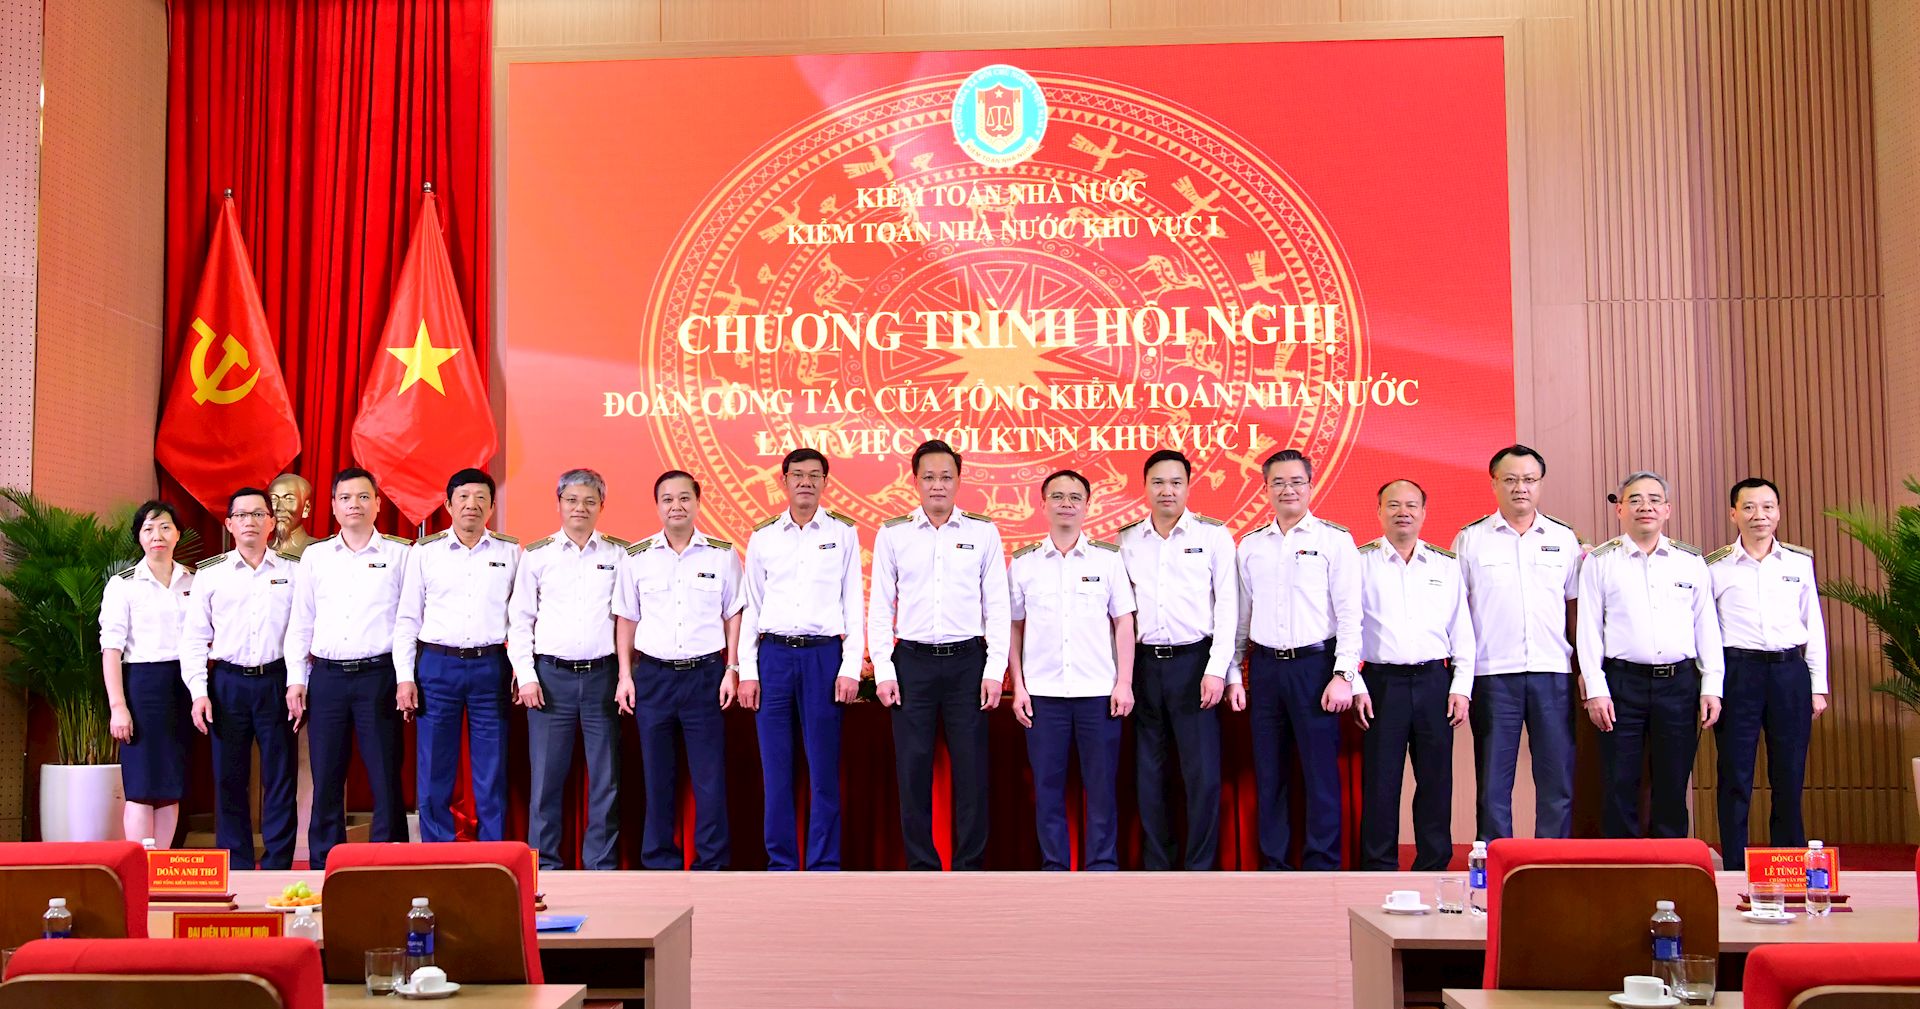
Delegates pose for a group photo.
This proposal stems from the specific characteristics of the area, which includes the capital city and a key driver of the country’s development. In practice, it is clear that each road and each major investment project in the city is creating momentum and providing a strong impetus for development. Significant resources from both the private sector and public sector, channeled through key projects, are expected to continue emerging in large volumes in the coming period.
Therefore, the Auditor General asked the Auditor General of SAV Area I to closely monitor the local area and its actual conditions in order to propose audit contents and subjects appropriate to the sector’s requirements. This would enable the unit to support, accompany, and facilitate local socio-economic development while effectively serving as a bridge between the SAV and local Party committees and authorities.
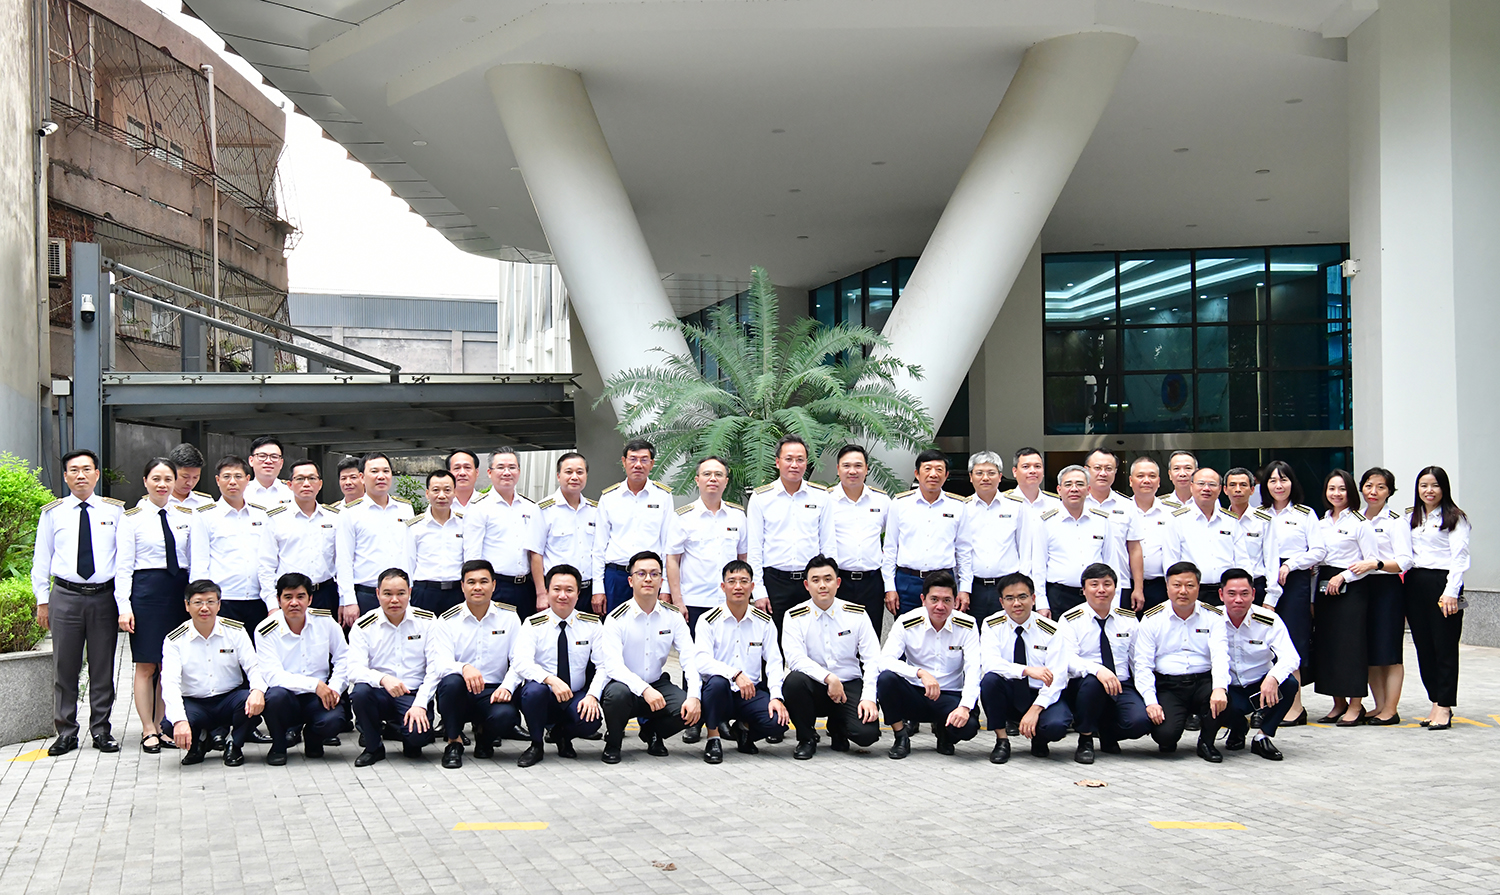
Auditor General Nguyen Huu Nghia takes a photo with the unit’s staff.
In particular, the Auditor General emphasized that later that afternoon, a coordination regulation would be signed between the SAV and Hanoi and Son La Province. The regulation is highly significant, with a major difference from previous coordination regulations: the direct participation of Party committees at various levels in the implementation process. This would help address the difficulties and obstacles faced by auditors, particularly in implementing audit conclusions and recommendations.
According to the Auditor General, when the Secretary of a Provincial or Municipal Party Committee becomes directly involved, the situation will be very different. This also presents a valuable opportunity for the Auditor General to communicate directly with Party committee secretaries and request that they direct inspections of departments and agencies that have not yet implemented audit conclusions and recommendations, thereby avoiding the risk of losses of State funds and assets.
Sharing his expectations with SAV Area I, the Auditor General emphasized: “I hope that all of you will remain united and work together under the leadership of the Party Committee, the Secretary of the Party Committee, and the leadership of SAV Area I to successfully fulfill your assigned tasks. With the direction of the Party Committee and SAV leadership, I have great confidence that SAV Area I has performed well and will perform even better in the coming period, despite the fact that its tasks will be much more difficult and complex.”
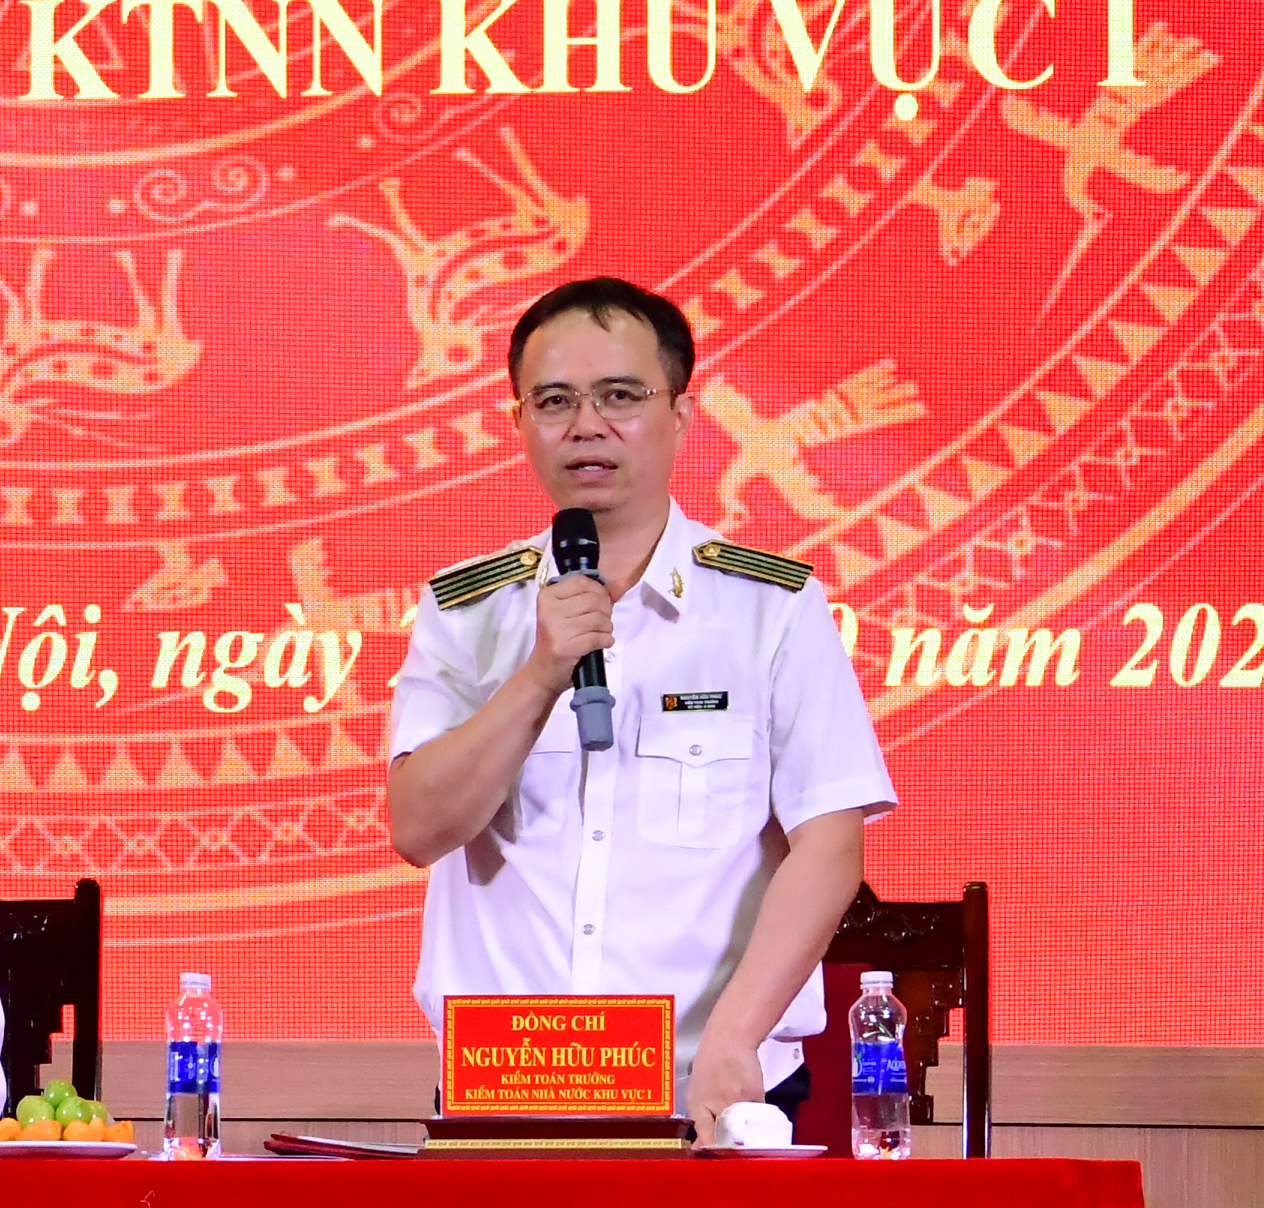
Auditor General of SAV Area I Nguyen Huu Phuc delivers his response.
In his response, Auditor General of SAV Area I Nguyen Huu Phuc expressed his sincere thanks and said that he would fully accept the guidance provided by the Auditor General and incorporate it into the unit’s work programs and plans for the coming period, striving to successfully fulfill all assigned tasks.