Approximately 180 information technology (IT) proposals are currently being reviewed and categorized by the State Audit Office of Vietnam (SAV) to identify “major challenges” that address urgent needs, have a broad impact and are practically implementable. In an interview with Audit Newspaper, Pham Huy Thong, Director General of the Department of Information Technology, said that the selected challenges would not only address individual operational needs but also tackle cross-sector issues, connect data and shared platforms, and lay the groundwork for digital auditing and modernized governance.
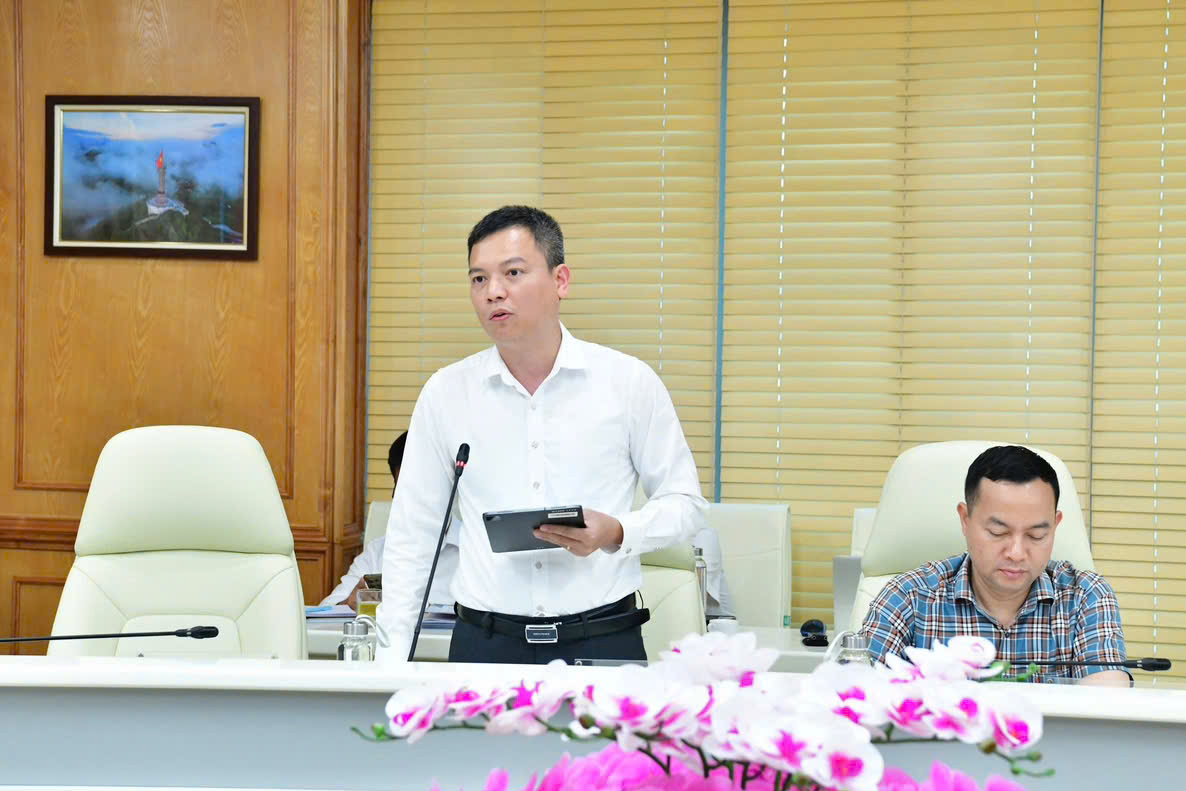
Pham Huy Thong, Director General of the Department of Information Technology
Given the practical requirements of management, administration and auditing, the SAV is focusing on developing “major IT challenges.” Could you tell us how this task has progressed so far?
The identification of “major IT challenges” aims to pinpoint practical issues that need to be prioritized in management, administration and auditing. This will help the SAV select appropriate digital transformation tasks that align technology with operational requirements and work efficiency.
As the standing body of the SAV’s Steering Committee for the Development of Science, Technology, Innovation and Digital Transformation, the Department of Information Technology (DIT) issued an official dispatch at an early stage requesting units to propose operational challenges and identify their needs for commercial software.
To date, the DIT has received approximately 180 proposals and is reviewing and categorizing them to clarify their content, scope and priority levels.
The proposals indicate substantial demand for technology applications across the SAV’s units. To gain a clearer understanding of operational issues, implementation processes, data sources, potential for shared use and connectivity requirements with existing systems, the DIT will continue working with the relevant units to refine requirements, group similar proposals and identify issues with a broad impact to formulate the sector’s “major challenges.”
In parallel, the SAV is developing its Digital Architecture Framework. In conjunction with this process, the DIT will prepare a list of implementation tasks for the 2026–2030 period. This will provide a basis for further refining the list of “major challenges,” ensuring consistency between the units’ practical needs and the sector’s overall digital transformation strategy.
The State Auditor General recently requested that the list of “major challenges” be approved before October 15. How is the DIT coordinating with relevant units to ensure that each challenge meets the required timeline and quality standards?
To meet the deadline set by the State Auditor General, the DIT is focusing on consolidating, reviewing and categorizing the proposals received. This preparatory step will enable the DIT to consult operational units, clarify each group of challenges and finalize the list for submission to the competent authority for consideration and approval.
The implementation schedule is linked to the development of the sector’s list of tasks for the 2026–2030 period, based on the Digital Architecture Framework currently under development. This list of tasks is expected to be completed soon and will serve as a basis for further refining the list of “major challenges.”
According to the plan, following the consolidation and categorization stage, the DIT will consult operational units to clarify processes, data, expected outputs, scope of use, priority levels and designated focal points. Each unit must clearly identify the issues it faces, the expected outcomes and its responsibilities for coordination and implementation. For proposals with overlapping content or involving multiple units, the scope of each challenge must be agreed upon and a lead unit designated.
The DIT will consolidate proposals, provide guidance on clarifying requirements, and review their alignment with the digital architecture strategy and ongoing tasks. Issues concerning shared use, data connectivity, system integration and information security must be considered during the preparation of the list to minimize duplication and facilitate subsequent implementation.
We believe that the quality of the list depends primarily on accurately defining the operational problems to be addressed. At this stage, each challenge must clearly specify its objectives, scope, expected outcomes, priority level and lead unit. Detailed technical requirements will be further developed in subsequent implementation stages. The DIT will work closely with the relevant units to meet the deadline while ensuring that the challenges are grounded in practical needs and are feasible to implement.
What changes do you expect these “major challenges” to bring to the SAV’s governance capacity and the modernization of its auditing activities?
I expect the completion and implementation of these “major challenges” to bring about tangible improvements in management, leadership, administration and auditing, particularly by strengthening digital auditing and gradually making data and technology routine working tools for auditors.
Linked to the Digital Architecture Framework and the sector’s list of tasks for 2026–2030, the challenges will be implemented under a consistent strategic direction, ensuring connectivity, continuity and the shared use of platforms and data.
In governance and administration, information on tasks, progress and implementation results will be updated and consolidated promptly through shared systems. Leaders at all levels will have better access to information for monitoring, supervision and decision-making. Staff will spend less time on manual data consolidation, duplicate data entry and preparing multiple reports from the same information source. Processing work in a digital environment will also help clarify responsibilities, enhance transparency and strengthen internal inspection and supervision.
In auditing, the priority is to promote digital auditing and gradually carry out stages of the audit process in a digital environment, from information collection and audit planning to audit execution, report preparation, quality control and follow-up on the implementation of audit recommendations. Electronic audit files that are organized and managed consistently will enable information to be accessed throughout the process, facilitating coordination within audit teams, inspection, supervision and the use of previous audit results in subsequent engagements.
Another important development is stronger data analytics capabilities to support auditing. When data is standardized, connected and updated appropriately, auditors can cross-check information from multiple sources, analyze variations, identify anomalies and determine high-risk areas that require closer examination.
Where conditions permit, auditors will gradually be able to expand their analysis to entire datasets, helping them select audit focus areas and improve the quality of audit evidence. Remote data access will also help reduce the time spent collecting documents in person, minimize repeated requests for information and make more efficient use of audit resources.
Faster work processing, more effective data utilization, timelier risk identification and improved audit quality — these are the outcomes we expect from the “major challenges.”
Pham Huy Thong, Director General of the Department of Information Technology
The “major challenges” will also provide a foundation for applying artificial intelligence (AI) to document retrieval and summarization, legal document review, data analysis, the use of accumulated auditing experience and support for quality control. Given the SAV’s specific responsibilities, such applications must be accompanied by measures to ensure information security, data confidentiality, access control and the traceability of information sources. Any indicators or suggestions identified by technology must be verified and assessed by auditors against supporting evidence before conclusions are drawn.
To achieve these changes, technology implementation must go hand in hand with improvements to operational processes, higher data quality and the development of digital capabilities among staff and auditors. Each challenge must have a designated lead unit, allocated resources, an appropriate implementation roadmap and specific criteria for evaluating effectiveness.
Success will be measured by faster work processing, more effective data utilization, timelier risk identification and improved audit quality. These are the outcomes we expect the “major challenges” to deliver, contributing to stronger governance capabilities, the modernization of auditing activities and the development of an increasingly professional and modern SAV.
Thank you very much for your time.