Based on the issues initially identified in the proposed revision of the State Audit Law (SAL), Nguyen Huu Nghia, Member of the Party Central Committee and State Auditor General, has called for further review and refinement to ensure that the amendments serve two objectives: addressing shortcomings and limitations in actual auditing practice, while establishing a legal foundation that enables innovation and the future development of the State Audit Office of Vietnam (SAV).
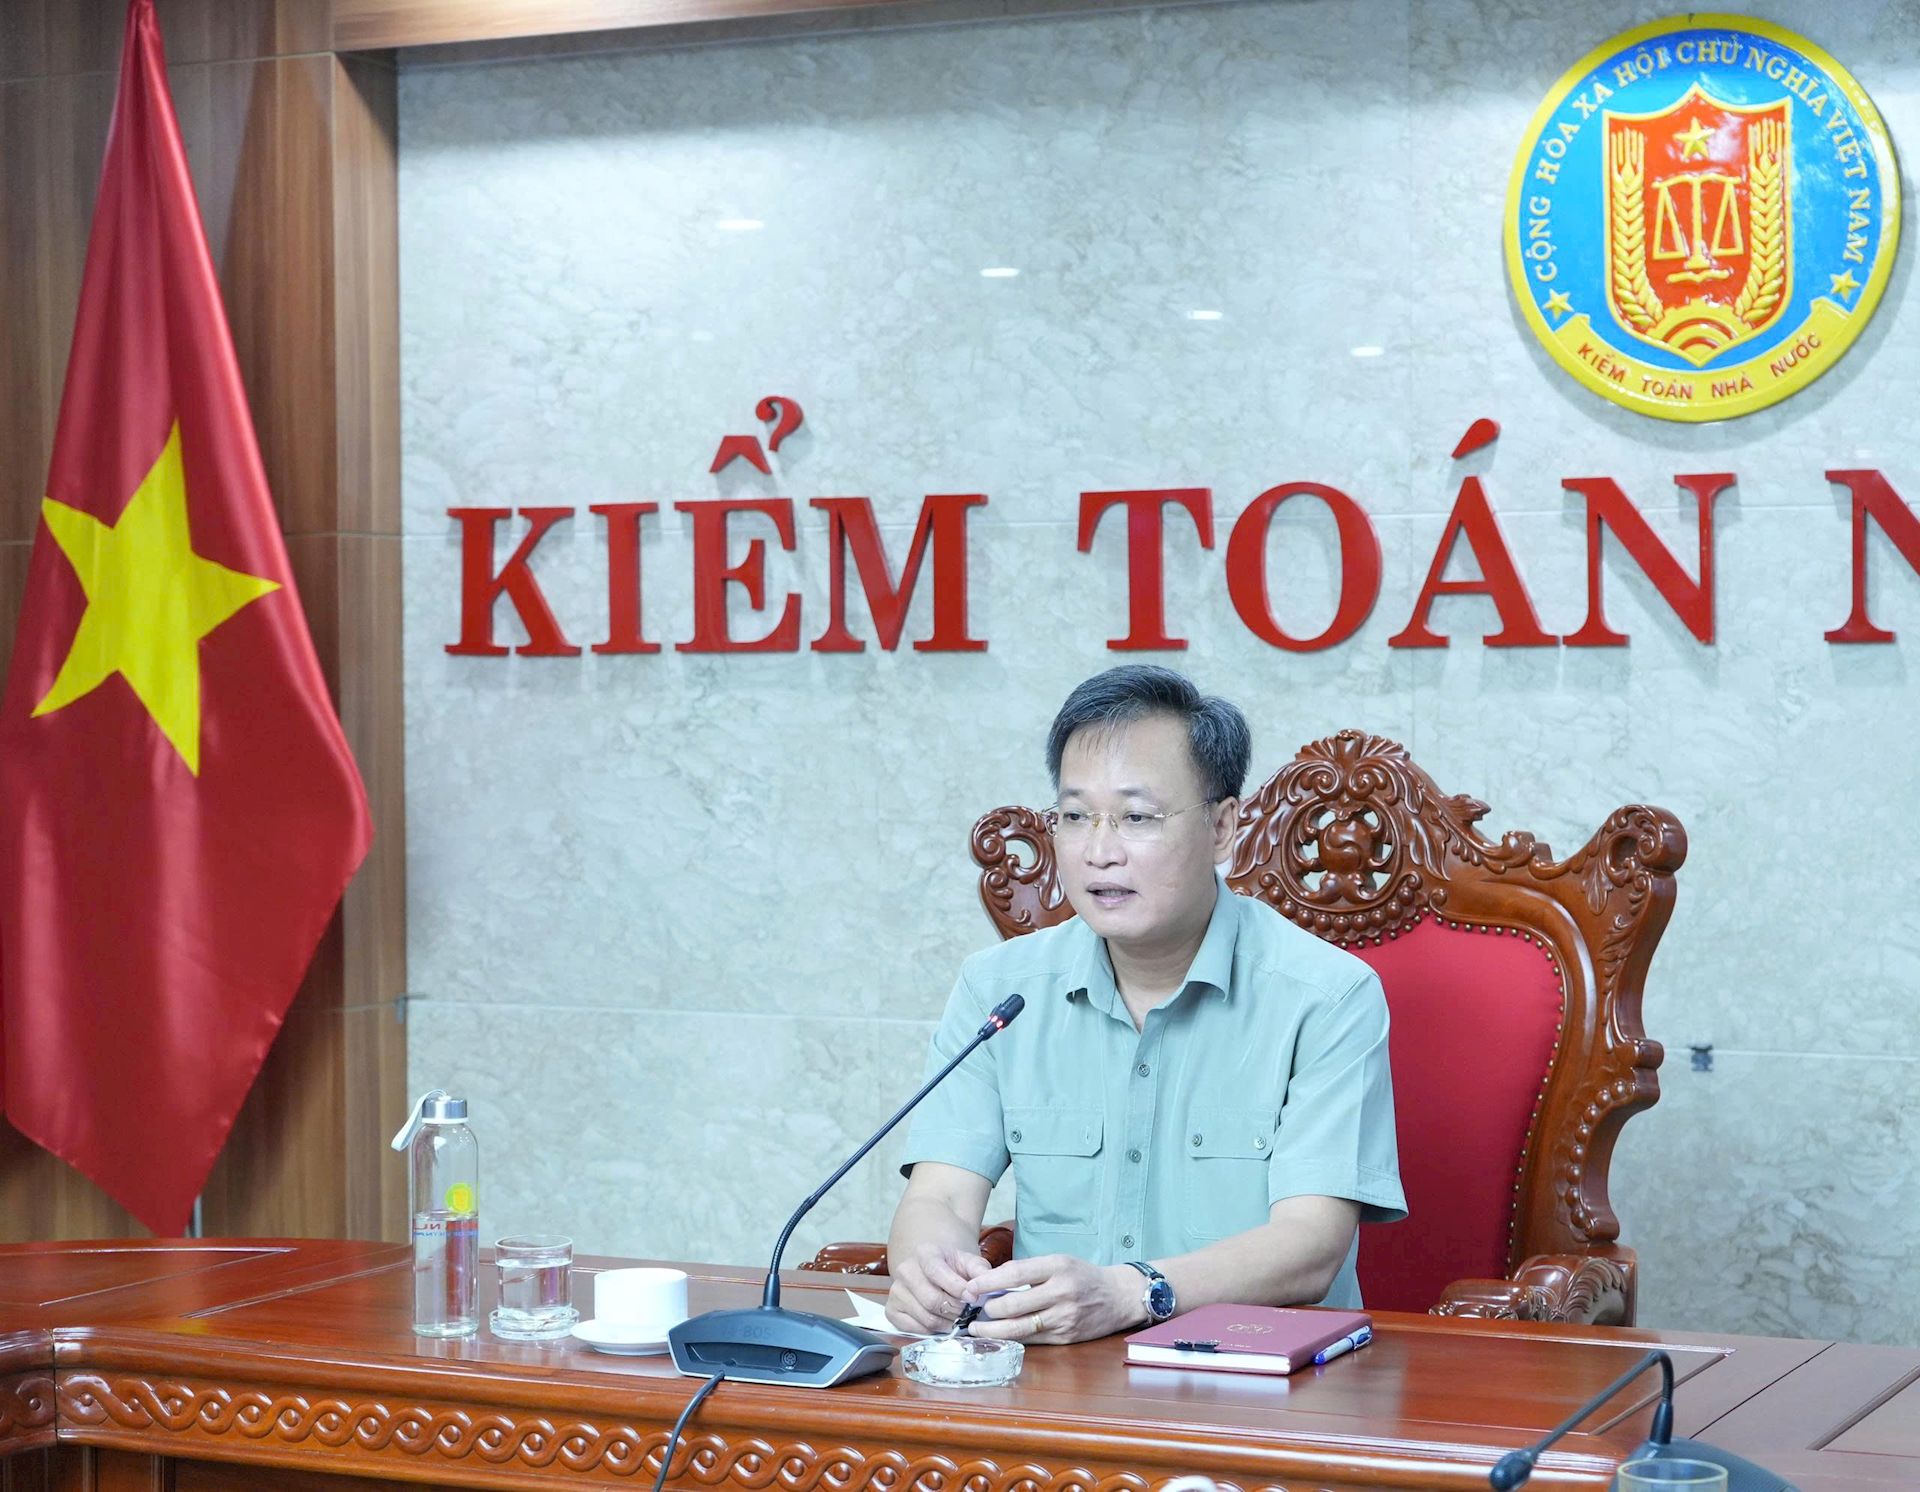
Nguyen Huu Nghia, Member of the Party Central Committee and State Auditor General, chairs the meeting. Photo: Thu Huong
On the morning of October 1, State Auditor General Nguyen Huu Nghia chaired a meeting of the Steering Committee tasked with reviewing and evaluating the implementation of the 2015 State Audit Law, as amended and supplemented in 2019, and revising the Law (the Steering Committee). The meeting aimed to discuss the proposed directions for amending and supplementing the SAL.
The meeting was held in person at the SAV headquarters and connected online to the SAV’s regional offices.
Attendees included Deputy State Auditors General Bui Quoc Dung and Doan Anh Tho, along with other members of the Steering Committee.
In his opening remarks, State Auditor General Nguyen Huu Nghia, Head of the Steering Committee, stated that, under the direction of the Standing Board of the Steering Committee, the standing body and the supporting task force had coordinated efforts to implement assigned tasks in a decisive and comprehensive manner, in accordance with the plan to review the implementation of the 2015 SAL, as amended and supplemented in 2019, and propose amendments to meet the SAV’s requirements and responsibilities in the new context.
The Standing Board had held meetings with the standing body and the supporting task force to establish clear and specific directions for reviewing the existing Law and preparing the draft amended and supplemented SAL. These efforts had yielded initial results in reviewing and assessing the Law, particularly in identifying shortcomings and obstacles in the current SAL that need to be addressed.
Deputy State Auditors General Bui Quoc Dung and Doan Anh Tho attend the meeting. Photo: Thu Huong
The State Auditor General emphasized that the revision of the SAL aims to resolve obstacles arising from actual auditing activities while establishing a legal foundation and institutional environment conducive to innovation and the development of the SAV.
In particular, the revision process must involve thorough comparison and cross-referencing to ensure that the Law institutionalizes and aligns with the Strategy for the Development of the State Audit Office of Vietnam through 2035, with a vision to 2045.
“We are carrying out two tasks toward the same ultimate goal: ensuring that the strategic direction is institutionalized in the Law,” the State Auditor General emphasized.
In light of this approach, he called on Steering Committee members to focus their discussions and provide opinions on the key directions for amending and supplementing the SAL.
Proposals to Amend, Supplement and Refine Key Provisions
At the meeting, Hoang Phu Tho, Director General of the Department of Legal Affairs, presented a report on implementation progress and several proposed directions for amending and supplementing the SAL on behalf of the Steering Committee’s standing body.
Director General Hoang Phu Tho stated that, based on the outline of the report reviewing the implementation of the SAL and proposing amendments and supplements, together with the State Auditor General’s directions, the Standing Board had proposed focusing the revision on several major areas.
These areas include amending, supplementing and refining provisions concerning the SAV’s institutional standing; its important role in the state management system, public governance, the national integrity framework and the control of power; and its role in preventing and combating corruption, wastefulness and misconduct in the management and use of public finances and public assets.
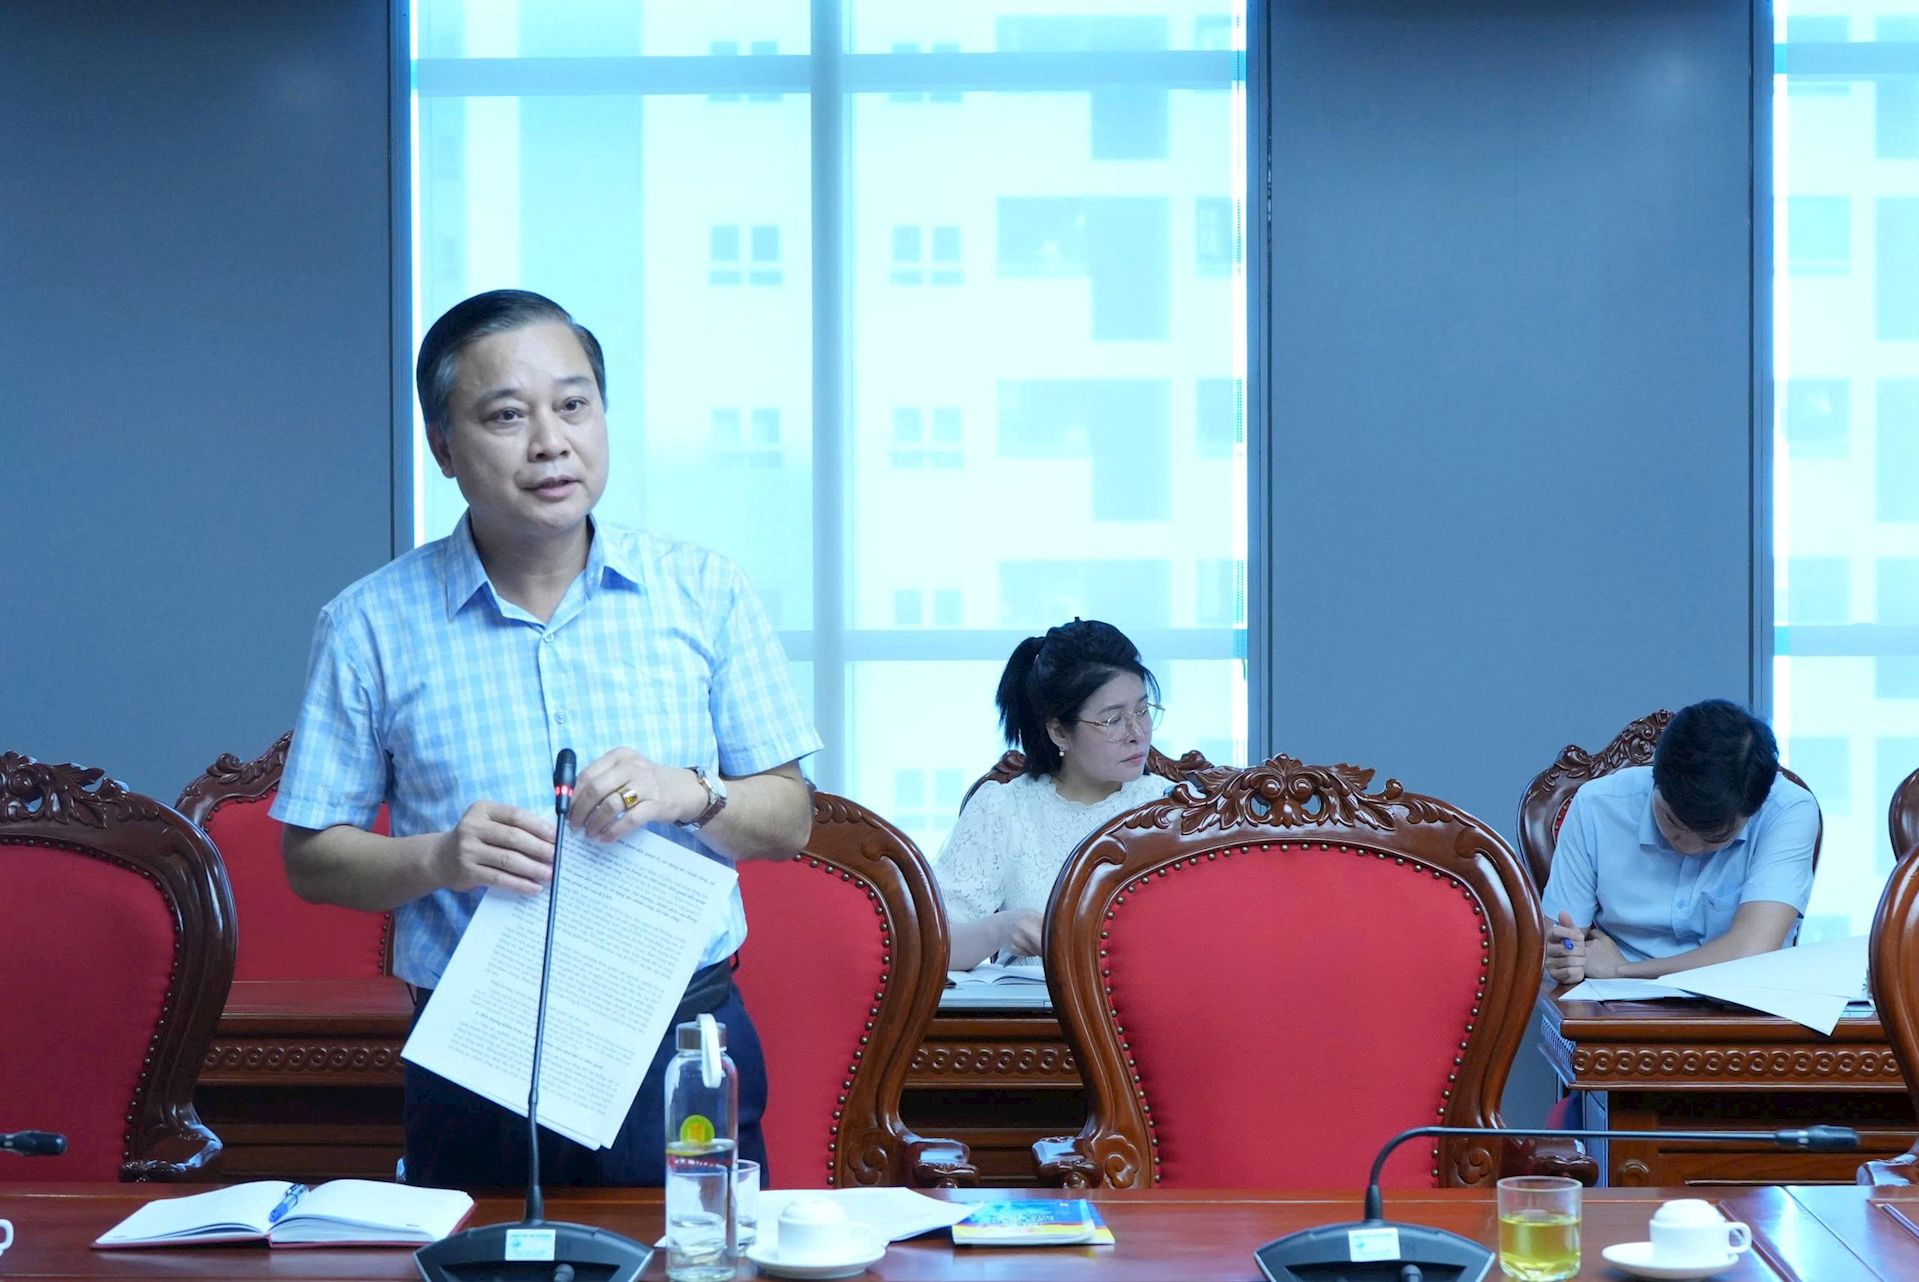
Hoang Phu Tho, Director General of the Department of Legal Affairs, reports on implementation progress and proposed directions for amending and supplementing the SAL. Photo: Thu Huong
The proposed revisions reaffirm the SAV’s status as an independent constitutional institution under the leadership of the Communist Party of Vietnam, directly and regularly led by the Politburo and the Secretariat. They also seek to clarify the SAV’s primary responsibility for state inspection and supervision of the management and use of public finances and public assets.
The proposed amendments also include adding a separate article specifying the objectives of the SAV’s activities, as well as reviewing and refining provisions governing the scope, types and content of audits.
Notably, the proposals include revising provisions on the SAV’s supervisory functions, with a view to empowering the SAV to conduct regular and continuous monitoring and supervision of the management and use of public finances and public assets based on information and data.
At the same time, the proposals call for further clarification of auditees within the broader system of Party inspection, examination and supervisory bodies, as well as clearly defining the responsibilities of relevant agencies, organizations, units and individuals involved in supervisory and auditing activities.
To enhance the State Auditor General’s initiative while ensuring transparency in the principles and conditions for selecting, adding or removing auditees from the audit plan, the Standing Board has proposed revising and supplementing provisions on the authority to decide on audits and manage audit plans.
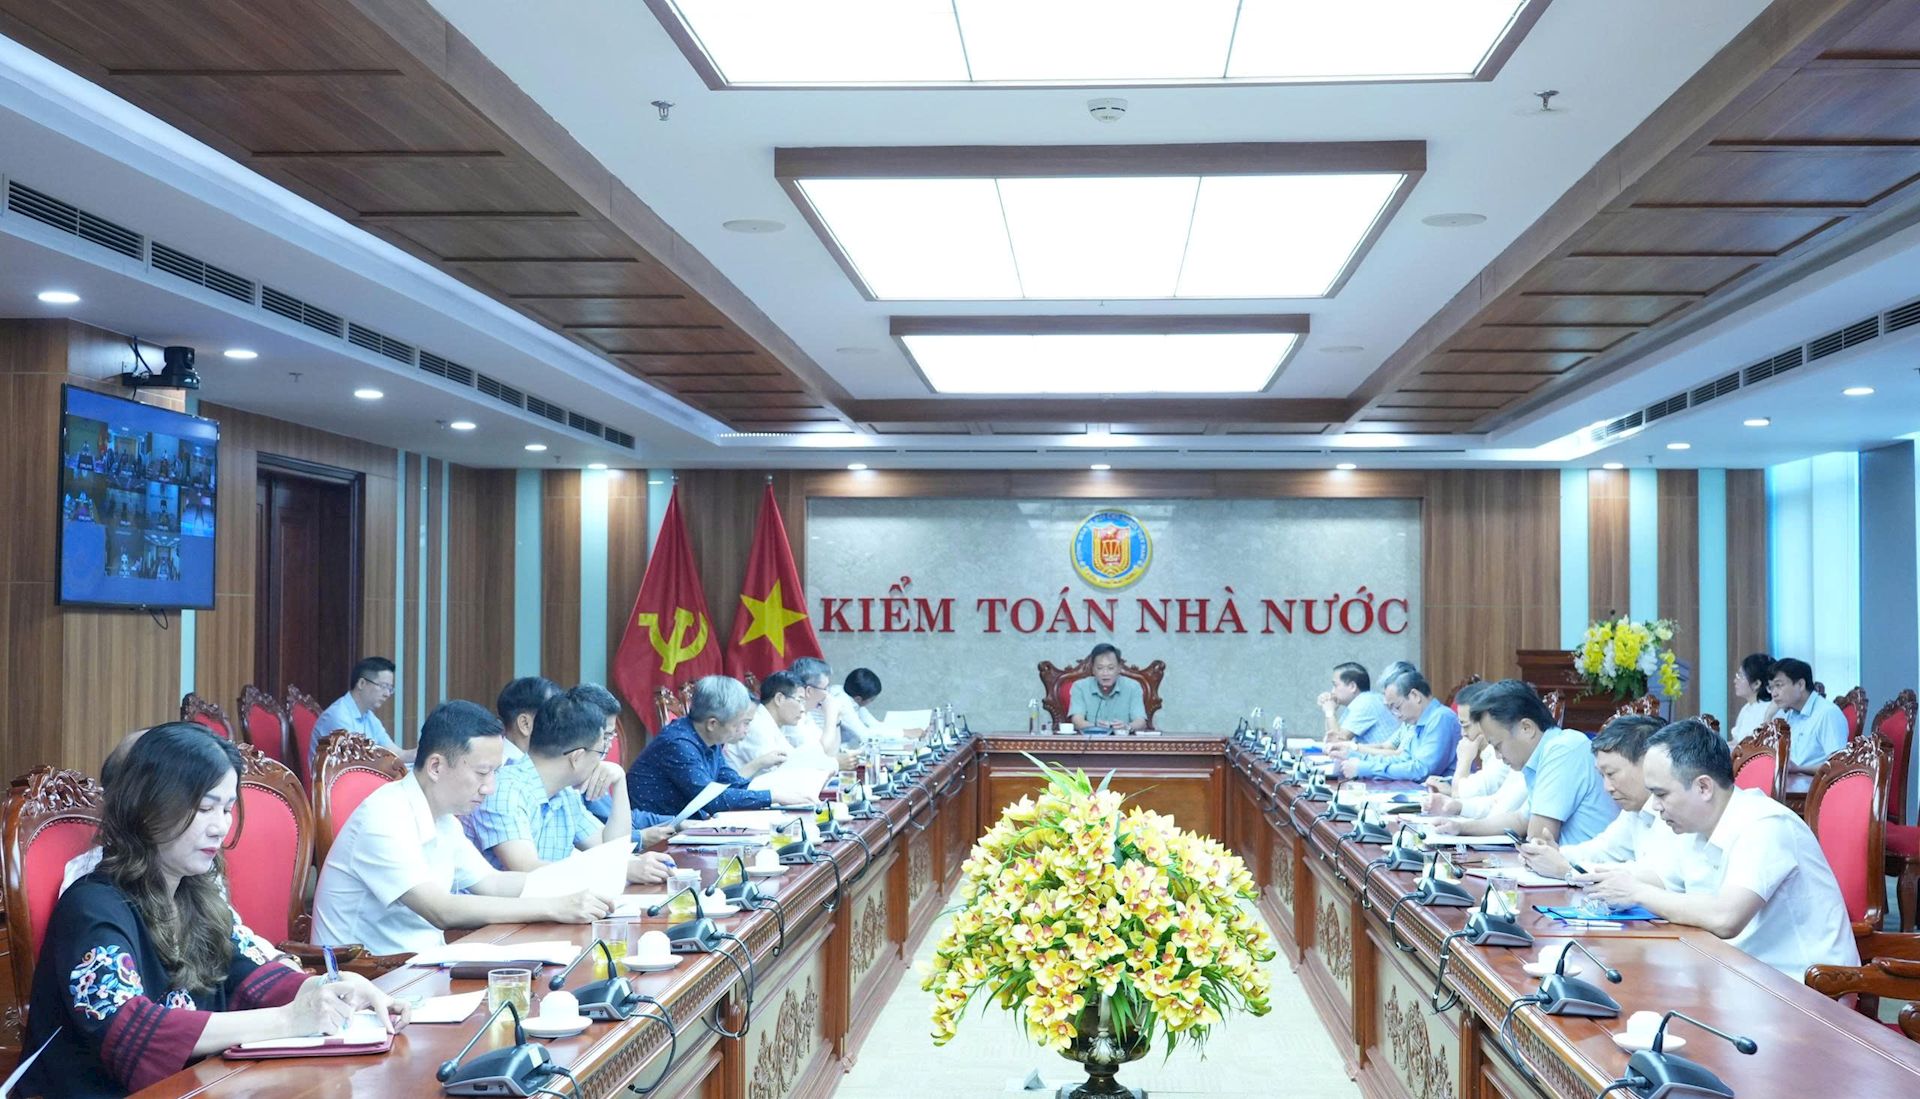
Overview of the meeting. Photo: Thu Huong
The proposed revisions also address decentralization and delegation of authority in audit organization and operations; auditor positions, qualifications and protection mechanisms; audit duration and deadlines for preparing and issuing audit reports; auditing in digital environments; audit quality control and risk management; implementation of audit conclusions and recommendations; operating budgets; and remuneration and policies for state auditors.
Further Review and Refinement to Ensure Consistency and Coherence
At the meeting, Steering Committee members broadly agreed with the proposed directions for amending and supplementing the SAL. Their discussions also focused on analyzing and clarifying the proposed revisions, particularly those concerning the SAV’s roles and responsibilities; the scope, types and content of audits; auditees and the responsibilities of relevant parties; and the authority to decide on audits and manage audit plans.
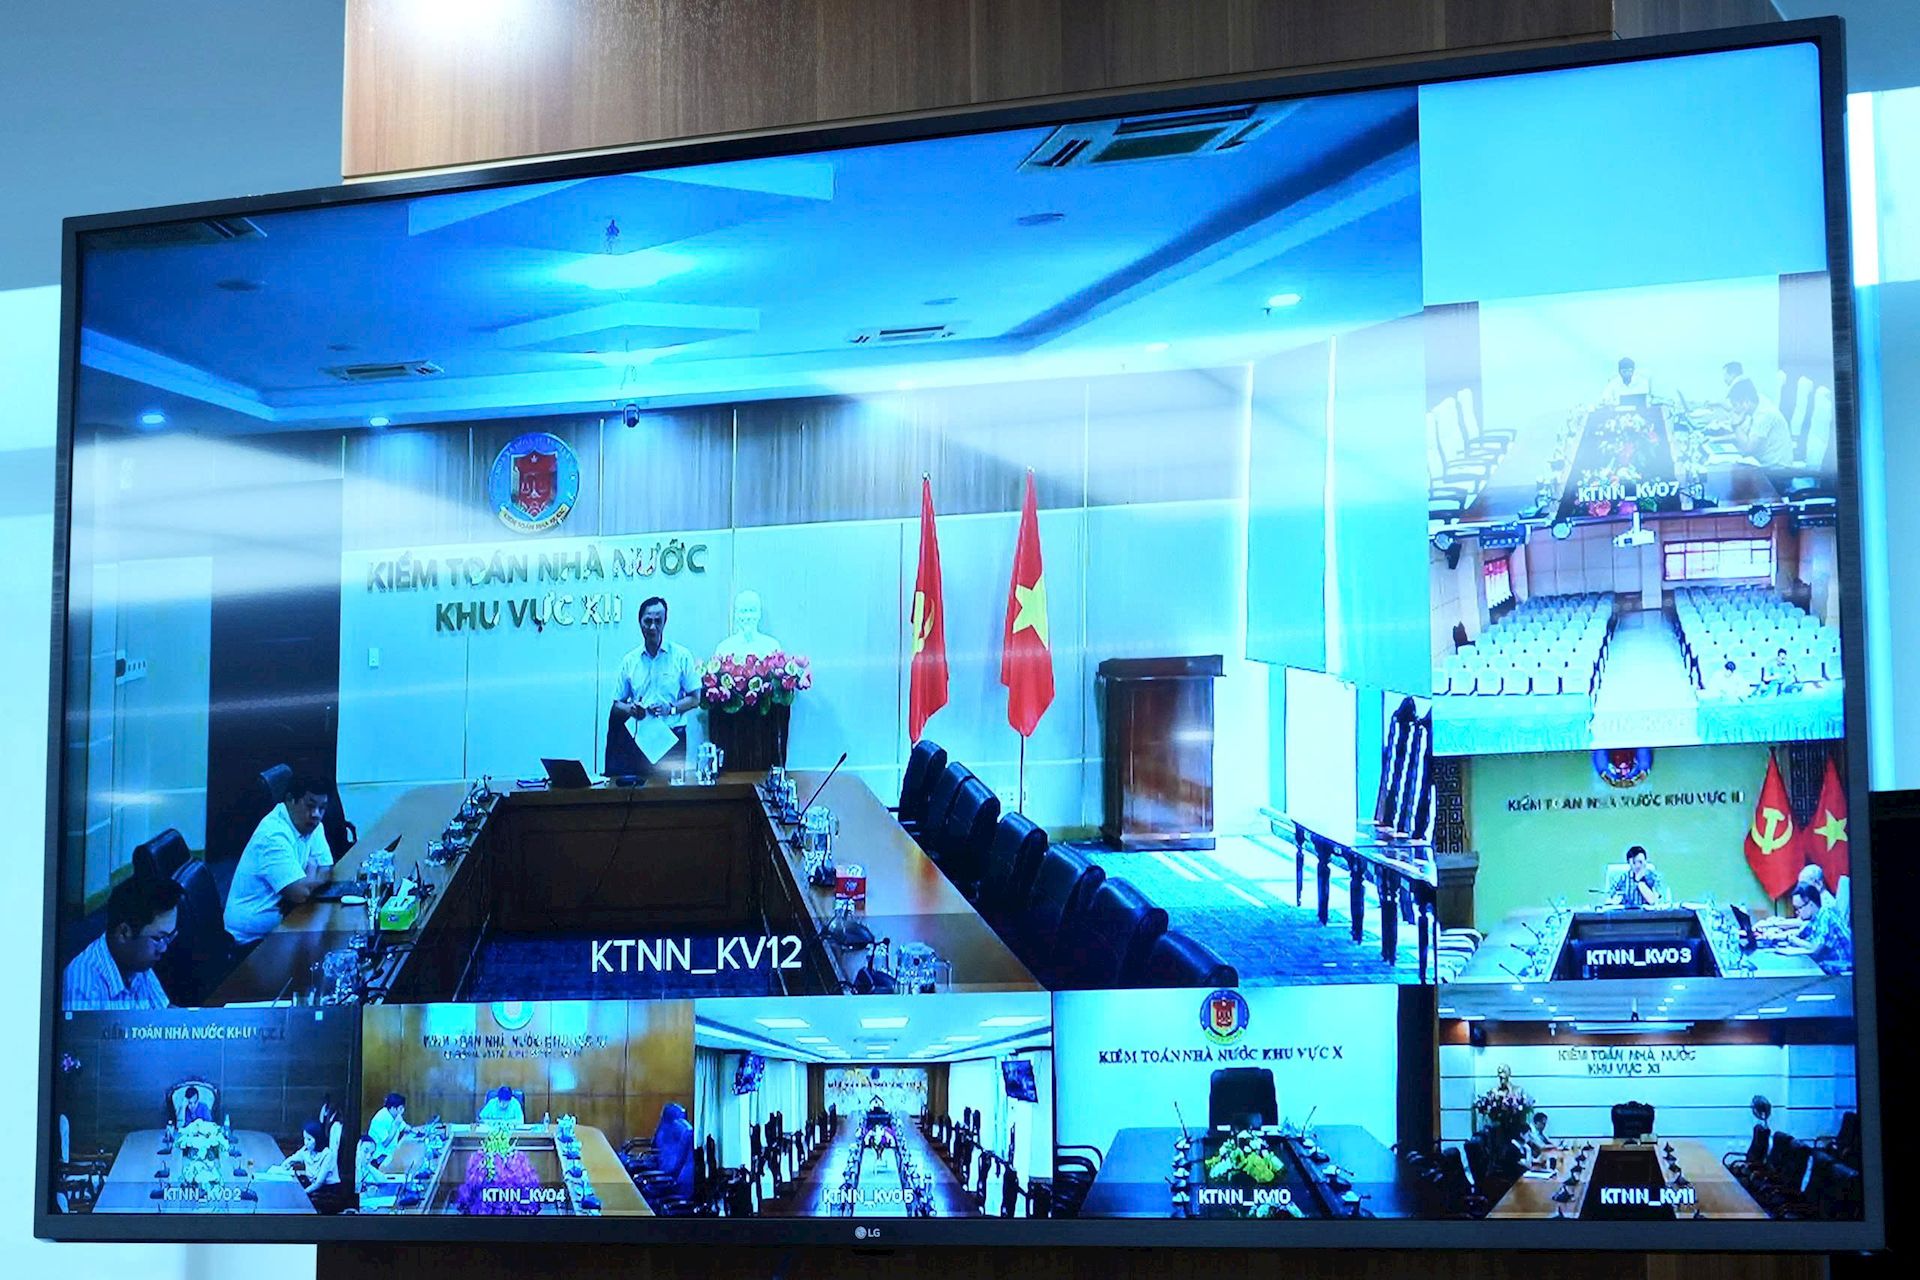
Regional SAV offices participate in the meeting via videoconference. Photo: Thu Huong
In his concluding remarks, State Auditor General Nguyen Huu Nghia emphasized that the issues identified so far were important initial findings. However, further review of the implementation of the SAL and practical auditing activities could reveal additional issues requiring amendments and supplements.
He urged the subcommittees to promptly complete their assessments and consolidate recommendations and proposals for revising the SAL within the deadlines set by the Steering Committee, ensuring that the results are available in a timely manner to support the legislative revision process.
Having considered the report from the Standing Board and the opinions expressed at the meeting, the State Auditor General called on Steering Committee members to continue studying and providing feedback to refine the proposed directions for revision. The standing body and supporting task force were also asked to continue reviewing, revising and finalizing the proposed provisions to ensure that they reflect practical requirements and maintain consistency and coherence throughout the draft Law.
The Steering Committee is expected to submit the proposed directions for revising the SAL to the Executive Committee of the SAV Party Committee for approval in October. These directions will serve as the basis for preparing draft reports and the draft revised Law.