As of July 31, 2026, the implementation rate of audit conclusions and recommendations for the 2026 audit year concerning the 2024 budget year increased by 52.06% compared with the same period last year. This result demonstrates the decisive direction of the Party Committee and leadership of the State Audit Office of Vietnam (SAV), as well as the efforts of units across the sector. However, many recommendations remain outstanding due to objective factors and the process of organizational restructuring, requiring the SAV to clearly distinguish the causes, properly identify responsibilities, and address each bottleneck, thereby improving the effectiveness and efficiency of implementing audit conclusions and recommendations.
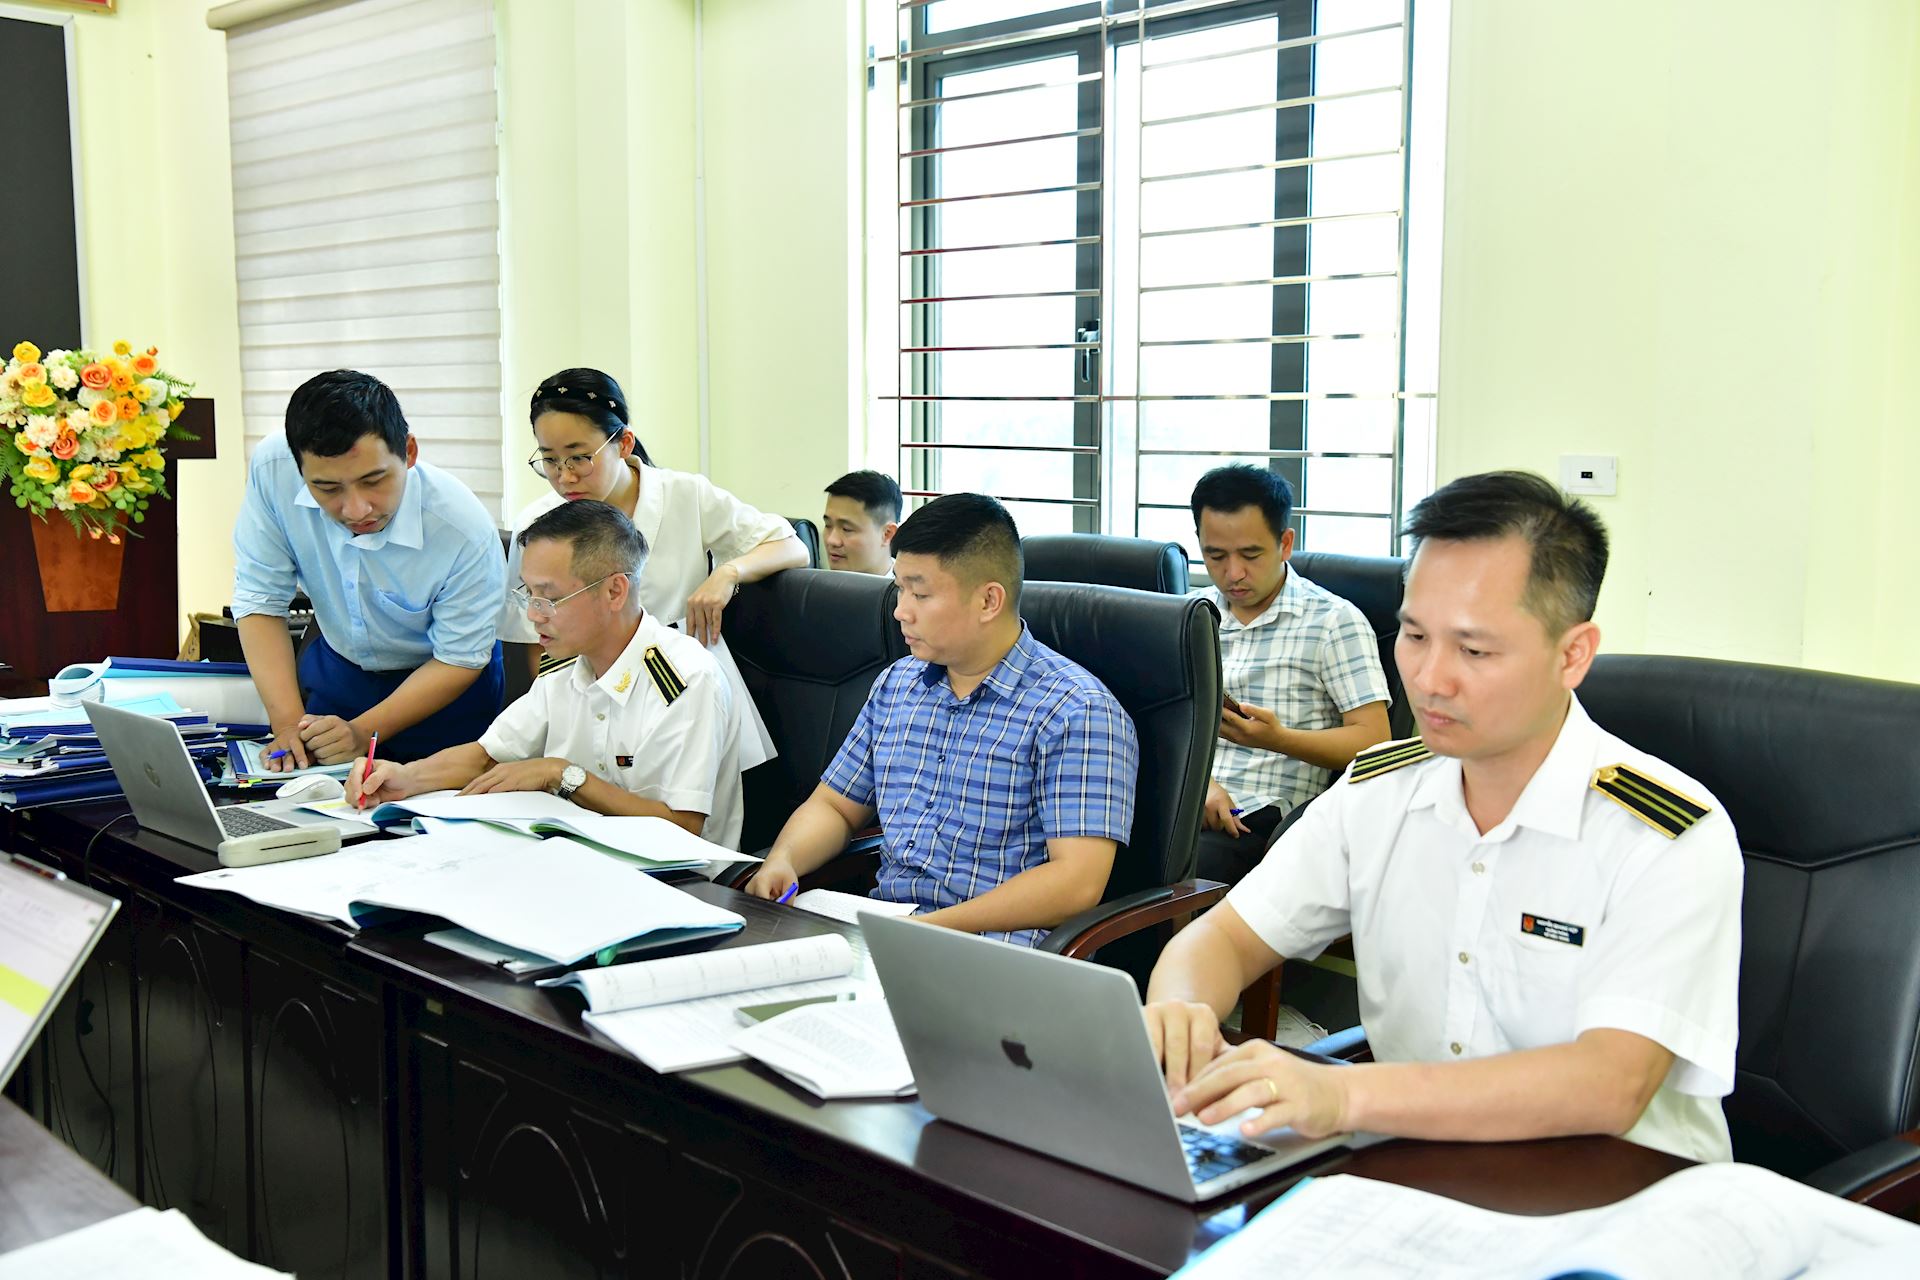
SAV takes decisive measures to accelerate the implementation of audit conclusions and recommendations. Photo: TL
Financial Recommendation Implementation Rate Reaches Nearly 73%, Up 52.06%
According to the SAV's report, as of July 31, 2026, for recommendations denominated in local currency, the total amount of financial and other recommendations implemented reached VND 29,942.10 billion out of a total adjusted amount of VND 41,039.27 billion, representing an implementation rate of 72.96%. This rate increased by 52.06% compared with the same period in 2025, when the rate as of July 31, 2025, was only 20.9%.
By audit-leading unit, implementation rates ranged from 41.55% to 99.86%. Several units achieved rates above 90%, including Specialized Audit Departments Ia, II, III, and VI, as well as Regional Audit Offices VI, VII, VIII, XI, and XII.
For recommendations denominated in foreign currencies, the total amount implemented reached USD 111,578,235.50 out of a total of USD 129,242,469.89, representing an implementation rate of 86.33%.
In addition to implementing recommendations concerning the 2024 budget year, in 2026, units continued to implement recommendations relating to state budget years from 2023 and earlier, amounting to VND 4,360.84 billion. As of July 31, 2026, the cumulative amount of financial and other recommendations from budget years 2023 and earlier that had been implemented reached VND 526,414.28 billion out of a total adjusted amount of VND 578,838.94 billion, representing an implementation rate of 90.94%.
Practical Solutions from Leading Units
Contributing to the overall results of the sector, leading units have adopted various practical and innovative solutions to accelerate the implementation of audit conclusions and recommendations.
For example, at Specialized Audit Department Ia — the leading unit across the SAV and among specialized audit departments in terms of the implementation rate of audit conclusions and recommendations for the 2024 budget year — Deputy Auditor General of Specialized Audit Department Ia Thai Thi Lan said that, recognizing that the value of auditing lies not only in identifying errors and making recommendations for corrective action, but more importantly in turning recommendations into substantive changes in the management and use of public resources at audited entities, the Party Committee and leadership of Specialized Audit Department Ia have consistently identified the monitoring, urging, and inspection of the implementation of audit recommendations as a key task, receiving attention from the very beginning of the work planning process.
In response to the specific characteristics of the defense sector, Specialized Audit Department Ia has implemented measures to ensure that audit recommendations comply with the law, are based on assessment results and sufficient evidence, closely reflect practical circumstances, and are highly feasible. With a proactive approach to resolving difficulties and innovating implementation methods, the unit has coordinated with relevant agencies of the Ministry of National Defense to classify recommendations, engage in dialogue, and provide guidance on handling them. Since 2025, professional divisions have been assigned to directly monitor, urge, and inspect the implementation of recommendations at designated entities and periodically report to the General Affairs Division for review and consolidation. Thanks to the synchronized implementation of these measures, the implementation rate of audit recommendations for the 2024 budget year at Specialized Audit Department Ia reached 99.86%.
Regional Audit Office XII ranked first among regional audit offices and second across the entire SAV sector, with an audit recommendation implementation rate of 98%, representing a cumulative implementation of VND 6,167.412 billion out of a total of VND 6,294.702 billion. Notably, this is also one of the largest absolute amounts across the sector.
Deputy Auditor General of Regional Audit Office XII Mai Van Tan said that when the locality transitioned to the two-tier local government model, the unit prepared a detailed list for each locality and coordinated with the former Regional Audit Offices VIII and XII to receive dossiers, reconcile data, and clarify the causes of outstanding recommendations.
Regional Audit Office XII also proactively worked with the People's Committees of provinces and centrally governed cities to clearly identify the responsible entities following organizational changes and subsequently issued reminders. The unit strictly adheres to the principle that the retirement or transfer of an individual involved does not terminate a recommendation; the responsibilities of the relevant organization or individual must still be considered in accordance with regulations.
In addition, the unit assigned auditors to monitor each report, from evidence collection through data entry into the software system. For problematic recommendations, audit and resolution teams worked directly with the relevant entities to agree on solutions and resolve the issues conclusively, rather than relying solely on administrative reminders.
Identifying Recommendations That Are No Longer Feasible to Implement
Although the overall implementation rate of recommendations across the sector has increased significantly, the number of outstanding recommendations remains substantial. For the 2024 budget year, VND 11,097.17 billion in financial recommendations denominated in local currency (27.04%) and USD 17,664,234.39 in foreign-currency recommendations (14%) had not yet been implemented, primarily because the audited entities had not taken action.
For budget years from 2023 and earlier, the outstanding amount was VND 52,424.66 billion, of which VND 30,052.82 billion (57.33%) originated from audited entities due to financial difficulties, cessation of operations, missing supporting documents, or disagreement with the recommendations.
Notably, some recommendations concerning financial adjustments, amendments to legal normative documents, and accountability measures were properly issued but can no longer be implemented because the relevant entities have been dissolved or declared bankrupt, or the individuals concerned have died, gone missing, or lost their civil capacity.
The process of merging and consolidating ministries, sectors, and localities, as well as the implementation of the two-tier local government model, has also resulted in some recommendations becoming impractical, difficult to implement, or lacking a clearly identified entity responsible for continued implementation.
Coordinated Solutions Toward Conclusive Resolution of Recommendations
To improve the implementation rate of recommendations, the Party Committee and leadership of the SAV have strengthened leadership and direction and issued directives, resolutions, and documents to monitor, urge, inspect, and supervise implementation. The SAV issued Circular No. 01/2026/TT-KTNN stipulating procedures for monitoring and inspecting implementation results; provided guidance on handling cases involving entities following mergers, divisions, and consolidations; strengthened coordination with ministries, sectors, and localities to resolve emerging difficulties; and published lists of organizations and individuals that have not implemented or have delayed implementation of audit conclusions and recommendations on the SAV's Electronic Information Portal.
In the coming period, the SAV requires specialized and regional audit offices to improve audit quality, ensuring that audit conclusions and recommendations comply with the law, are supported by sufficient evidence, are consistent with practical circumstances, and are feasible. At the same time, coordination with ministries, sectors, localities, and audited entities must be strengthened to clearly identify responsible entities, clarify causes and responsibilities, and prevent recommendations from being left unresolved following organizational restructuring.
SAV leadership requested the General Affairs Department to advise on the public disclosure of the results of implementing audit recommendations following the Second Session of the 16th National Assembly. At the same time, the Department is required to complete the publication of lists of entities, organizations, and individuals that have not implemented audit conclusions and recommendations through the prescribed channels before October 15, 2026.
The SAV also requires clear identification of the responsibilities of heads of units that deliberately fail to fully and promptly implement recommendations, so that competent authorities can take appropriate action; and strict handling of administrative violations in accordance with the Ordinance on Sanctions for Administrative Violations in the State Audit Sector. Where failure to implement recommendations is found to have caused serious consequences or shows signs of criminal activity, the Auditor General must immediately report to the Auditor General of the SAV for the dossier to be promptly transferred to the investigating agency within September 2026.
For cases involving prolonged violations where no other measures have been taken to address audit recommendations, the Auditor General will consider notifying the People's Procuracy at the same level to initiate civil proceedings to protect public interests or vulnerable groups in accordance with Article 9 of Resolution No. 205/2025/QH15 of the National Assembly.
The SAV requires focused review and conclusive resolution of outstanding recommendations before September 30, 2026; detailed classification of recommendations that are impossible to implement due to force majeure or for which the responsible entity has not yet been identified; and reporting to the competent authorities. The implementation results of audit recommendations shall serve as one of the criteria for assessing and rating the level of task completion of SAV collectives and individuals.
The period from now until September 30, 2026, is limited, requiring units across the sector to remain proactive and decisive, clarify the causes, properly identify responsibilities, and address each outstanding issue. Strict implementation of the SAV leadership's directives will contribute to ensuring that audit conclusions and recommendations are implemented substantively, thereby enhancing the effectiveness and efficiency of audit activities and strengthening discipline and order in the management and use of public finances and assets.